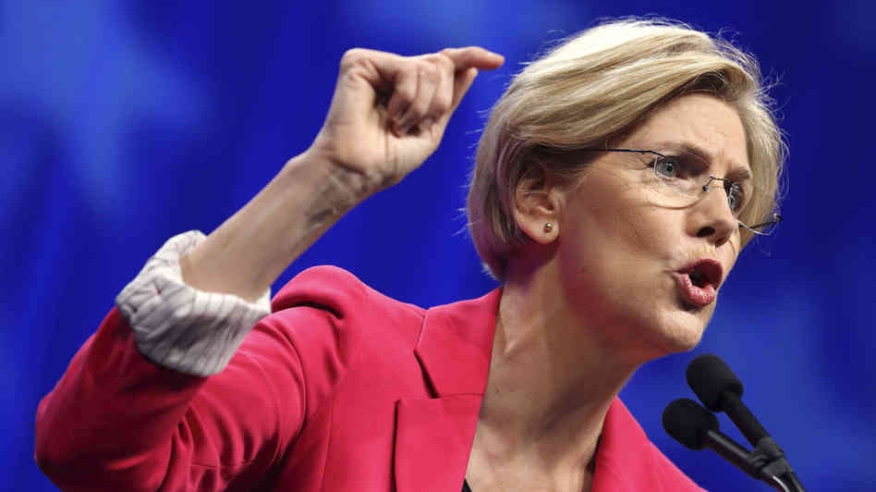
Sen. Elizabeth Warren (D-MA) has offered a harsh criticism of the $5.1 billion settlement by Goldman Sachs to resolve federal charges related to its underwriting and sale of problematic mortgage-backed securities (MBS) between 2005 and 2007.
The settlement, which was announced on Friday, will conclude the ongoing investigation of the New York-based firm by Residential Mortgage-Backed Securities Working Group of the U.S. Financial Fraud Enforcement Task Force and will also resolve claims brought by the U.S. Department of Justice, the National Credit Union Administration, the Federal Home Loan Banks of Chicago and Seattle, and the New York and Illinois Attorneys General. In announcing the settlement, Goldman Sachs made no admission of guilt or error, and no executive from the New York-based financial giant will face criminal or civil charges.
Sen. Warren used her Facebook page to denounce the agreement, noting that the settlement sum was “barely a fraction of the billions investors lost” while arguing that Goldman Sachs was not properly penalized for its actions.
“That’s not justice – it’s a white flag of surrender,” she wrote. “It’s time to end this farce. These companies think they’re above the law – and too many government officials go along with them. A first step would be to pass the bipartisan Truth in Settlements Act to shine more light on these backroom deals. A second step would be to get government officials who have the backbone to fight back.”
Warren’s comments were echoed by the nonprofit U.S. Public Interest Research Group (U.S. PIRG), which noted that Goldman Sachs would enjoy a sizeable tax deduction benefit from the settlement.
“The proposed deal includes a substantial $2.385 billion civil monetary penalty, an $875 million cash payment, and $1.8 billion in consumer relief,” the U.S. PIRG observed in a press statement. “The civil monetary penalty is non-deductible as per the tax code, but the remaining $2.675 billion is entirely tax deductible for the bank as an ordinary business expense. By law, fines and penalties cannot be treated as regular business expenses, and therefore are not tax deductible. The cash payment and consumer relief portions of the payment, however, are not specifically designated as penalties and can therefore be deducted from Goldman’s taxes. The bank reported that the settlement would reduce its earnings in this period by roughly $1.5 billion on an after-tax basis. The foregone tax revenue must ultimately be paid for by ordinary taxpayers in the form of higher individual taxes, program cuts, and more national debt.”
Goldman Sachs also figured prominently in last night’s debate among the candidates for the Democratic presidential nomination, with Vermont Sen. Bernie Sanders pointedly reminding Hillary Clinton of her business relationship with the company.
“I don’t get personal speaking fees from Goldman Sachs,” he stated when the debate focused on Wall Street-related issues, reminding Clinton, “You've received over $600,000 in speaking fees from Goldman Sachs in one year.” Clinton did not acknowledge Sanders’ statement, which was greeted by a mix of booing and applause from the debate audience