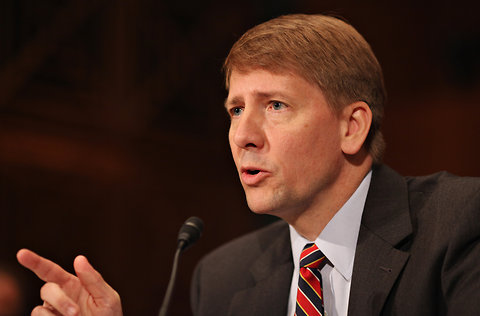
 Richard Cordray used an appearance before the House Financial Services Committee to trumpet the achievements of the Consumer Financial Protection Bureau (CFPB) in policing the mortgage banking industry.
In his written testimony presented this afternoon as part of the CFPB’s sixth Semi-Annual Report to the Congress and the President, Cordray insisted that the bureau has been responsible for improving consumer safety in the mortgage market.
“Our Ability-to-Repay rule, also known as the Qualified Mortgage rule, put new guardrails in place to prevent the kind of sloppy and irresponsible underwriting that had precipitated the crisis,” Cordray wrote, referring to the 2008 financial crash. “Our mortgage servicing rules offered new and stronger protections to homeowners facing foreclosure. And our other rules addressed significant problems in the mortgage market deemed in need of repair. During this period, we continued our extensive work on regulatory implementation by providing tools and resources to assist industry in implementing our final rule to consolidate and streamline mortgage disclosure forms at both the application stage and the closing stage.”
Cordray also addressed the CFPB’s oversight of community banks and credit unions, which has created tension due to regulatory burdens that hampered these smaller institutions’ ability to originate home loans.
“As we have demonstrated again and again, we are committed to an even-handed approach to rulemaking that maintains important protections for consumers while listening to all stakeholders and making changes where appropriate to get things as right as we can,” Cordray continued, acknowledging that community banks and credit unions were not responsible for the 2008 events.
Cordray also trumpeted efforts by the bureau to seek financial penalties from companies that were charged by the bureau with inappropriate actions – citing issues relating to credit cards, payday lending and phony debt relief operations, but did not make any mention of penalties against mortgage lenders.
“To date, we have helped secure orders through enforcement actions for more than $5.3 billion in relief to more than 15 million consumers who fell victim to various violations of federal consumer financial laws,” Cordray said. “During the period of the Semi-Annual Report, we brought enforcement actions that secured $1.6 billion in relief for consumers. Those actions included $727 million in relief to consumers who were harmed by a company’s deceptive marketing of credit card add-on products. They included $92 million in debt relief for 17,000 servicemembers and other consumers who were harmed by a predatory lending scheme. And they included $225 million in relief for consumers who were harmed by other deceptive and discriminatory credit card practices. We also filed suit to hold a company accountable for operating a debt collection lawsuit mill that intimidated consumers with deceptive court filings, totaling more than 350,000 lawsuits in four years in Georgia alone.”
Cordray added that the Bureau’s Office of Consumer Response has accepted more than 540,000 consumer complaints, but he did not say how many of these complaints were affirmed and how many were later dismissed.