The regulator of the Federal Home Loan Banks (FHLBanks) is not pleased with how these institutions are conducting business, and he is not shy about stating his views.
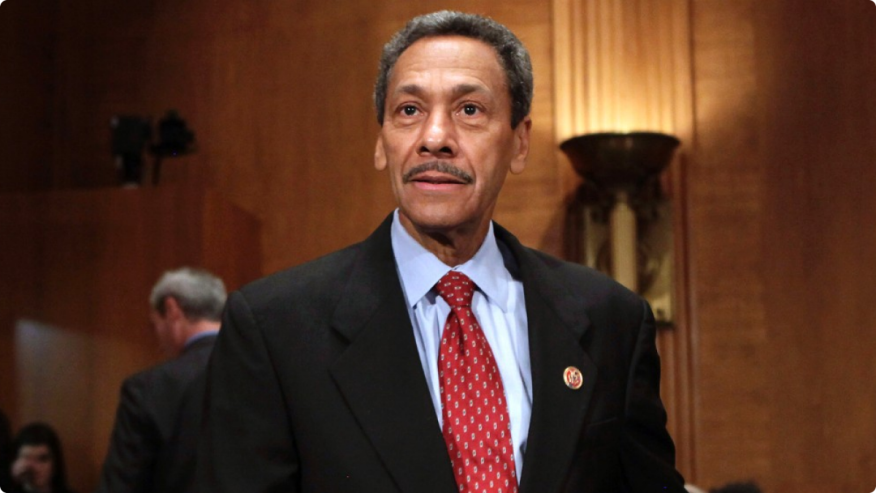
In a speech delivered yesterday before the 2016 Federal Home Loan Bank Directors' Conference in Washington, D.C., Federal Housing Finance Agency (FHFA) Director Mel Watt did not mince words on how these institutions operate.
“We remain concerned about the extent to which some FHLBanks continue to rely on non-core mission assets to support their earnings,” he said, noting a mere two percent drop in the overall level of FHLBank assets held in investments between 2014 and 2015. Watt spelled out three key areas where he expected the FHLBanks to show signs of improvement.
“First, for those FHLBanks that have large exposures to insurance company members, we continue to encourage you to exercise due diligence to establish conservative haircuts and controls over collateral pledged by them in support of their advances,” Watt said. “While lending to insurance companies remains an important FHLBank activity, the FHLBanks face different risks when lending to these companies compared to other members. Second, the system as a whole, and some FHLBanks in particular, have advances concentrated to a few large members. Across the system, the top four borrowers accounted for 24 percent of aggregate advances at the end of 2015. Business concentration with a small number of borrowers can threaten profitability if one or more of these borrowers suddenly decrease their demand for advances.
“Third,” he continued, “concerns have recently arisen about and FHFA has started a review of the system's increased usage of short-term funding in the form of discount notes. At year-end 2015, discount notes constituted 54 percent of outstanding FHLBank debt, compared to 43 percent at year-end 2014 and 39 percent at year-end 2013. Short-term funding requires more frequent debt rollover than longer-term funding and this could become a safety and soundness issue if liquidity dries up unexpectedly.”
Watt also stated that the FHFA is placing a greater emphasis on issues related to the inclusion of women and minorities in FHLBank activities. He said his agency plans to “propose an amended minority and women inclusion regulation that would direct all of our regulated entities to undertake diversity and inclusion strategic planning, either on a stand-alone basis or as part of their overall business strategic planning process.”
Watt also said the FHFA might propose a new guidance “about incorporating diversity and inclusion in assessing FHLBank executive incentive compensation programs,” and he suggested the FHLBanks implement their own diversity and inclusion goals in both their interactions with lenders serving predominantly nonwhite communities and ensuring greater diversity within their organizations and in their vendor supply networks.