MBA’s Stevens Points to Political Impact on Housing’s Future – NMP Skip to main content

MBA’s Stevens Points to Political Impact on Housing’s Future

May 22, 2018
The new push by the Trump Administration to bring the government-sponsored enterprises (GSEs) out of their 11-year federal conservatorship could result in some negative impacts on the wider mortgage market, according to an opinion piece by David H. Steven

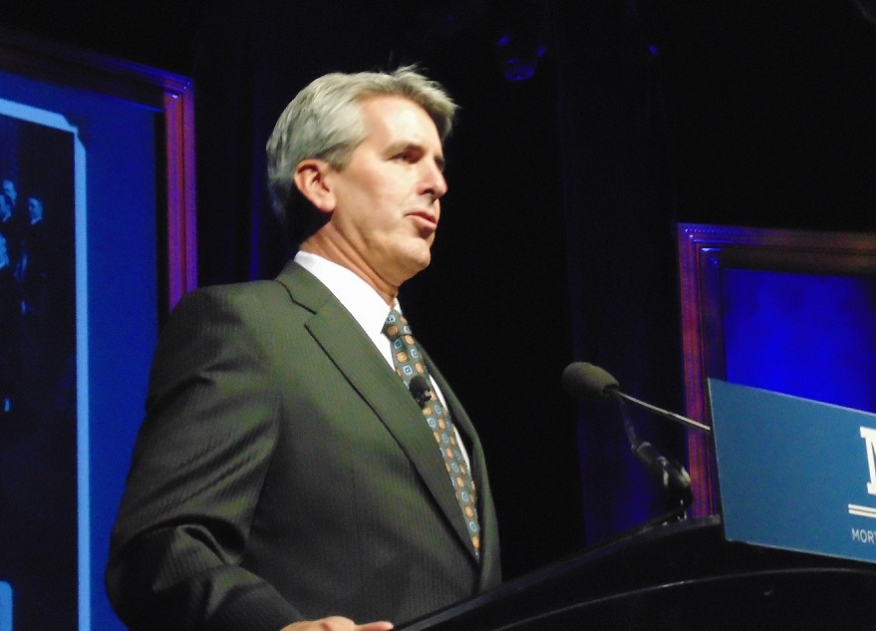
In his final trade conference appearance as President and Chief Executive of the Mortgage Bankers Association (MBA), David H. Stevens warned that potential changes in the political landscape could bring a reshuffling of how Washington views the housing and mortgage markets.
 
Stevens linked one of the key issues facing today’s housing market to the post-recession regulatory regimen.
 
“The real problem is that there is not enough housing inventory,” said Stevens in a presentation at the MBA National Secondary Market Conference & Expo. “One of the big challenges in providing homeownership opportunities is simply having more inventory on the market, and that has its own regulatory issues. We have to give home builders the incentives to build more entry level homes.”
 
However, Stevens did not dump the burden solely on the home builders.
 
“All of us have to work together—Mortgage Bankers, Realtors, Home Builders—to create meaningful change,” Stevens added. “We don’t have to worry about people wanting to own a home—they do.”
 
Stevens stated that barring another recession, he was “going to remain bullish on the housing market and the economy.” But a change in the political landscape could bring new emphasis to different issues within the federal housing policy debate.
 
“Should the Democrats flip the House, you're going to see a bigger focus on affordable housing,” he predicted, noting that the next presidential election could bring even more change. “The next President could be a Democrat and we could see the deregulation pendulum swing back. We need stability; we need responsible lending; and I worry that we don't self-police ourselves enough.”

 
About the author
Published
May 22, 2018
Jobs Report Comes In Weak After Mortgage Rates Surge

Employers added just 29,000 jobs in September, sending Treasury yields lower and offering a potential counterweight to the recent rise in mortgage rates

Oct 02, 2026
Price Cuts Hit Four-Year High As Mortgage Rates Top 7%

More than one in five listings took a price cut in September, but pending sales still posted their sharpest annual decline since March 2025

Oct 01, 2026
Serious Mortgage Delinquencies Rise 19% After Five Months Of Improvement

ICE data shows 574,000 mortgages were at least 90 days past due in August, while early-stage delinquencies remained below year-ago levels

Sep 29, 2026
Smaller Down Payments Give Buyers More Room, But Rates Limit The Savings

The typical down payment fell 9% from a year ago, while shifting market conditions are giving originators different affordability conversations across the country

Sep 25, 2026
Mortgage Rates Break 7% Just As Builders Find A Way To Move Buyers

New-home sales rose 6.4% in August as builders cut prices, offered incentives, and sold more lower-priced homes. Now mortgage rates are moving against buyers again

Sep 25, 2026
Borrowers Want Digital Closings, But Some Originators Remain Hesitant

ServiceLink finds 45% of surveyed LOs cite borrower reluctance as a barrier, even though most recent buyers say digital options would influence their choice of mortgage provider

Sep 23, 2026


