The Federal Reserve maintained its benchmark interest rates Wednesday, taking into consideration the current robust state of the economy, labor market growth, and inflation rates that surpass the central bank's objective.
As anticipated by many, the Fed's decision-making committee unanimously decided to keep the primary federal funds rate stable within a 5.25%-5.5% range, unchanged since July. This marks the Federal Open Market Committee's second consecutive meeting where rates were held steady, following a series of 11 rate increases, four of which occurred in 2023.
The committee also improved its overall evaluation of the economic climate.
According to their post-meeting statement, there was a "strong pace" of economic activity during the third quarter. This shows an uplifted tone from their September announcement, which described the economy's growth as being at a "solid pace." The recent statement also highlighted that while the rate of employment growth has decelerated since earlier this year, it remains robust.
In addition, the Fed will continue reducing its holdings of Treasury securities and agency debt and agency mortgage-backed securities, as described in its previously announced plans.
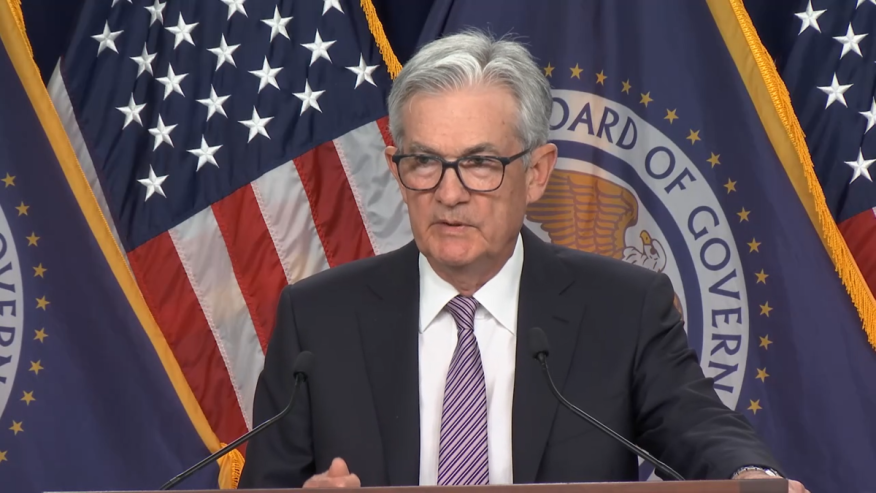
Fed Chairman Jerome Powell said “activity in the housing sector has flattened out.”
How bad will the economy have to get to take another rate hike off the table?
“We're getting reports from housing that the effects of this could be quite significant,” Powell said.
Mortgage Bankers Association Chief Economist Mike Fratantoni wants to see the Fed cut rates in the future.
“The housing and mortgage markets are at a standstill. Mortgage rates near 8%, coupled with a lack of inventory, are impairing affordability, even as new home construction picks up speed," Fratantoni said. "If the Fed does indeed move to cut rates next year and signals its intent to do so, mortgage rates should trend downward. Our forecast calls for this to happen, which would support a somewhat stronger spring housing market."
He said there are still risks for an economic slowdown in the first half of next year.
“It’s also worth noting that heavy debt issuance from the Treasury, a consequence of large and rising federal deficits, is also contributing to higher rates," Fratantoni said.
Marty Green, a principal in Polunsky Beitel Green, agreed there is risk.
“With treasury yields rising and mortgage rates at a 20+ year high, the Federal Reserve is like a blackjack player with two face cards—the only sensible play at this meeting was to hold pat," Green said. "Since the last meeting, the markets have basically done the Fed’s work for them, with the rise in rates for treasuries and mortgages equating to another interest rate increase. The lag effect of the Fed’s policy decision was on full display, with the economy continuing to absorb the full impact of the Fed’s decisions from earlier in the year, even with the Fed taking no additional action."
He predicted the Fed is done raising rates in this cycle.
"While the cycle has been inordinately painful to the mortgage industry, with another interest rate pause, we should be at least one step closer to some relief in 2024," Green added.