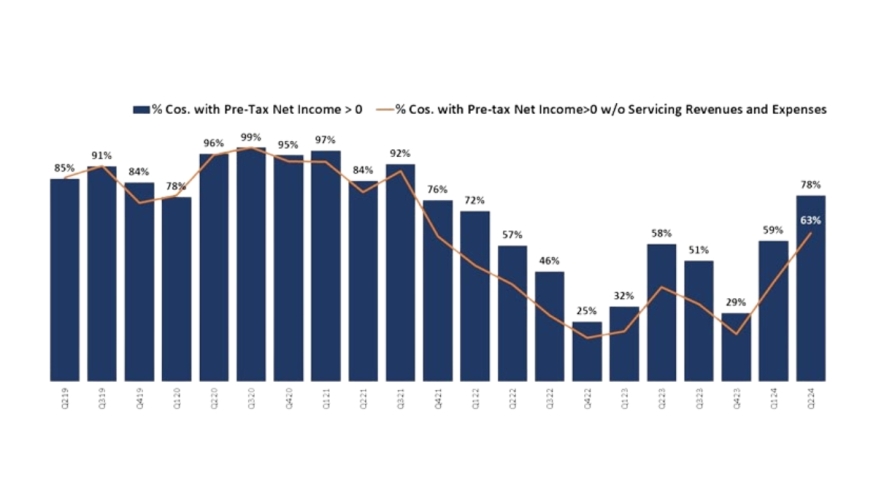
Independent mortgage banks (IMBs) and mortgage subsidiaries of chartered banks reported a pre-tax net profit of $693 on each loan they originated in the second quarter of 2024 — a major improvement that more than makes up for the reported loss of $645 per loan in the first quarter of 2024, according to the Mortgage Bankers Association’s (MBA) newly released Quarterly Mortgage Bankers Performance Report.
Overall, 78% of the firms in the report posted pre-tax net financial profits in the second quarter of 2024, up from 59% in the first quarter of 2024. The average pre-tax production profit was 17 basis points (bps) in the second quarter of 2024, compared to an average net production loss of 25 bps in the previous quarter and loss of 18 bps last year.
The average production volume was $492 million per company in the second quarter, up from $384 million per company in the first quarter. The loan volume by unit per company averaged 1,503 loans in the second quarter, up from 1,193 loans in the first quarter.
“Net production income was positive in the second quarter of 2024 — a welcome sign after eight consecutive quarters of net production losses,” said Marina Walsh, CMB, MBA’s vice president of industry analysis. “With a pickup in quarterly volume, productivity, and closings to applications pull-through, production costs dropped by about $1,800 per loan. These developments contributed to better net results, even as production revenues decreased from the previous quarter.”
Total production revenue (including fee income, net secondary marketing income, and warehouse spread) decreased to 347 bps in the second quarter, down from 371 bps in the first quarter. The production revenue per loan decreased to $11,499 per loan in the second quarter, down from $11,947 per loan in the first quarter.
However, total loan production expenses (including commissions, compensation, occupancy, equipment, and other production expenses and corporate allocations) decreased to 330 basis points in the second quarter of 2024 from 395 basis points in the first quarter of 2024.
The cost per loan decreased to $10,806 per loan in the second quarter, down from $12,593 per loan in the first quarter of 2024. From the second quarter of 2008 to last quarter, loan production expenses have averaged $7,524 per loan.
The purchase share of total originations by dollar volume was 86%. For the mortgage industry as a whole, MBA estimates the purchase share was at 78% in the second quarter of 2024. The average loan balance for first mortgages increased to $356,993 in the second quarter, up from $345,761 in the first quarter.
Servicing net financial income for the second quarter (without annualizing) was $69 per loan, down from $82 per loan in the first quarter. Servicing operating income (which excludes MSR amortization and gains/loss in the valuation or sale of servicing rights) was $88 per loan in the second quarter, down from $93 per loan in the first quarter.