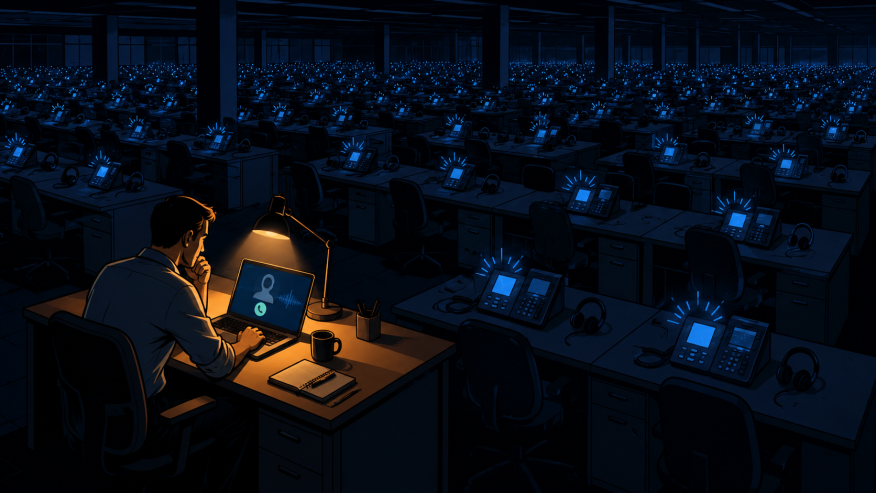
Hundreds of sales conversations happen daily right now that you'll never hear.
Not because it isn't recorded. Not because you don't care. But because there are only so many hours in a day, and reviewing sales calls manually — even two or three a week — is a time investment most mortgage sales managers can't sustain alongside everything else competing for their attention.
That's not a personal failure. It's a structural one. Industry data shows that sales managers review less than 1% of their team's calls.
On a team of ten loan officers making twenty calls a day, that means roughly 99% of every conversation — every objection handled well or poorly, every rate question fumbled, every moment a borrower almost said yes… goes completely unheard.
The result is millions in lost revenue that most mortgage sales leaders don't even realize is a problem because it’s just “standard”.
Managing the Scoreboard, Not the Game
Most mortgage sales managers run their teams on outcomes. Close rate. Pipeline volume. Funded loans. These numbers are important, but they're lagging indicators. They tell you what already happened, not why. By the time a performance problem shows up in the data, the sales mistakes that caused it have occurred hundreds of times over the past weeks.
The disconnect is significant. A manager might sit down with a rep for their weekly one-on-one, review their numbers, and walk away thinking the coaching session went well. But without visibility into actual call behavior, that conversation is built almost entirely on assumptions. You're coaching based on what you think is happening, not what is.
This is how bad habits compound. A rep develops a weak response to the rate objection. Nobody catches it for 30 days. In that time, they've lost deals that never showed up as a coaching opportunity, because nobody was listening.
The Manual Review Problem
The instinct most managers have is to listen to more calls. Pull a few recordings at the end of the week, spot-check a rep who's struggling, and sit in on a live call when you can. And while any coaching is better than none, the manual approach has a ceiling.
Selecting which calls to review introduces bias. Managers tend to pull calls for review from LOs who are constantly at the bottom of the leaderboard. Each rep has different sales struggles you don’t realize, and you never will because your sample size is too small. The 1% you hear is enough to diagnose the problem.
And even with the best intentions, sitting through full call recordings is slow. A 30-minute call takes 30 minutes to review. For a manager running a team of any real size, full call coverage simply isn't possible at scale.
The Old Fix Was Adding Headcount… And It's Expensive
For years, the only real solution was to hire more sales leaders. If one manager couldn't keep up with ten loan officers, the answer was to add another manager. And another. Stack enough multi-six-figure salaries, and you'd eventually have enough coverage to stay on top of the team.
The math was brutal. It compressed profit margins. A mortgage company growing from 20 to 40 loan officers wasn't just adding producers — it was adding layers of management to supervise them. Payroll bloated. Org charts got complicated. And even then, each manager was still only hearing a fraction of what their reps were actually saying on calls.
The teams that scaled that way built expensive infrastructure to solve a problem that was fundamentally about information, not headcount.
What Leading Teams Are Doing Differently
A growing number of mortgage sales leaders are solving this with conversation intelligence — AI tools that automatically analyze every call a team makes, surface what's working and what isn't, and give managers a structured way to coach without spending hours in a recording queue.
Objectionly has quietly become one of the mortgage industry's best-kept secrets. You just connect your call recording software, upload your sales scripts, and the platform reviews 100% of your team's calls with the same eye a seasoned manager would bring — flagging deal-killing moments, identifying objection patterns, and surfacing the conversations that actually need attention.
The practical impact goes beyond sales team visibility. Managers using Objectionly are doubling sales team size without adding sales leaders — going from supervising 10 loan officers each to managing 20 or more, without losing visibility into what's happening on calls. For a mortgage company with multiple sales managers on the payroll, that shift substantially cuts sales leadership overhead while improving the quality of coaching across the team.
In the same 3 hours, you could only review 6 calls; a manager using Objectionly can review 30 by seeing the top reason the deal didn’t close, clicking into that moment, and listening to the rep's response. It shows exactly which LOs are struggling with rate objections, which ones are losing borrowers in the first five minutes, and which calls are worth pulling up in a team meeting as a coaching example. All in one click. The decisions become specific, fast, and grounded in what's actually happening — not what you assume is.
The Gap Is Widening
The mortgage industry has always been competitive, but the teams pulling ahead right now share a common trait: they're making better decisions faster, and those decisions are grounded in what's actually happening on calls — not what managers assume is happening.
The 1% problem is solvable. The managers who solve it first will have a compounding coaching advantage — better-trained reps, more consistent objection handling, shorter ramp times for new hires, and a clearer picture of what's driving performance and what's killing it.
The ones who don't will keep managing the scoreboard and adding headcount, wondering why the numbers still aren't moving.