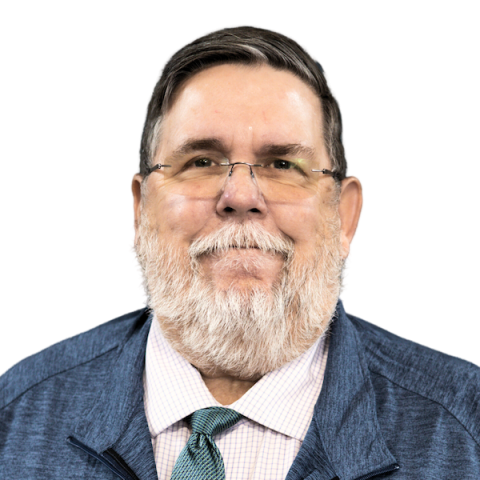
A Rhode Island mortgage broker has pleaded guilty for his decade-long Ponzi scheme that cost investors $6 million.
He will be sentenced in December and faces a maximum penalty of 20 years in prison for committing wire fraud, and five years in prison for committing tax evasion.
Court documents say between 2008 and 2018, Thomas Huling, 58, orchestrated a scheme that raised approximately $14 million, and caused losses of more than $6 million to his victims. Huling defrauded investors by promoting several investment projects. To enhance his credibility and build trust, he incorporated religion, the possibility of charitable good works, and association with well-known individuals into his sales pitches.
In an online sales pitch, Huling promoted himself as “one of the leading experts in international investments and global business.” He touted his 27 years of experience and “offered his unique brand of financial security, service excellence, and business ethics" to several companies.
Federal authorities also said Huling diverted investor money to fund a lavish lifestyle that included high-end vehicles; memberships and golf fees at multiple country clubs; gambling; clothing; restaurants; vacations and travel, as well as improvements to his residence. He created and used multiple shell companies; opened over 50 bank accounts; and engaged in convoluted financial transactions between various accounts before ultimately using the money personally.
According to court documents, at the same time that Huling was defrauding his investors, he was also committing tax evasion. Between 2009 and April 2018, Huling reported no taxable income, paid no income taxes, and for certain years filed false and fraudulent individual and corporate income tax returns.
To further hide his income, Huling used nominee bank accounts, and paid for personal expenses using cash and corporate debit cards. He also manipulated the books and records of his companies to record sham loans, titled personal assets in the name of shell companies, and made false statements to IRS special agents as to his income, expenses, and business activities.