On April 9th, my daughter got married. Being the freaky, nature loving, hippie that she is, the wedding was held on top of some mountain in the Shenandoah Valley. Don’t get me wrong, the background scenery to the ceremony was serene, but do you know how cold it has been in Virginia this April? Add to that the winds and it was like negative 30 degrees as I walked her down the aisle in my paper thin, rented tuxedo. I could feel myself catching a virus as I stood there.
Over the next week, I developed a fever, a nasty phlegmy cough and pink eye in BOTH eyes. Have you ever had pink eye in both eyes at the same time? Squinting through an intersection while you are driving is not the height of safety. I looked like something living at the top of a bell tower in Notre Dame.
Yet, life goes on, work goes on and I still had loans to do. Thank goodness I work from home. Can you imagine coming to the office all feverish and half blind? If I was the office manager, I would call security and have me shot on sight. Think zombie invasion.
This got me wondering. Just how bad would I have to be so that I was too disabled to still be a loan officer?
This is something I have contemplated ever since I once hired a loan officer with one arm. He was a slow typist, but pretty much, all in all, just as good as any other loan officer I ever hired. I was really impressed at the time. I thought to myself, “Hey, if I lost an arm, I could still be a loan officer, pretty cool.” In fact, even if I lost both arms, I could hire someone to type for me, no problem.
How about if I lost both arms and both legs? Sure, same solution, I could hire an assistant, since my main job is to solicit business and answer calls. Who needs to walk and see people? I could do everything over the Internet.
Come to think about it, assuming the correct compute interface, I could be a body-challenged brain in a jar and still be a darn good loan officer. I am sure there is a “Futurama” episode like that somewhere. Imagine Stephen Hawkins selling reverse mortgages? It could be done.
Okay, here is where I start to date myself (visualize your grandfather’s voice).
Back when I started in the mortgage industry as a loan officer, I visited real estate agents, bringing donuts to their office and handing out “rate sheets.” Is that a thing anymore? Real estate agents all work at home and I have not done a rate sheet in, literally, decades. This was all back when the Web was something spiders made in a haunted house and before Al Gore invented the Internet. A thumb drive was something you used to hitchhike. Cellphones were pagers and a computer was the size of your garage that only NASA could afford.
There is no way you could have been a loan officer back then with no arms and no legs.
Now, of course, we have social media advertising, interactive downloading personal Web sites, home offices and everything one needs to be a licensed mortgage loan officer … no anatomy needed, except your brain.
In fact, it makes you wonder if Quicken Loans actually has any human beings working there right now. I mean, given the strides in artificial intelligence, really, that disembodied voice you get could be Siri with a testosterone subroutine. How would you know? But more importantly, how would your customer know? Would your customer care? Just as long as the rate was 0.125 percent lower, I don’t think they would.
So that is the trend I see in the mortgage industry. Soon, smart software programs will replace even us loan officers.
But I have a plan. I will open a string of mortgage companies where all the loan officers are just brains in a jar. I would imagine I could pay them a lot less, since how much would a brain need to live on? I even have my corporate name picked out, “No Body Mortgage.”
Our motto: “We only have fixed-rate mortgages because … we have no ARMs.”
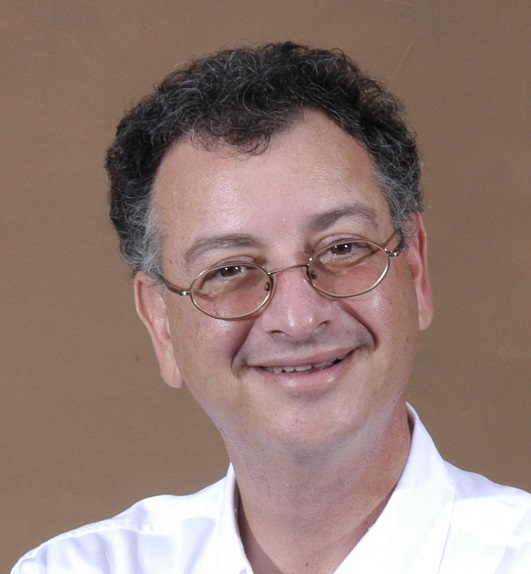
Eric Weinstein worked in banking, on the commercial real estate side until 1991, when he fell in love with residential lending. In 1995, he started a small mortgage company in his basement called Carteret Mortgage Corporation, which in 2003, grew to one of the largest mortgage broker companies in the United States. Eric is semi-retired, doing mortgages by referral only. He may be reached by phone at (703) 505-8692 or e-mail [email protected].
This article originally appeared in the May 2016 print edition of National Mortgage Professional Magazine.