The American workforce is undergoing an era of change. As the “gig economy” becomes more prominent, there is an ever-increasing number of independent contractors—or contingent workers—infiltrating the labor pool. According to the U.S. Department of Labor (DOL), contingent workers are those with temporary jobs and do not have implicit or explicit contract for employment, such as Uber drivers or those who are otherwise self-employed.
As stated in a recent Bloomberg article, the number of contingent workers has been increasing significantly in the last 20 years. And, beyond that, a recent Deloitte survey found that 42 percent of U.S. executives expect to use more contingent workers within the next three to five years. As these types of jobs are showing no sign of disappearing, the question remains: are W-2 tax forms really the most accurate proof of cash flow when applying for a mortgage?
It’s already difficult for homebuyers to qualify for QM loans due to the tight credit box in the mortgage market. These contingent workers get 1099s instead of W-2s, so when it comes time to purchase a home, many are left in a lurch as they cannot qualify for an Agency loan under the current requirements. Despite not being able to present a W-2, many of these workers are otherwise qualified for a mortgage but cannot get one since the mortgage industry has been slow to adapt to the gig economy.
Recently, the mortgage industry has relied on these tax forms for proof of income rather than taking a holistic view of a potential borrowers’ financial situation. If mortgage brokers want to remain competitive in the evolving economy and service those workers who are embracing this change, they will need to come up with programs that give homebuyers a means of verifying income outside of W-2s.
Many lenders in the non-agency space are starting to capitalize on this evolving trend. One solution is to allow potential homebuyers to use bank statements as qualifying income instead of W-2 income. In these types of programs, no tax returns are required, 24 months of bank statements must be shown, and those who qualify can have credit scores as low as 620, up to 85 percent LTV and rates starting in the five percent range. Angel Oak Mortgage Solutions offers these programs and has seen a sharp increase in volume as an increasing number of borrowers and real estate agents become aware of their existence.
If lenders want to stay relevant in the changing landscape of the labor market, they will need to evolve their programs to cater to this large percentage of the U.S. workforce.
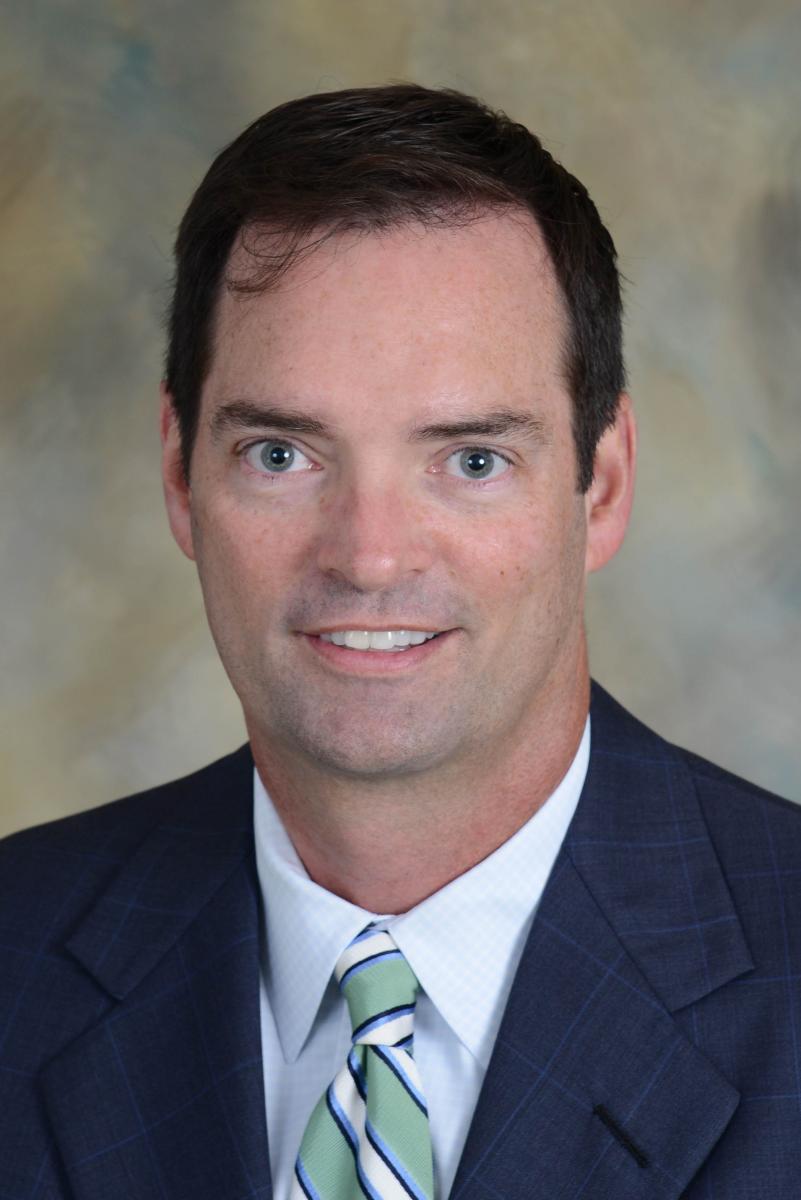
Tom Hutchens is senior vice president of sales and marketing at Angel Oak Mortgage Solutions, an Atlanta-based wholesale lender currently licensed in 32 states. Tom has been in the real estate lending business for nearly 20 years. He may be reached by phone at (855) 539-4910 or e-mail [email protected].
This article originally appeared in the August 2016 print edition of National Mortgage Professional Magazine.