I just completed my eight hours of online SAFE continuing education classes, and I actually learned something this time (thank you, Uncle Aaron!).
Did you know the average age of a mortgage originator is 54-years-old, the Mortgage Bankers Association's Barbara Hanson said during a panel discussion at the MBA’s Annual Convention called "Next Generation Loan Originators: Planning for the Industry's Future Workforce."
Now, compare that to 33-years-old, which is the average age for first-time homebuyers in the United States, according to a Zillow analysis (Zillow.MediaRoom.com/2015-08-17-Todays-First-Time-Homebuyers-Older-More-Often-Single).
Is it me, or does that seem like a huge generational gap between the average borrower and your typical loan officer?
I am 57-years-old and most of my buyers are 30-somethings buying their first home. I consider myself a fine cheese, like Camembert, and not just because I am a bit smelly and covered with a fungus. Kids today are more like a slice of American cheese, technologically processed and individually wrapped up in themselves.
So how do I bridge the gap? Easy, my kids are about that age. I treat my customers like I treat my own children. I try to offer them the best advice I can and explain in detail the reasoning behind what I tell them. And, like my kids, sometimes, they can be just so annoying!
If you have kids, you know what I am talking about. Why is it that when you call, their voicemail is always full and they only respond to a text? Why can’t they just pick up the phone? Everything is e-mail this and e-mail that. What ever happened to face-to-face personal interaction? Would it kill you to come over and visit your father once in a while?
Still, you love them and put up with it. Just like I do with my customers.
On the other hand, some of my youngster borrowers have dragged me kicking and screaming into the new millennium. Being old, it never occurred to me to advise my clients to send me their personal financial information in a secure fashion until a borrower brought up the subject. There are tons of cheap or free ways to do it like WinZip with an encryption key, Google Drive or Dropbox, to name just a few. If you don’t think e-mail security is important, just ask Hillary Clinton. More importantly, it lets your borrower know you care. The same I would do for any of my own offspring.
Here is another way to stay ahead of the technological curve if you are ancient like me. Ever since 1991 when I first became a loan officer, I have been going to my customer’s house to take the loan application and get disclosures signed. I felt people appreciated me coming to their home to discuss their purchase or refinance over a cup of coffee at the kitchen table. It is a great bonding moment for you and your client. I always received terrific feedback on my warm personal approach and tons of referrals. Then something changed. It was called the Internet.
Now I send all of my borrower documents through DocuSign, where they can electronically e-Sign them on their phone while they are running errands!
I have not noticed any drop in my referral business and conversely, the new generation tends to prefer it. Who has time for offline human interaction anymore? They tell me, “The house is a mess, the kids have the flu, but it’s been sure nice talking to you. Yes, sure nice talking to you. I don’t know when you can come over, but we’ll get together then, we’ll have a good time, then.” And then it occurs to me. The kids today grew up just like me. Who has the time?
Now here is the downside to all these mobile and paperless technologies. With all my video Webinar CE classes, online application practices, secure document transfers and e-Signature disclosing, I have not left the house in a month. Why bother to shower, shave or even change pajamas if you are not meeting people? The Big Cheese is getting smellier and smellier. Even my dog refuses to sleep in my home office now. Welcome to the Brave New World. It is easier, faster and more secure … but with just a whiff of foot odor.
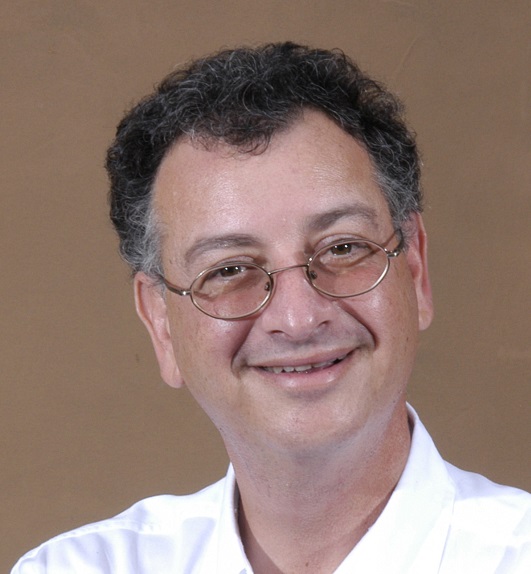 Eric Weinstein worked in banking, on the commercial real estate side until 1991, when he fell in love with residential lending. In 1995, he started a small mortgage company in his basement called Carteret Mortgage Corporation, which in 2003, grew to one of the largest mortgage broker companies in the United States. Eric is semi-retired, doing mortgages by referral only. He may be reached by phone at (703) 505-8692 or e-mail [email protected].
This article originally appeared in the October 2016 print edition of National Mortgage Professional Magazine.