After surging to a post-financial-crisis high last year, home-equity originations have fallen back in 2023, mostly due to the tightening of credit in the wake of recent bank failures, according to a new report.
The 32-page report, “Second Mortgage Market Insights Q2 2023,” was produced by Home Equity Lending News LLC (HELN) and Flueid, a technology company focused on real estate transactions. It provides a detailed look into the current state of the home equity market.
More than 10 million home equity lines of credit (HELOCs) and home equity loans (HELs) were outstanding at the end of last year, the report states.
“Back when the financial crisis was still unfolding in 2009, the number of HELOCs originated plunged by nearly half from 2008 to fewer than 1 million units,” it states. “Volume remained low in the following years but finally edged higher in 2014, rising to more than 1 million units – where it lingered until at least 2017.”
The COVID-19 pandemic and subsequent financial crisis put a dent in new lending, as volume tumbled to less than 900,000 units in 2020, the report states.
New business rebounded to nearly 1 million units in 2021, and then gained steam in 2022, the report states.
“Last year represented the strongest year for home-equity lending since the financial crisis, with volume estimated at 2.7 million HELs and HELOCs for roughly $450 billion,” it states.
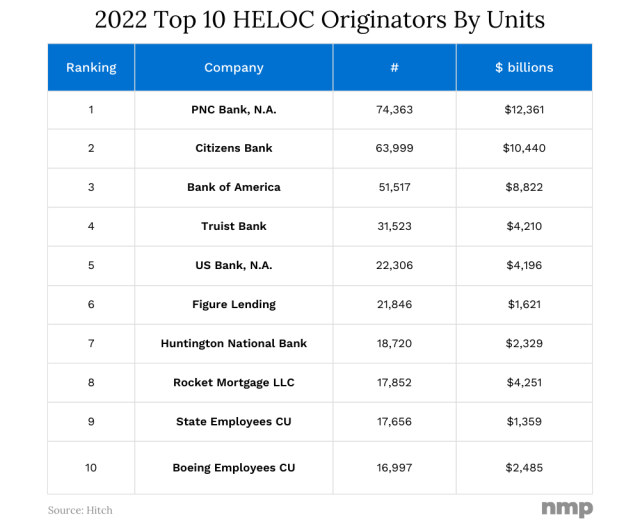
Most HELOCs are owned by financial institutions, with a small share financed through the secondary market, the report states. A majority of the overall home-equity activity is HELOCs, and among originators, PNC was the biggest HELOC lender in 2022, originating 74,363 loans totaling nearly $12.4 billion. All of the top-five HELOC lenders were banks.
Following the strong 2022 results, 2023 has seen a drop in demand.
According to the report, “Just as it appeared that home-equity business was trending higher, aggressive rate hikes by the nation’s central bank threw capital markets into disarray. Although it didn’t start out that way, 2022 ended with capital markets volatility, and that volatility has carried into 2023 — with the recent bank failures only adding to the market stress. Still, some home-equity transactions are being securitized.”
The recent bank failures involved Silicon Valley Bank and Signature Bank in March, and First Republic Bank earlier this month.
“After second-mortgage production surged last year to a post-crisis high, the recent failure of three regional banks disrupted the capital markets for home-equity products and drove down interest rates – making first mortgage cash-out refinances more viable for some homeowners,” HELN CEO Sam Garcia stated. “So we’ve seen a revision to expectations for second-mortgage originations.”
In addition to loan production, the report discusses advancements in home-equity technology, along with the impact from the growing implementation of artificial intelligence. It also discusses the quality of automated verifications and valuations, and their ability to help lenders predict performance. An analysis of search results for home-equity phrases that identifies which lenders are winning the SEO race is also included.