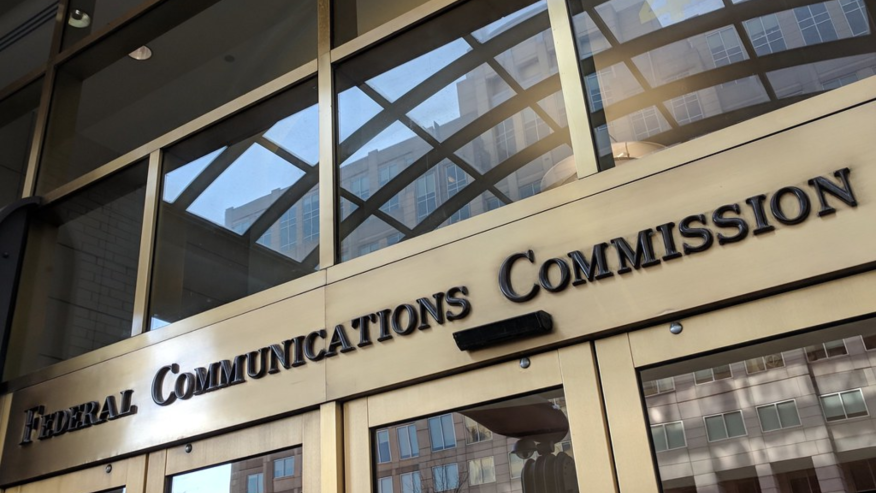
As of January 27, 2025, the Federal Communications Commission (FCC) will implement new rules to close the so-called lead generator loophole for companies using auto dialers and pre-recorded messages, which could completely overhaul the business model among lead providers and some mortgage lenders.
In an attempt to mitigate the ‘bombardment’ of robocalls and robotexts consumers receive from telemarketers, the FCC plans to adopt the one-to-one consent rule requiring texters and callers to obtain a consumer’s prior express written consent from a single seller at a time on the comparison shopping websites, such as LendGo and LendingTree.
Multiple sellers can be presented on a webpage, but each must obtain express consent separately and maintain a logical and topical relationship to the website.
In 2016, the National Mortgage Servicing Association created a petition in 2016 saying “that auto dial calls are necessary for mortgage servicers to effectively communicate with their customers,” though the FCC rejected them, saying they can use other means.
The new regulations also include provisions for blocking robo-texting numbers identified as "red flagged," formalizes do-not-call regulations for texting, and promotes an opt-in strategy for sending email-to-text messages.
The FCC sought commentary until late January 2024 to conduct further economic analysis on the impact of this proposal on small businesses. Among the small businesses that provided their feedback was Lendgo, a distributor of mortgage leads, which said the new rules will lead to at least a 25% reduction in consumer journey completions. In turn, the company anticipates cost increases of more than 25% for the businesses that rely on comparison sites for lead acquisition.
In other words, Lendgo believes not every lender will survive the new rules, and any that do will pass down the higher costs to the consumer.
“Closing the “lead generator” loophole and asking consumers for one-on-one consent will greatly affect the online user journey and user experience of legitimate comparison websites,” said a spokesperson for Lendgo. “In addition, it will adversely affect the performance metrics of these user journeys which will likely wipe out several small and mid-tier businesses.”
Other potential problems that small businesses mention in response to the FCC’s new order include:
- Increase operating expenses
- Benefit large telemarketing firms and large brands/businesses
- Unfairly punish small businesses, cause massive layoffs and even shut down businesses
- Consumers will lose options
- Consumers will lose the expertise of skilled agents in specific verticals
- Consumers will pay the higher price
For any originators that would like to provide their feedback on the FCC's new rules, please contact [email protected].