The Federal Reserve on Wednesday announced another 25-basis-point increase in its benchmark rate as it continues to battle stubborn inflation, but what was more important to observers is what the Fed didn’t say.
In announcing its 10th increase in the federal funds rate in 14 months, the Federal Open Market Committee (FOMC) omitted from its statement previous language that signaled additional rate hikes could be on the table at future meetings. Wednesday’s statement did not include the phrase “some additional policy firming may be appropriate,” which had been included in the statement after its previous meeting in March.
Wednesday's announcement came at the end of the FOMC’s two-day meeting, and had been highly anticipated by economists and Wall Street analysts. According to Seeking Alpha, market participants had bet the FOMC would announce another rate hike, with an 88% probability of a 25 bps increase, according to the CME's FedWatch Tool.
That prediction was spot on. The 0.25% increase raised the federal funds rate target range to between 5% and 5.25%, the first time the range has been this high since the FOMC raised the rate to 5.25% in June 2006. It remained there until Sept. 2007, when the rate was cut to 4.75%.
In its statement Wednesday, the committee said economic activity expanded at a modest pace in the first quarter, unemployment remains low, and inflation remains elevated.
It also said the U.S. banking system “is sound and resilient,” while also acknowledging that tighter credit conditions “for households and businesses are likely to weigh on economic activity, hiring, and inflation,” though it added that the “extent of these effects remains uncertain."
What's Next?
With that mixed economic news as a backdrop, the FOMC said it raised the fed funds rate in its ongoing effort to bring inflation down to its goal of a 2% annual rate.
“In determining the extent to which additional policy firming may be appropriate to return inflation to 2% over time, the committee will take into account the cumulative tightening of monetary policy, the lags with which monetary policy affects economic activity and inflation, and economic and financial developments,” the FOMC said.
The FOMC said it will also continue to reduce its holdings of Treasury securities, agency debt, and agency mortgage-backed securities.
Whether the FOMC will continue to raise its benchmark rate or pause after its next meeting, scheduled for June 13-14, remains unclear.
“In assessing the appropriate stance of monetary policy, the committee will continue to monitor the implications of incoming information for the economic outlook,” the FOMC said in its statement. “The committee would be prepared to adjust the stance of monetary policy as appropriate if risks emerge that could impede the attainment of the committee’s goals.”
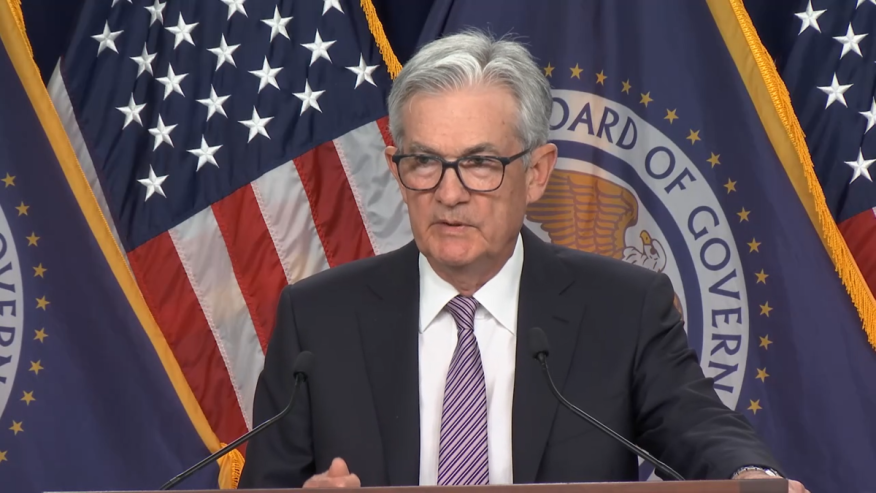
In a news conference Wednesday afternoon, Fed Chairman Jerome Powell also was noncommittal about what actions the FOMC will take at its next meeting.
“Our future policy actions will depend on how future events unfold,” he said. “We are prepared to do more if greater monetary tightening is warranted.”
To Pause, Or Cut
Others have already begun speculating.
“Neither a fragile banking sector nor a slowing job market prevented the Federal Reserve from increasing its short-term rate target again…, in line with market expectations.” said Mike Fratantoni, senior vice president and chief economist for the Mortgage Bankers Association. “However, with this increase, we expect this is the peak rate for this cycle, and potential homebuyers and their mortgage lenders may be breathing a sigh of relief.”
Fratantoni said the MBA continues to expect mortgage rates will drift downward “over the course of the next year as the economy slows, as we move closer to the Fed lowering rates beginning in 2024, and as the financial market volatility finally begins to settle down.’
Marty Green, principal with the law firm Polunsky Beitel Green, was less certain about a future pause or rate cut.
“The Fed clearly wants more time to assess whether inflation is truly retreating to the Fed’s target level, while the market is hopeful that the Fed will more quickly recognize the need for a rate reduction to respond to, or prevent, a more severe recession,” Green said. ‘Unfortunately, it is unlikely that there is a ‘Goldilocks rate’ that will address both concerns, so the Fed is letting markets know it will choose to stay the course to win the inflation fight before becoming overly concerned about a possible recession.”
Green added that there was a positive takeaway from the Fed’s increase.
“The good news is the mortgage market had already priced in the quarter-point increase,” he said. “The hope is that a pause in future increases, along with less interest rate volatility, will cause mortgage rates to return to a more historically consistent spread in relation to 10-year Treasuries. That spread has typically been 1.5%-2%, but today, that spread is over a point higher. So, it’s possible that mortgage rates might see improvement later this year even without the Fed actually lowering the discount rate.”