The 30-year mortgage was designed with that amortization schedule to provide a hedge against volatility and inflation, but because borrowers are not being underwritten for long-term affordability, and homes are not being underwritten to emerging, asset-level climate risks, ballooning escrows are functioning like piggyback, adjustable-rate mortgages, which is bad math for consumers.
“Those big spikes in insurance change the contract that homeowners sign when they get a mortgage,” says Jeremy Porter, director of Quantitative Methods in the Social Sciences at City University of New York, who leads the Climate Implications Research team at First Street Foundation, a climate change modeling and analytics firm. “They would’ve worked that into the household economics of owning a home.”
Insurance executives, economists, actuaries, and scientists have testified to the Senate Budget Committee that as underinsurability rises, property values in affected markets will decline, insurance unavailability will cause affected properties to become unmortgageable, and the “wide-scale decline in coastal and wildland-urban interface community property values would present a systemic risk to the U.S. economy, similar to what occurred in the 2007-2008 mortgage meltdown,” according to publicly available documents.
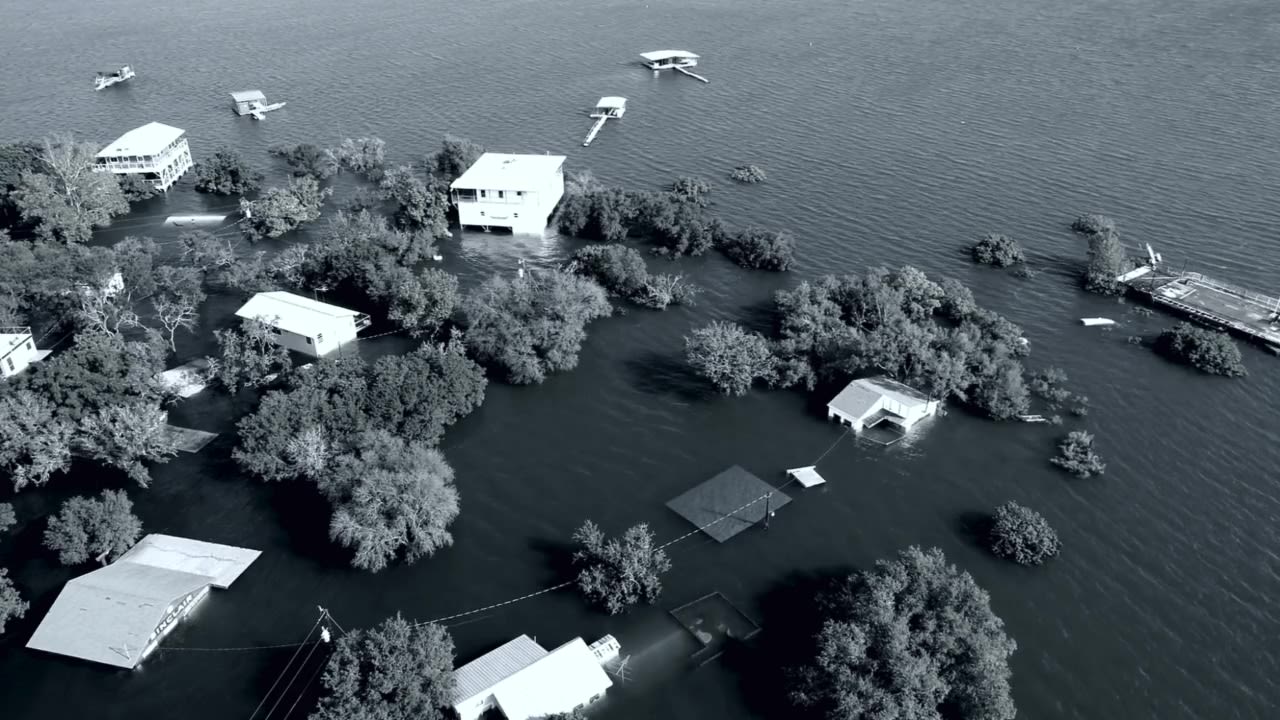
“If you open up the hood and you find out, in fact, there is flood exposure, your property value goes down,” the White House advisor explains. At play, in the face of mounting threats from flood to fire to tornadoes, from wind to drought to hail, is collateral — homeowners and homes — not underwritten to the risks they actually present.
As insurers and investors re-risk every U.S. home on the basis of its insurability, adjusting portfolios to prepare for a climate-adjusted future, government housing agencies are racing to remediate widespread, self-inflicted insurance shortfalls on their books. At this very moment, re-risked homes nationwide securing trillions of dollars of mortgage securities warrant lower valuations.
As the cost of homeownership surges in some places and home values fall in others, those buying homes today, or who bought since 2020, are not being underwritten for either scenario.









 Built with Shorthand