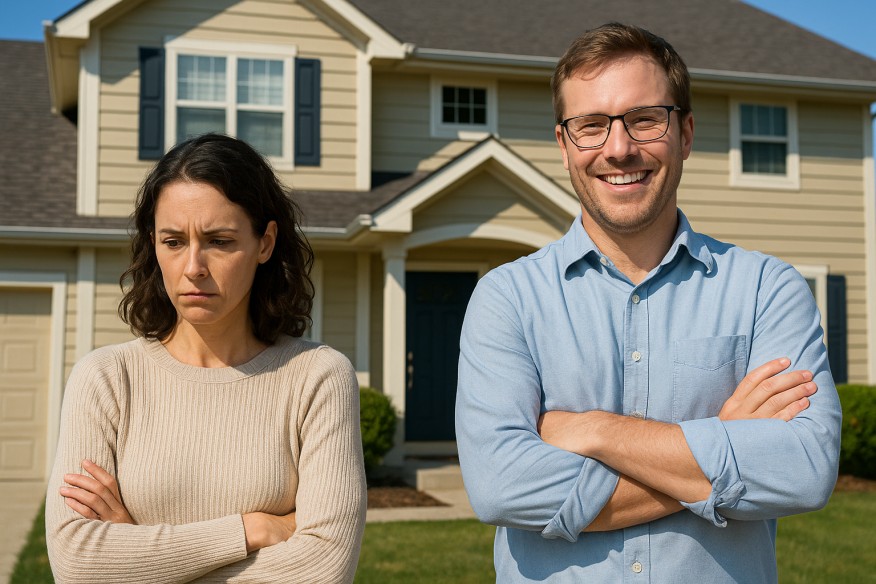
Hitching your wagon to the wrong person can be expensive, not just in terms of mental fatigue and possibly divorce. It can also be costly when a poorly matched pair wants to buy a house.
A new study from the Mortgage Research Network finds it could cost an extra $437 a month when your spouse has a low-credit score – even if you score in superb. Over the typical 12-year ownership tenure, that works out to more than $63,000, the Columbia, Md., media firm calculates.
For the study, a low credit score was defined as less than 640, whereas a better score was 760 or higher. Mix those together and the financially mismatched couple will end up paying higher mortgage rates, larger private mortgage insurance premiums, and more money for homeowners insurance.
And the ripple effect doesn’t stop there. A low score also drives up costs for auto insurance, auto loans, and, of course, credit cards.
Consequently, it may be better for a betrothed couple to exchange credit scores before they exchange their vows. It may not be the most romantic thing to do, but research shows that those with higher and more similar scores are more likely to stay together post-nuptials.
Indeed, a 2015 Federal Reserve study found that couples with a 66-point credit score gap had a 24% higher risk of breakup during the first four years of their relationship and a 12% higher risk during years five and six.
At the same time, higher average credit scores also predicted relationship longevity. For every 93-point increase in a couple's average score, the likelihood of separation dropped by 37% during the first six years.
“These results lead us to hypothesize that credit scores, in addition to measuring an individual’s creditworthiness regarding the repayment of debt obligations, reveal information about an important relationship skill,” say the study’s authors. “We argue that one such skill could be an individual’s general trustworthiness and commitment to non-debt obligations.”
The good news is that buying a house usually comes long after the wedding, so the lower-credit score spouse has time to improve his or her score. The other choice is to call it quits, if not the marriage altogether, then at least the notion of buying a house.
Nationally, the research network found that a house payment increases an average of 14.4% when adding a low-credit co-applicant. But costs spike even higher in some cities: 30.2% in Memphis, Tenn., 29.9% in Detroit, and 24.1% in Oklahoma City.
In dollar terms, the largest increases in payments when adding a spouse with low credit were in San Jose, Calif. ($1,049), San Francisco ($926), San Diego ($751), and Los Angeles ($671).
Leaving the lower credit score spouse off the application isn’t always possible because many couples need the incomes of both partners to qualify, says Tim Lucas, a licensed originator who leads mortgageresearch.com, a division of Three Creeks Media. Lenders use the lower score, not the average, when underwriting a loan, he points out.
Moreover, in nine community property states, a spouse’s debts and sometimes credit score must be factored into underwriting FHA, VA, and USDA loans, even if they’re not on the application.