Most states posted annual overall mortgage delinquency increases in March, according to CoreLogic's latest monthly Loan Performance Insights Report, with Louisiana (+0.7%), Mississippi (+0.4%), and Alabama (+0.4%) seeing the largest annual increases.
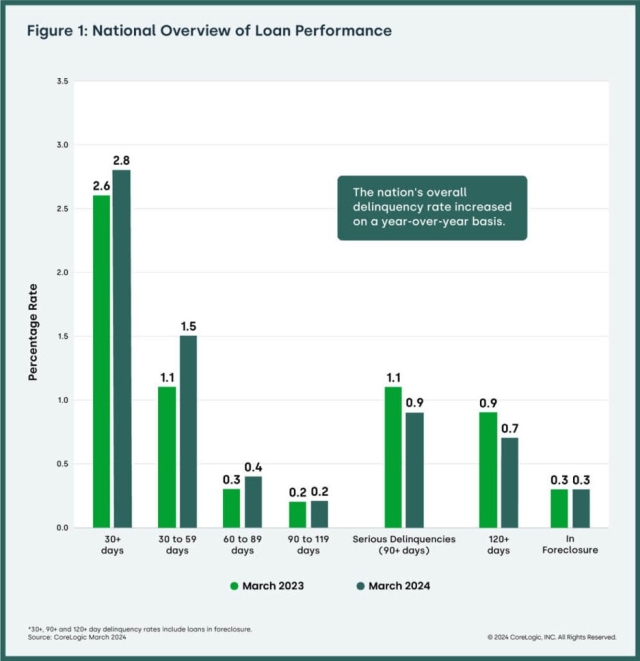
The nation’s overall mortgage delinquency rate held at 2.8% in March for the third straight month, but moved up slightly (+0.2%) from the same time last year.
“The U.S. delinquency rate increased from a year earlier in March, driven by an uptick in early-stage delinquencies,” said Molly Boesel, principal economist for CoreLogic. “Further, the early-stage delinquency rate remained flat from February to March this year, while it typically falls between those months, as many borrowers receive income tax refunds in March. While monthly changes in the early-stage delinquency rate can be volatile, this break from the seasonal trend comes at a time when household budgets are strained by still-high inflation.”
Meanwhile, more than 80% of tracked U.S. metro areas saw serious delinquency rates rise on an annual basis anywhere from 1.6% to 0.1%.
Despite the small annual delinquency gains, the national foreclosure rate stayed at 0.3% for the 25th straight month, a sign that mortgage performance remains strong, according to the report. A U.S. unemployment rate that remained below 4% in April should help most borrowers pay their bills on time in the coming months, the report also says.
For all stages of delinquencies, the March 2024 report breaks down as follows:
- Early-Stage Delinquencies (30 to 59 days past due): 1.5%, up from 1.1% in March 2023.
- Adverse Delinquency (60 to 89 days past due): 0.4%, up from 0.3% in March 2023.
- Serious Delinquency (90 days or more past due, including loans in foreclosure): 0.9%, down from 1.1% in March 2023 and from a high of 4.3% in August 2020.
- Foreclosure Inventory Rate (the share of mortgages in some stage of the foreclosure process): 0.3%, unchanged from March 2023.
- Transition Rate (the share of mortgages that transitioned from current to 30 days past due): 0.7%, up from 0.5% in March 2023.