Study Uses Court Record Data to Predict Policy Claims and Losses – NMP Skip to main content

Study Uses Court Record Data to Predict Policy Claims and Losses

Feb 09, 2016
Is there a correlation between court record violation activity and homeowners insurance loss ratio performance

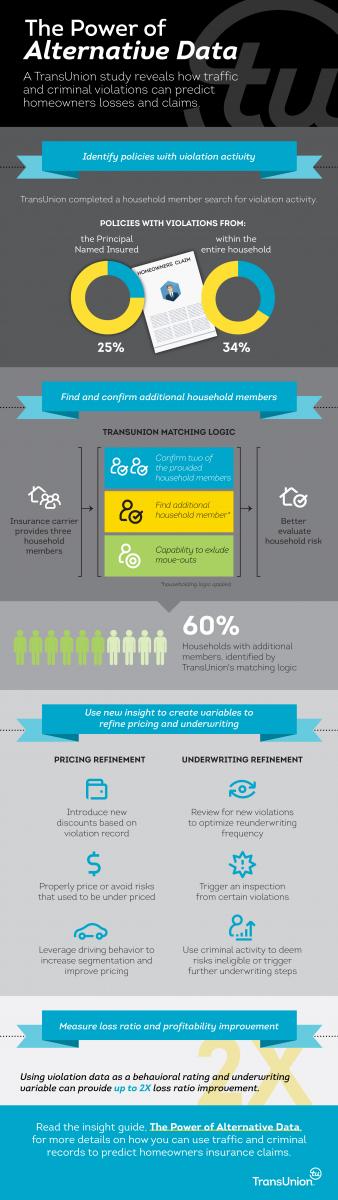
Is there a correlation between court record violation activity and homeowners insurance loss ratio performance? According to a new study by Chicago-based TransUnion, the answer is yes.

“The homeowners insurance industry is expanding its use of underwriting variables and rating techniques and is more closely evaluating those that are traditionally used in the personal automobile insurance underwriting process,” said Mark McElroy, executive vice president of TransUnion’s insurance business unit. “The findings clearly show that the use of alternative data assets such as court record violations can help property insurance carriers better assess a homeowner’s risk. As insurance carriers incorporate driving records to properly price riskier policies, consumers with clean driving records can benefit.”

By using definition of defined “court record” data to encompass both criminal and traffic violations, TransUnion determined that one-quarter of policies had at least one criminal or traffic violation based on the primary named insured. But when the court record data of the additional members of a household were added into the configuration, the violation hit rate increased from 25 percent to 34 percent.

“The current macro-economic trends and the consumer market show there is a greater demand for using broader data attributes to deliver better predictive analytics,” said Geoff Hakel, senior vice president of TransUnion’s insurance business unit. “Incorporating court record violation data into the pricing and underwriting process provides property insurance carriers greater pricing sophistication and profitability.”

About the author
Published
Feb 09, 2016
When AI Takes Action: New Federal Framework Raises Questions

New federal banking guidance examines the risks of autonomous AI, from borrower communications to servicing transactions, with a focus on human oversight and accountability

States Tighten Mortgage Rules For Home Equity Investments

Massachusetts, Maine, and Illinois are expanding oversight of home equity financing

West Capital LO Challenges Contractor Status, Required Fees

A former originator alleges unpaid overtime, recurring tech charges, and company restrictions that he says undermine his independent-contractor status

CFPB Closes 40% Of Investigations, Keeps Mortgage Enforcement In Focus

The federal watchdog closed thousands of supervisory and investigative matters as it narrowed oversight

Midterms Loom With Mortgage Policy Changes Already In Motion

As voters head to the polls Tuesday, Washington is weighing changes to refinancing costs, loan pricing, and lending regulations

UAD 3.6 Deadline Is Monday. Are Brokers Ready?

Wholesale lenders have adopted different rules for appraisal transfers, loan product changes, and reporting formats, adding complications for brokers and appraisers ahead of the Nov. 2 mandate