CoreLogic has released its August 2016 National Foreclosure Report which shows the foreclosure inventory declined by 29.6 percent and completed foreclosures declined by 42.4 percent compared with August 2015. The number of completed foreclosures nationwide decreased year over year from 64,000 in August 2015 to 37,000 in August 2016, representing a decrease of 69 percent from the peak of 118,221 in September 2010.
The foreclosure inventory represents the number of homes at some stage of the foreclosure process and completed foreclosures reflect the total number of homes lost to foreclosure. Since the financial crisis began in September 2008, there have been approximately 6.4 million completed foreclosures nationally, and since homeownership rates peaked in the second quarter of 2004, there have been approximately 8.5 million homes lost to foreclosure.
“Foreclosure inventory fell by 30 percent from the previous year, the largest year-over-year decline since January 2015,” said Dr. Frank Nothaft, chief economist for CoreLogic. “The large decline in the distressed inventory has been one of the drivers of steady home price growth which helps Americans increase their home equity to support increased spending or cushion future economic risk.”
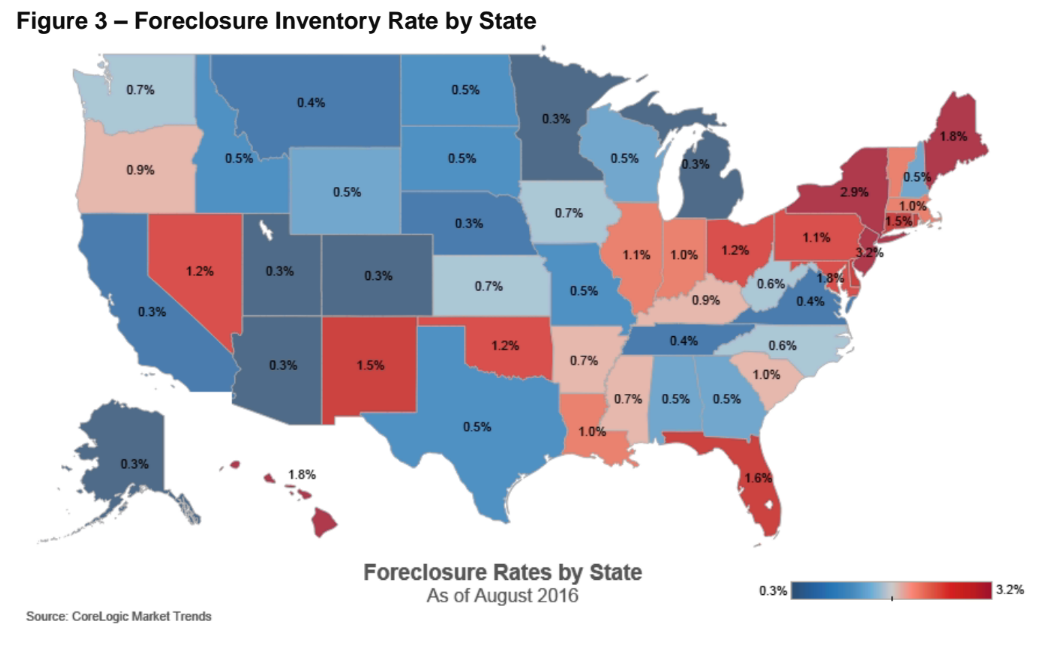
As of August 2016, the national foreclosure inventory included approximately 351,000, or 0.9 percent, of all homes with a mortgage compared with 499,000 homes, or 1.3 percent, in August 2015. The August 2016 foreclosure inventory rate is the lowest it’s been since July 2007.
CoreLogic also reports that the number of mortgages in serious delinquency (defined as 90 days or more past due including loans in foreclosure or REO) declined by 20.6 percent from August 2015 to August 2016, with 1.1 million mortgages, or 2.8 percent, the lowest level since September 2007. The decline was geographically broad with decreases in serious delinquency in 48 states and the District of Columbia.
“Foreclosure rates and serious delinquency continued to trend down in August as real estate markets across many parts of the U.S. exhibit strong demand growth and rising prices,” said Anand Nallathambi, president and CEO of CoreLogic. “With the foreclosure inventory now under 1 percent nationally, the need to boost single family housing stocks through new construction will become more acute in the coming months and years.”