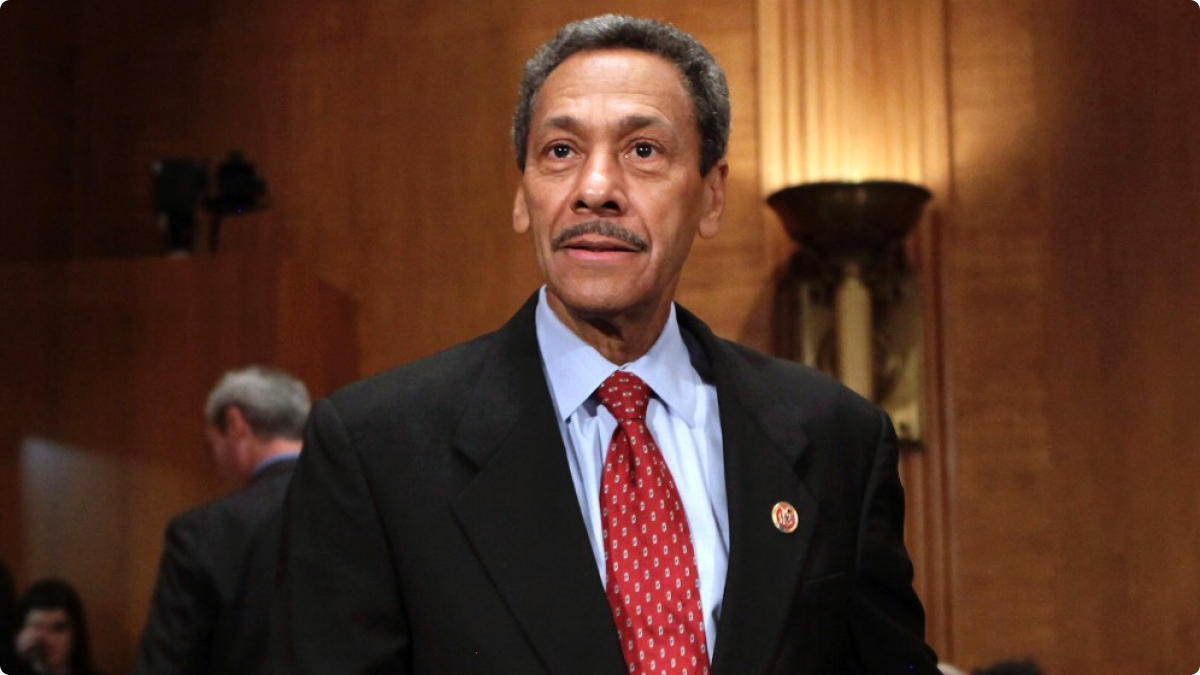
 The regulator for the government-sponsored enterprises (GSEs) is openly admitting that the sections of the housing market are poorly performing due to a myriad of socioeconomic challenges. In a speech delivered today before the Mortgage Bankers Association’s Annual Conference, Federal Housing Finance Agency Director Mel Watt admitted that the post-2008 recovery has been “disappointingly uneven,” with many areas facing continued uncertainty or worse.
“Some areas of the country have not regained pre-crisis home values, and some are not projected to do so for some time to come,” he said. “These areas continue to have a significant number of borrowers who are seriously delinquent on their mortgage or who are current in making their payments but are still underwater. These problems often exist in urban and low-income neighborhoods that were hardest hit by the crisis and where abandoned and vacant homes adversely impact property values and fuel a continuing cycle of disinvestment. Often these are neighborhoods where people of color predominate. Ironically, these hardest hit neighborhoods often stand in close proximity to other, higher-income neighborhoods that are thriving. And, of course, many rural areas, where manufactured housing continues to be an important source of housing, also continue to face unique and difficult housing challenges.”
Watt noted that the disparity between fast-rising home prices and relatively stagnant wage gains have exacerbated the situation, although he remained optimistic that this imbalance could change.
“New data suggest that real incomes may finally be showing signs of growth, although real wages still remain below peak levels,” he continued. “Last month, the Census Bureau released data showing that median wages, adjusted for inflation, grew over five percent in 2015. This growth was shared across demographic groups, with the notable exception that workers living in non-metropolitan areas experienced flat incomes, signaling a challenge for many families living in rural areas. It's too soon to reach any conclusions about income trends, but sustained wage growth would obviously help many people regain their footing in the economy and in the housing market.”
Watt also pointed to credit score problems that many Americans experienced during the recession as contributing to problems in accessing homeownership, although he noted that “borrowers will begin to see these negative events fall off their credit reports in the next several years, and that has the potential to improve their credit scores.”
Still, Watt forecast positive developments in the near future, with the potential for Millennials to make their long-overdue major thrust into homeownership numbers as well as increased homeownership rates among African-Americans and Hispanics. But, nonetheless, Watt remained cognizant of the struggles taking place elsewhere in the housing world.
“Millions of families lost their homes to foreclosure and, in the process, moved from being homeowners to renters,” he said. “Over the last 10 years, the number of renters increased by nine million, and renters now represent 36 percent of all households … By the end of 2015, over 20 million households were paying more than 30 percent of their income toward rent. Of these, over 10 million paid more than 50 percent of their income on rent. High rent payments not only impact the finances of households in the present, but may also limit future housing options by making it harder to save for a down payment. There are some signs that rent increases may be lessening in certain metropolitan areas, but rental affordability is certain to remain an ongoing challenge for many families.”