The head of the nation’s leading mortgage industry trade group warned that the status quo regarding the government-sponsored enterprises (GSEs) cannot be accommodated any longer.
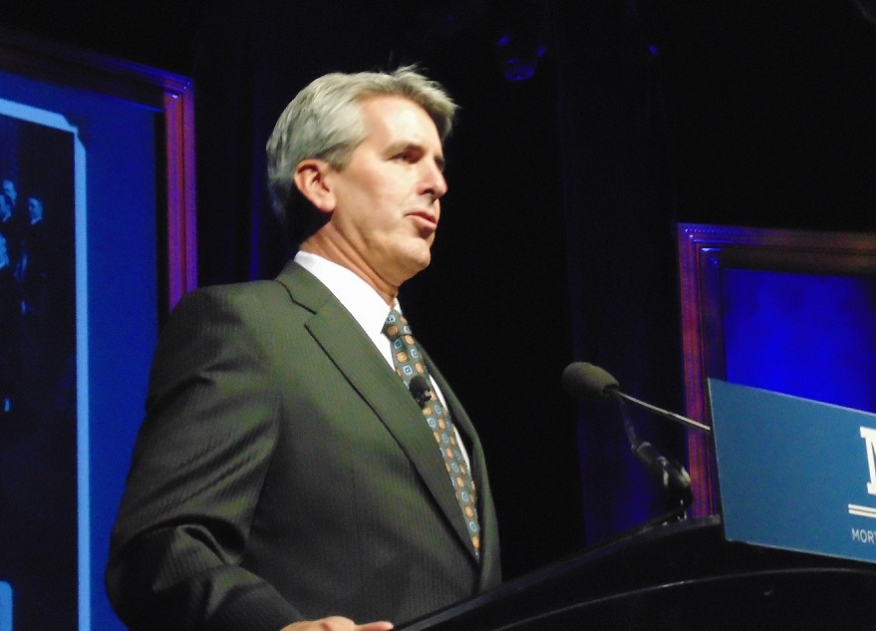
David H. Stevens, president and CEO of the
Mortgage Bankers Association, addressed the issue of GSE reform in a speech before his organization’s National Secondary Market Conference and Expo in New York, where he warned that returning Fannie Mae and Freddie Mac to their pre-conservatorship configurations is not a feasible option.
“Simply put, recap and release is more like rewind and repeat,” he said. “It would return the GSEs to their previous state without safeguards to ensure the positive progress during conservatorship remains and without any guarantee the agencies will operate in a manner that protects the taxpayer going forward. This is dangerous ground that destabilizes the system and does nothing to protect our economy, our homes or taxpayers from another bailout.”
Stevens pointedly added that winding the GSE clock back to before September 2008 is not in the best interests of the nation.
“Rather, recap and release is a “solution” designed to protect the personal pocketbooks of a select few,” Stevens continued. “This misguided dialog threatens to recreate the very crisis it purports to avoid and destabilize the level playing field for all eligible lenders to compete in this market equally. The financial crisis plainly exposed the structural conflicts, misaligned incentives, and other weaknesses associated with the GSE business model and regulatory framework. The result was a catastrophic failure of the secondary mortgage market that required more than $187 billion in direct taxpayer support and a continuing federal commitment of more than $240 billion.”
Stevens noted that the Trump Administration and the GOP-controlled congress were pursuing a legislative solution to GSE reform while the Federal Housing Finance Agency had “made significant progress mitigating some of the key flaws in the GSEs’ operations that distorted the market in the run-up to the crisis, including bringing parity and transparency to their pricing models, moving toward a single security and developing the common securitization platform.” But he warned that efforts to pollute the debate with class warfare politics would serve no credible purpose.
“This is not a big versus small lender issue, or Wall Street versus Main Street, as some would have you believe,” he stated. “It’s not lenders versus consumers, as if only one side can win. It’s about ensuring a housing system that first and foremost gives qualified borrowers access to affordable, long-term fixed rate mortgages without allowing the riskier aspects of the pre-conservatorship GSE model to re-emerge.” He also noted this proposal addressed the gnawing problem of affordable housing, which has become more acute in recent years.
“We believe that any new system must expand access for affordable mortgage credit; preserve and develop affordable rental housing; and improve liquidity for underserved segments of the mortgage market,” Stevens said. “America’s housing needs must be served along the full continuum—from the most subsidized government assistance programs, to the fully-private, jumbo mortgage market. Our proposal looks to ensure the new guarantors have incentives that will support, not distort, the market for affordable mortgage credit.”