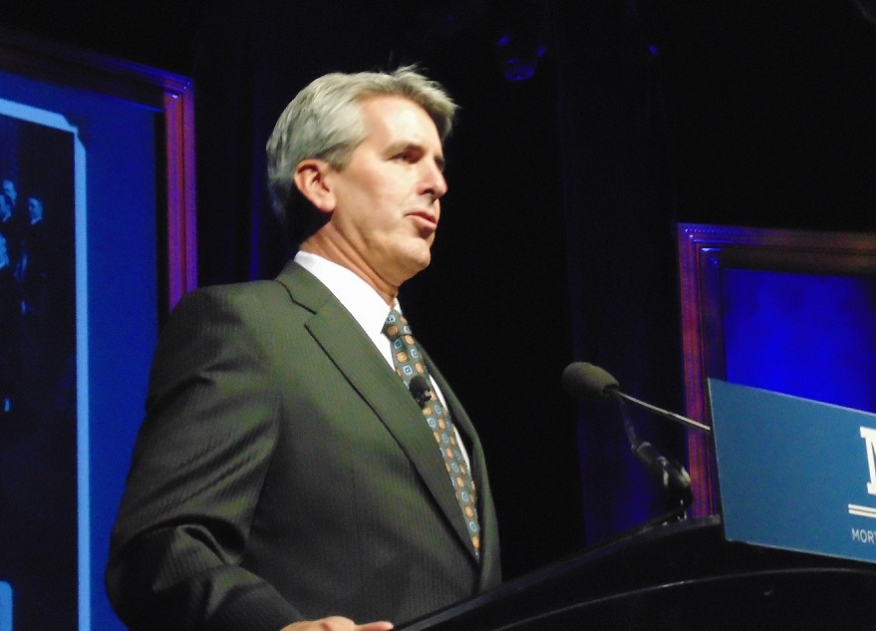
David H. Stevens mixed a personal health update with a professional diagnosis on the state of the mortgage industry in his opening remarks at the Mortgage Bankers Association’s (MBA) Annual Convention in Denver.
On the personal front, the trade group’s President and Chief Executive Officer updated the industry on his
fight against prostate cancer, reporting that he was in full remission after an extensive regimen or surgery, chemotherapy and daily radiation sessions running for eight weeks.
“This may not last forever,” Stevens said. “But I feel great and I’m grateful.”
Overcoming the unpredictable also impacted Stevens’ professional focus, particularly his dealings with the Trump Administration. Stevens stated that the MBA has established a vibrant relationship with the Administration and continues to be a prominent though leader in the nation’s capital.
“When it comes to policy, the policymakers in Washington come to us,” he said. “They rely on our data, our research, our thoughtfulness, and our perspective.”
Stevens also pointed out that more unpredictable challenges face the industry, including the conclusion of
Mel Watt’s tenure as Director of the Federal Housing Finance Agency.
“The fact is that Director Watt’s term ends at the end of next year and who is selected after him could risk the sense of security that far too many in our industry and in real estate live in today,” Stevens said. “What happens if the President nominates a new director who thinks the government role in mortgage finance is too large and wants to scale it back? The answer is that it could affect everything from G-Fees to loan limits. Credit policy could change which would impact the QM patch and confidence in the rule as it works today. Even the level playing field in pricing and credit terms could change as there is nothing locked in. We are risking our respective business models under a change in director unless we can permanently lock these reforms in. And that can only be done with legislation.”
Stevens repeated the MBA’s goal of enacting a solution to end the federal conservatorship of Fannie Mae and Freddie Mac, while urging the MBA membership to use its collective voice to “ensure a pro-growth tax code keeping incentives that encourages families and businesses to invest in real estate.”
Stevens also highlighted the association’s commitment to diversity, noting the Diversity and Inclusion Conference scheduled for December in Washington and the
mPower initiative to detail the role of women in the mortgage profession. He also called on mortgage professionals to become more active participants in shaping the industry’s future.
“This is not a sideline sport,” Stevens said. “And as we always say, the larger the group, the louder the voice: Power comes with numbers. From best practices to critical market data to education and important conferences. To all of our committees, task forces, and policy teams that help create the framework for influencing and advocating.”