April 2024 (Q1) Senior Loan Officer Opinion Survey on Bank Lending Practices shows weakening demand for consumer loans.
The Federal Reserve Senior Loan Officer Opinion Survey on Bank Lending Practices (SLOOS) recently published its findings for the first quarter of 2024, addressing lending standards, terms, and demand for bank loans among businesses and households.
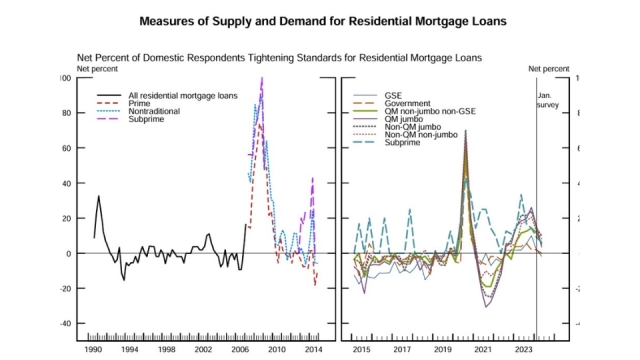
For households, a modest net share of banks reported that lending standards tightened across some categories of loans, including Non-QM jumbo, Non-QM non-jumbo, subprime, and qualified mortgage (QM) non-jumbo, non-GSE-eligible mortgage loans. Lending standards remained about the same for GSE-eligible mortgages, government mortgages, and QM jumbo mortgages.
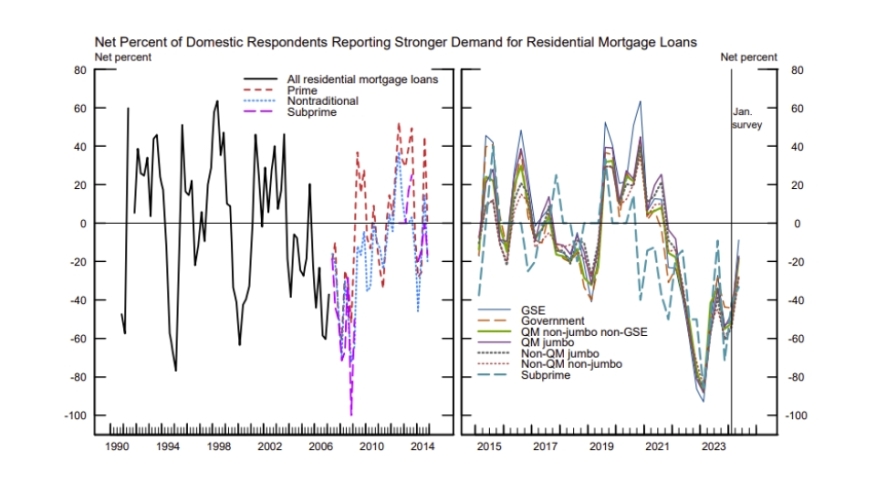
Large banks reported net easing of standards, while other banks reported net tightening of standards for most residential real estate (RRE) loans. Additionally, a moderate net share of banks reported weaker demand for HELOCs.
Federal Reserve Board, April 2024 Senior Loan Officer Opinion Survey on Bank Lending Practices shows bank lending standards tightening.
Over the first quarter, banks reported tightening lending standards and most terms, on net, for all consumer loan categories, including credit card loans.
Significant net shares of banks reported tightening lending standards for credit card loans, but only moderate and modest net shares of banks reported tightening standards for other consumer loans and auto loans, respectively.
Get the NMP Daily
Essential stories, every weekday.
Additionally, a significant net share of banks reported increasing the minimum credit score requirements for credit card loans, while only a moderate net share of banks reported doing the same for other consumer loans. Plus, a modest or moderate net share of banks reported decreasing the extent to which loans are granted to customers not meeting credit scoring thresholds and increasing spreads of interest rates over the cost of funds for all consumer loan categories.
Other queried terms and conditions were left unchanged on those loans, except for the credit limits for credit card loans.
As for demand, a moderate net share of banks reported weaker demand for credit card loans and other consumer loans in the first quarter. Also, a significant net share of banks reported weaker demand for auto loans.
September's $53 increase ended three months of payment relief, with affordability deteriorating in 39 states
Three months of declining mortgage payments came to an end in September, as higher rates pushed the median monthly payment on purchase applications up $53 despite a slight decline in loan amounts.The median principal-and-interest payment rose to $2,215 from $2,162 in August,...
The $2 million credit line combines 30-year fixed-rate repayment with reusable borrowing capacity
Fintech lender Aven is taking its home-equity lending model into the purchase mortgage market, offering qualified buyers up to $2 million in financing and promising closings in as little as seven days.The California-based company announced Friday that its new Home Purchase L...
The mortgage giants recorded a combined $1.94 billion in third-quarter provisions, with higher projected rates extending credit exposure and signs of stress emerging among newer loans
ICE and Auction.com data reveal a growing concentration of recent mortgage vintages in foreclosure activity, with government-backed borrowers facing additional equity pressures