Substantial home equity has boosted consumer financial health, but risks remain in non-mortgage consumer lending
“Persistently resilient” describes U.S. consumers according to DoubleLine Portfolio Manager Andrew Hsu and ABS Trader Michael Fine in their newly published research, "The State of the U.S. Consumer Through the Lens of Asset-Backed Securities.” That consumer resilience is backed, they say, by a lot of home equity.
By leveraging asset-backed security (ABS) loan data with macroeconomic data, the asset management firm DoubleLine formed a comprehensive view of the U.S. consumer that offers perspective on their economic/financial health. The authors of the study, Hsu and Fine, conclude that consumer resilience has been fueled by the strength of the residential mortgage market, a healthy labor market, and excess savings accumulated during the pandemic.
A gradual slowdown in prepayment speeds indicates that consumers are still largely able to meet their obligations despite higher borrowing costs, the study found. Plus, overall delinquencies have remained low in the past two years, especially mortgage delinquencies, which are below the long-term historical average.
Low rates of mortgage default and substantial home equity have provided a buffer against financial stress for homeowners. Also, because of consumers’ resilience, the authors of the study believe it suggests the possibility of pulling off an economic soft landing.
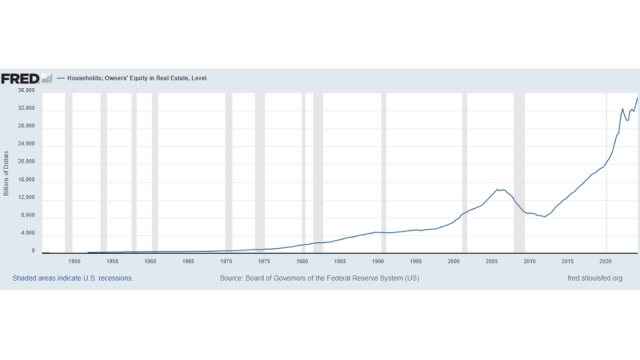
Owners' equity in real estate from January 1952 to January 2024. As property values increase, so does homeowners' financial security.
However, the authors note that "potential risks to the consumer persist, including the depletion of these savings, wage stagnation, a recent rise in unemployment and ongoing high consumer prices, notwithstanding cooling in the year-over-year rate of inflation."
Get the NMP Daily
Essential stories, every weekday.
Credit card delinquencies, for example, have been climbing. The study highlights how the rise in delinquencies in other sectors of consumer lending suggest growing financial stress among consumers, especially those with weaker credit profiles. Although defaults have remained low, the authors predict that default levels could rise if economic conditions worsen.
Still, an apparent improvement in underwriting and lending practices as observed from the average FICO score among vintage ABS loan pools also provide a positive sign of consumer financial health, per DoubleLine's report. ABS deals in 2021 have an average FICO score of 680, whereas 2024 deals have an average of 724, rendering a decreased likelihood of default.
The authors report that DoubleLine continues "to find attractive relative value in select areas of the ABS consumer market. While prepayments, defaults and loss severities require close monitoring, they all remain within reasonable historical average moving bands."
The dispute over publicly marketed homes comes amid a Compass–Rocket alliance linking home search, buyer inquiries, and financing offers
Six multiple listing services have sued Compass over its demands that they stop penalizing agents who publicly market homes without sharing the listings through the MLS, escalating a dispute over who gets access to for-sale inventory and when.The lawsuit, filed Oct. 21 in th...
Veterans United’s survey finds less willingness to hold out for lower rates, but little change in purchase timelines
Prospective homebuyers are growing more pessimistic about interest rates, and less inclined to wait for relief.In Veterans United Home Loans’ latest survey, 57% expect interest rates to rise over the next year, up from 45% a year earlier. Yet the share who would consider wai...
September’s decline leaves originators competing for fewer purchases, while rising borrowing costs and limited new listings keep affordability under pressure
Realtor.com finds 66 of 99 metros favor buyers or are moving that way, while rising financing costs have cut borrowing capacity 7.2% since late August for a fixed monthly payment