Federal Agencies Announce Threshold for Smaller Loan Exemption – NMP Skip to main content

Federal Agencies Announce Threshold for Smaller Loan Exemption

Oct 14, 2022
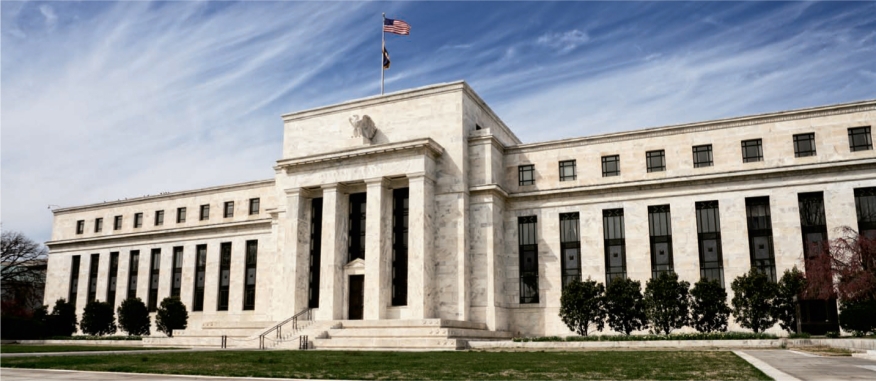
Federal Reserve Bank
Staff Writer

The 2023 threshold will involve exempting loans from special appraisal requirements for higher-priced mortgage loans.

KEY TAKEAWAYS
  • The threshold amount will be effective January 1, 2023, and is based on the annual percentage increase in the CPI-W as of June 1.
  • The rules implementing these requirements contain an exemption for loans of $25,000 or less.

The Consumer Financial Protection Bureau, the Federal Reserve Board, and the Office of the Comptroller of the Currency today announced that the 2023 threshold for exempting loans from special appraisal requirements for higher-priced mortgage loans will increase from $28,500 to $31,000.

Each agency released statements about the new change. According to each press release, the threshold amount will be effective January 1, 2023, and is based on the annual percentage increase in the Consumer Price Index for Urban Wage Earners and Clerical Workers (CPI-W) as of June 1, 2022.

The Dodd–Frank Wall Street Reform and Consumer Protection Act added special appraisal requirements for higher-priced mortgage loans, including that creditors must obtain a written appraisal based on a physical visit to the interior of the home before making a higher-priced mortgage loan. 

The rules implementing these requirements contain an exemption for loans of $25,000 or less, adjusted annually to reflect CPI-W increases.

An addendum to the Fed’s release states that if there is no annual percentage increase in the CPI-W, the agencies will not adjust this exemption threshold from the prior year. 

Additionally, in years following a year where the exemption threshold was not adjusted due to a decrease in the CPI-W, the threshold would be calculated by applying the annual percentage increase in the CPI-W to the dollar amount that would have ensued, after rounding, if the decreases and any subsequent increases in the CPI-W had been taken into account.

About the author
Staff Writer
Sarah Wolak is a staff writer at NMP.
Published
Oct 14, 2022
What The 2026 Election Means For Mortgage Professionals

CHLA’s Scott Olson examines how the next Congress could reshape housing tax breaks, lending costs, and access to homeownership — and where bipartisan deals remain possible

Oct 22, 2026
Servicer Takes New York Payment-Fee Fight To Federal Court

Onity Group says the state hasn’t clearly defined how fees for optional expedited payments must relate to the cost of providing the service

January’s Condo Reserve Increase Puts Project Budgets In Focus

Fannie Mae and Freddie Mac’s higher allocation requirement gives LOs reason to review association finances now, while California’s new funding duties begin in 2032

California Probes Lenders Over Delayed Wildfire Insurance Payouts

State regulators are examining access to rebuilding funds, while CalHFA offers financing tools for eligible disaster survivors

One In Three Americans Blame Lenders For Housing Crisis Ahead Of Midterms

Voters want lower taxes, insurance costs, and mortgage rates, but 63% doubt the election will improve housing

Oct 20, 2026


