With the pandemic pretty much in the rearview mirror and inflation still a big issue, it was inevitable that the rate of mortgage delinquencies would increase.
That happened in the fourth quarter of 2022 according to the latest National Delinquency Survey, released Thursday by the Mortgage Bankers Association (MBA).
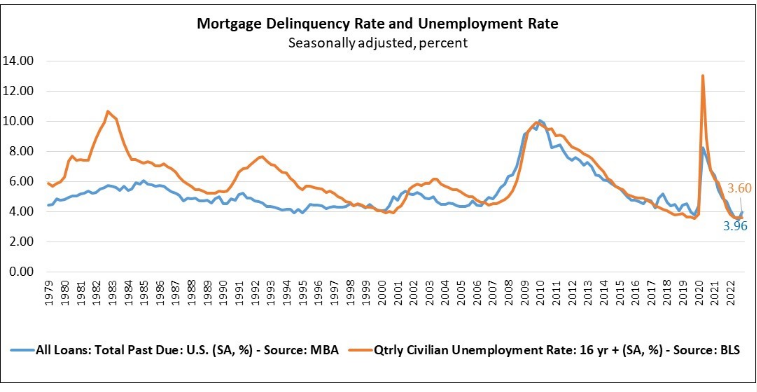
The delinquency rate for mortgage loans on one-to-four-unit residential properties increased to a seasonally adjusted rate of 3.96% of all loans outstanding at the end of the fourth quarter of 2022, the MBA said.
The rate was up 51 basis points from the third quarter, but was still down 69 basis points from the fourth quarter of 2021. The percentage of loans on which foreclosure actions were started in the fourth quarter fell by 1 basis point to 0.14%.
“As expected, the overall national mortgage delinquency rate increased in the fourth quarter of 2022 from its previous quarterly survey low,” said Marina Walsh, CMB, MBA’s vice president of industry analysis. “The weaker economy and ongoing inflationary pressures contributed to the uptick in delinquencies. The delinquency rate — while still low — increased from the previous quarter across all loan types and across all stages of delinquency.”
According to Walsh, for the past 15 years mortgage delinquencies have tracked very closely with employment conditions. Despite recent indications that the job market remains strong, including the unemployment rate slipping to 3.4% in January, the MBA still forecasts for slower hiring and rising unemployment in 2023, with the rate rising to 5.2% by the end of the year. That will likely mean further increases in mortgage delinquencies, the MBA said.
“Notwithstanding the fourth-quarter increase in mortgage delinquencies, the foreclosure starts rate of 0.14% was well below the historical quarterly average of 0.4%,” Walsh said. “Many distressed homeowners have loss-mitigation options available to them and have accumulated home equity, which can ease financial hardship and avert foreclosure actions.”
The Key Highlights
Here are some of the key highlights of the MBA’s National Delinquency Survey. Note: For the purposes of the survey, MBA asks servicers to report loans in forbearance as delinquent if the payment was not made based on the original terms of the mortgage.
- Compared to last quarter, the seasonally adjusted mortgage delinquency rate increased for all loans outstanding. By stage, the 30-day delinquency rate increased 26 basis points to 1.92%, the 60-day delinquency rate increased 13 basis points to 0.66%, and the 90-day delinquency bucket increased 11 basis points to 1.38%.
- By loan type, the total delinquency rate for conventional loans increased 26 basis points to 2.78% over the previous quarter. The FHA delinquency rate increased 209 basis points to 10.61%, and the VA delinquency rate increased by 45 basis points to 4.16%.
- On a year-over-year basis, total mortgage delinquencies decreased for all loans outstanding. The delinquency rate decreased by 80 basis points for conventional loans, decreased 15 basis points for FHA loans, and decreased 108 basis points for VA loans from the previous year.
- The delinquency rate includes loans that are at least one payment past due, but does not include loans in the process of foreclosure. The percentage of loans in the foreclosure process at the end of the fourth quarter was 0.57%, up 1 basis point from the third quarter and 15 basis points higher than a year earlier.
- The five states with the largest quarterly increases in their overall delinquency rate were: Louisiana (77 basis points), Florida (74 basis points), Indiana (62 basis points), West Virginia (55 basis points), and Mississippi (55 basis points).