As the forecasts for 2026 begin to roll in, Realtor.com is calling for a “steadier” housing market in the coming year, with mortgage rates averaging 6.3% and home prices rising just “a modest” 2.2%.
The official listing site of the National Association of Realtors (NAR), the nation’s largest trade organization, Realtor.com predicts a “more balanced market” in 2026, one where price growth steadies and rate relief offers “breathing room.”
“Housing affordability improves as incomes outpace inflation, pushing the typical payment share of income below 30% for the first time since 2022,” economists at the site predict.
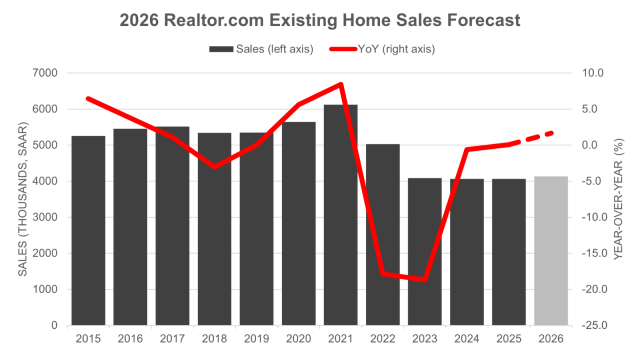
Existing-home sales are expected to edge up 1.7% in 2026 after a nearly flat 2025. Even with this modest rebound, though, sales will remain well below normal as high prices and financing costs continue to hold back demand.
If the forecast holds true, 2024's existing-home sales of 4.06 million will be a 29-year low. In 1995, existing-home sales reached only 3.849 million.
The mortgage rate “lock-in effect” will continue to weigh heavily on the market next year, Realtor.com also projects. Recent data, the site reports, shows that four out of every five owners with a mortgage have a rate below 6%.
“As a result,” the report says, “turnover will be limited with moves likely to be spurred by life necessities such as job or family changes.”
House prices, meanwhile, will rise 2.2% in 2026, the site predicts. That's on top of an even more modest 2% increase this year. But Realtor.com expects inflation to outpace these gains, meaning real house prices, those adjusted for inflation, will “decline slightly” for a second consecutive year.
“This dynamic — nominal prices rising but real prices slipping — gradually improves affordability, even if it doesn’t feel like a dramatic shift to most buyers or sellers,” the forecast says.
“Put simply, the sticker price of homes keeps going up, but the overall price level and incomes rise faster meaning that it takes a smaller chunk of each paycheck to buy a home. The slow normalization process helps buyer incomes catch up.”
With the 30-year fixed-rate mortgage (FRM) averaging 6.3% next year, the site’s economists note, the typical monthly payment to buy the median-priced home can be expected to slip 1.3% year-over-year as home price growth moderates and mortgage rates drop on average.
“This will mark the first decline in monthly payments on average across the year since 2020,” the economists say.
Moreover, they add, rising incomes give buyers more purchasing power, helping to shrink the share of a paycheck that has to be put toward the mortgage.
The monthly payment to buy the typical home is expected to dip to 29.3% of median income in ‘26, the first year under the 30% affordability threshold since 2022 when mortgage rates shot higher.
“The gains may be modest, but mark an important shift toward better conditions for home buyers,” the report says.
At the same time, the site predicts that inventories will grow more slowly next year, but that growth will still outpace sales. It projects an 8.9% increase in active listings in ‘26, marking a third consecutive year of gains. Still, by year’s end, inventory levels are expected to remain roughly 12% below pre-2020 averages.
Overall, the report confides, while the housing market won’t be ‘easy’ for buyers, more will be able to successfully navigate the market’s challenges. Sellers, on the other hand, face another year of rising home inventory and sluggish sales as the market continues to move into a more balanced one.