It’s a good time to “read the tea leaves” in the mortgage industry because the next five years are likely to bring big changes – and the pace of change is only accelerating, disrupted by forces like artificial intelligence (AI) and automation.
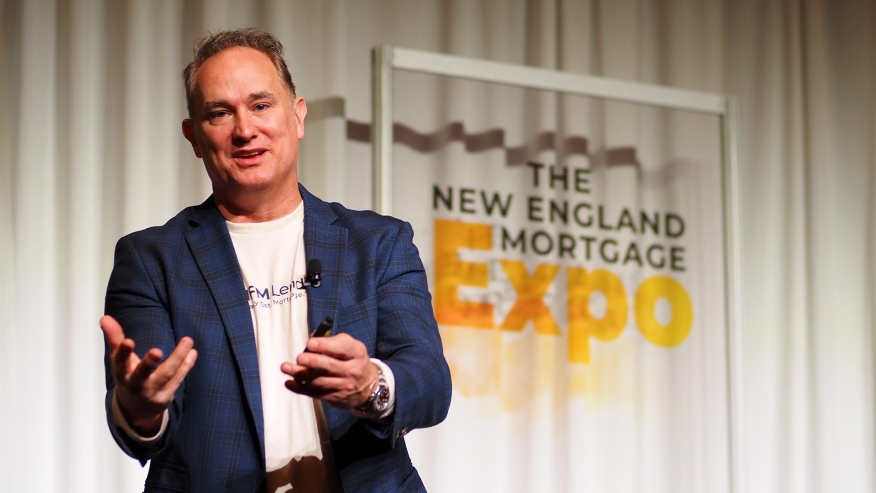
So noted Rick Roque, corporate vice president of new growth at NFM Lending and founder of Menlo Consulting, speaking this week at the New England Mortgage Expo in Connecticut.
“With some regulatory changes, we're going to be able to qualify for a mortgage as fast as you can qualify for student loans. It'll happen in minutes,” Roque said. On that note, he added, loans will have the potential to close in fewer than seven days.
He explained that AI is already getting very, very good in terms of what it can do with borrowers, and it will be able to free up a good deal of loan officers’ time. Roque gave the example of a chatbot phoning borrowers and having a conversation about whether a borrower is ready for a loan – without the borrower ever having any clue he or she was talking to a bot.
What that means for mortgage loan originators (MLOs) careening toward 2030, is that certain functions of handling a loan will likely be handled by AI and automation, reducing the need, say, for loan officer assistants and processor assistants.
“Back in the day ... for every seven loans or 10 loans or 40 loans, you hire a processor, hire another underwriter, all the old metrics,” Roque said. In the coming years, “we’re going to hold our back office to probably about 10, 15, 20% of what it is today, but we're expecting to be able to have that support because of AI, a growth of almost doubling our production.”
The changes to come sparked Roque’s comment about “reading the tea leaves” in the mortgage industry. “You have to understand where the market is going to pivot for your own career, regardless of where you are,” he said, highlighting the distinction between the mortgage market's evolution and mortgage operations' evolution.
Though 2025 has begun with marked inventory improvements, “there’s a lot of work to be done yet.” Total mortgage origination volume for 2025 may be less than had been projected, Roque said.
“Literally, in December, we were talking about $2.2, $2.3, $2.4 trillion” in total origination volume, he said. “I don't think there's a chance we'll get above $2.2 trillion; I really don't."
He added there's a chance this year's total volume will be between that of 2023 and 2024 – "and let's just hope it's not 2023.” Roque also said he expects consolidation to accelerate this year, and for loan originators to “get used to selling” at rates around 7% or even higher.
For loan officers today, he noted, it’s becoming more essential to use social media to help boost their influence and business.
“We're in an era of ‘image and likeness’ deals with loan officers, right?” Roque said. “What I think you guys should be doing is leveraging the experience and the knowledge you've accumulated over a career in appropriate online content."