Ask a room of mortgage professionals whether AI matters to their business, and nearly every hand goes up. Ask where they should start, and the room gets quiet.
That silence makes sense. A five-person brokerage, a regional lender with a small marketing team and a top-20 lender with its own data science group are not standing at the same starting line. They have different systems, different levels of expertise, different risk tolerances and very different definitions of a win. Yet much of the AI conversation in our industry assumes a single path: buy the platform, flip the switch, wait for the transformation.
At Cotality, we see it differently. There is no single prescribed path to AI value. There is the path that fits where you are today and where you want to go next.
Every Path Starts With Data You Can Trust
Our industry has become very good at speed. Credit pulls, verifications, AVMs and eSignatures can each happen in seconds. Yet originating a mortgage still takes weeks because our industry has built islands of instant in a sea of disconnected, manual processes.
AI can connect those islands, but only if the intelligence behind it is right. A model trained with incomplete or stale property data doesn't improve outcomes; it just produces wrong answers faster. Cotality research finds homebuyers are reluctant to trust in AI tools, and nearly half of the buyers surveyed would pay extra for a human to verify AI outputs.
That is why the foundation matters more than the model. Cotality's AI-ready data draws on more than 22,000 verified property and public record sources, identifies U.S. properties with 99.25% accuracy and is checked against more than 130 federal and state regulations every day. Just as important, it carries the semantic context that AI models need to interpret property intelligence correctly.
Four Ways In: Data, Solution, Persona, Application
With the foundation in place, the real question becomes how your team consumes that intelligence. We think about it in four ways, and most clients use more than one.
Data. For organizations with their own analysts, models or data science teams, the most valuable thing we can deliver is the raw material: AI-ready bulk data delivered into the cloud environments they already use, including Snowflake, Databricks and Google Cloud. Your team builds. We make sure what it builds on is accurate, current and defensible.
Solution. Many lenders and brokers don't want a data pipeline; they want a problem solved. Here, we package our intelligence in purpose-built solutions. AutomatIQ Borrower, for example, brings verification and qualification into one automated workflow. Lenders using it report handling more than 40% additional volume without adding staff, eliminating nearly eight hours of manual work per file and cutting cycle times by four days.
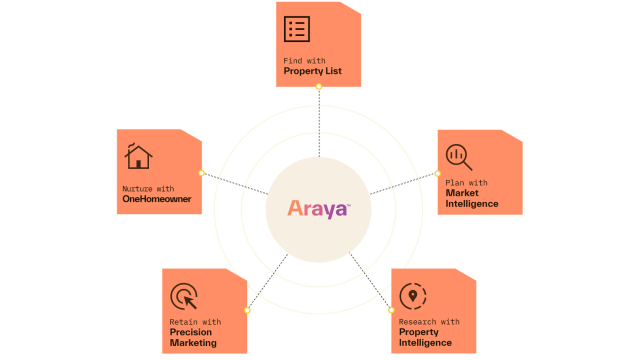
Persona. The same intelligence means different things to a loan officer, a marketing lead, a processor and a branch manager. A marketer focused on retention and who needs to know which past clients are signaling a move or a refinance might leverage the propensity models behind our Precision Marketing solution. A loan officer trying to answer "who should I call first, and why" might use Customer Intelligence, which stacks signals — equity position, rate eligibility, home-shopper behavior, life events — into a single, explainable priority list. A growth leader who needs to know which markets and real estate partners to pursue might turn to Market Intelligence. Those same loan officers, along with servicers, might also lean on OneHomeowner to stay connected with past clients year-round, surfacing opportunities before a competitor does.
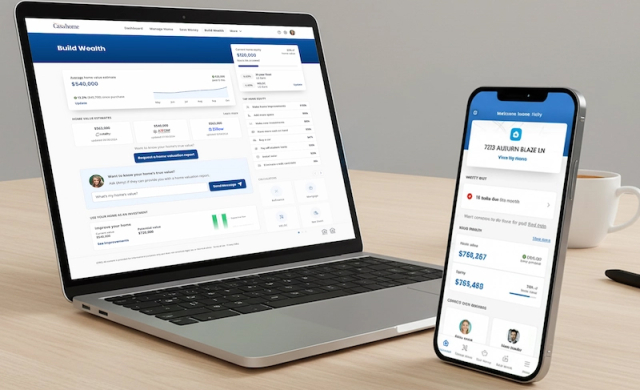
Application. Having the ability to consume the data and insight that users are looking for is also critical. On Araya, Cotality's property, market and portfolio intelligence platform, a loan officer or marketer can ask questions in plain language and get immediate answers from Aly, our AI assistant. At the other end the spectrum, more sophisticated customers and AI consumers want more options. AI agents can go directly to an MCP server and get AI-ready data, or they can plug our data into their existing AI models.
Meeting Clients Where They Are
When it comes to AI, our conversations with clients start with questions, not products. What does your data environment look like today? Who on your team needs the answer, and at what moment? Where do decisions actually get made: in a dashboard, through your LOS, a CRM or an AI assistant? What would success look like 90 days from now?
The answers to those questions point to the right mix of data, solutions, persona experiences and applications, and realistic plans for moving from pilots to practical, scalable adoption.
AI will not replace the judgment, relationships and trust essential to this business. Used well, it allows mortgage professionals more time to perfect those human elements. The goal isn't to adopt AI for its own sake but to put trusted.
Wherever you are on your AI journey, that's where we'll start.