SPONSORED CONTENT
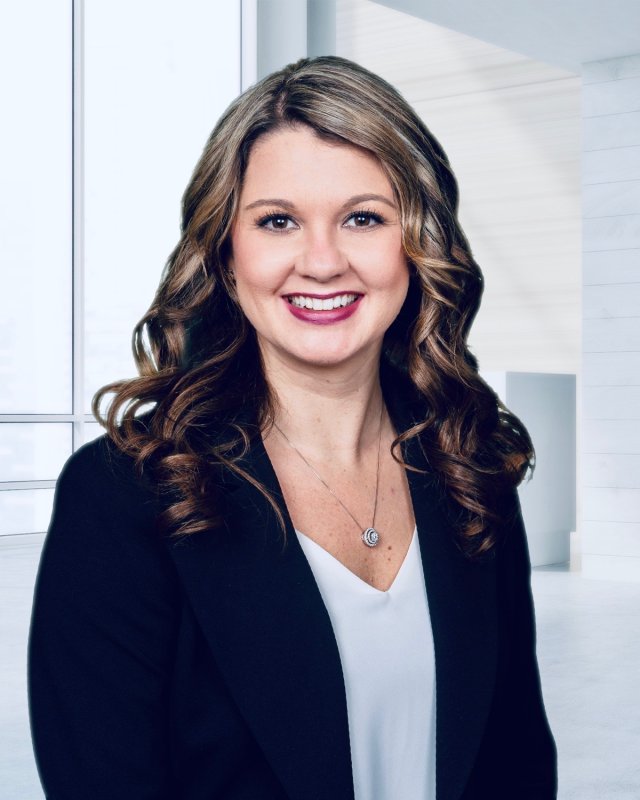
By: Ashley Wood, VP of Mortgage Verification Services, Equifax
As the housing market cools, mortgage lenders will need to maximize opportunities and minimize risk with every decision they make. Trusted income and employment data can help support this. Without secure and fast data, not only can decisioning be challenging and time-consuming, but it can also open lenders up to potential improper payments and lost opportunities.
If you’re wondering when a change in the housing market might occur – or what the severity of a potential economic downturn would be – you’re not alone. Despite industry and economist predictions, we can only make assumptions about what may happen and when. In a volatile market, mortgage lenders must do what they can to prepare for housing market headwinds. Fortunately, if the past two years have taught us anything, it is the need for businesses to be agile and adaptable.
What will the future hold for the housing market? We don't know for sure, but there are some things that mortgage lenders might want to keep an eye on as they make decisions about their business:
Flexibility will need to be a top priority for lenders. Cloud technology is key. Cloud-based technology solutions can give mortgage professionals the flexibility they need to innovate quickly, while still responding to changing market conditions. For example, lenders can tap into third-party verification data, like employment and income information from The Work Number® to help make more informed decisions, faster. Backed by the built-in speed and security of the cloud, lenders, and borrowers benefit from fewer paper-based transactions, a reduced need for multiple requests for more documents, greater flexibility when transacting (aligning with a range of consumer preferences), and ultimately a quicker time to close.
Lenders will need to broaden their customer base to remain competitive. One key challenge for lenders will be identifying and attracting newly qualified borrowers and retaining existing customers —competition will remain a factor. As lenders look to stay competitive and manage costs, they can benefit by adopting practices that help expand their borrowers from the existing applicant pool. By layering automated income and employment data along with traditional credit scores, lenders can see a more comprehensive view of the consumer’s creditworthiness, all while giving a better overall experience to consumers that have historically been excluded. Borrowers benefit from a more streamlined, efficient, and timely mortgage process, which is increasingly important in the current competitive environment.
Any amount of unproductive downtime can result in lost revenue. While disasters or worldwide pandemics that negatively impact our industry are often unpreventable, it is critical for lenders to take proactive measures to protect against downtime. In volatile market environments, third-party data partners can give lenders the ability to redirect resources as needed, ensuring that staff is focusing time and attention on prioritized, revenue-generating activities. Borrowers benefit from a more streamlined, efficient and timely mortgage process, which is increasingly important in the current competitive environment.
Fraud and misinformation in the employment verification process may still be an issue. The reality is that today’s consumers can buy just about anything on the internet — including fraudulent income and employment documents. Borrowers might also forge these documents themselves. Due to the persistence of fraudsters, pretending to be an employer it may only get easier to do so. To add, some even may have legitimate phone numbers and automated call centers. Third-party verifiers, with automated data directly from employers, can provide lenders with reliable data to help them make more informed decisions.
The Work Number® can be a sure bet in the midst of many unknowns. While no one knows exactly what the future of the housing market holds, lenders need to be prepared to make fast, informed decisions that address the changing demands of the industry and the consumers they serve. Streamlining and reevaluating processes for efficiencies to be gained is key to staying competitive – and the right technology plays a vital role. And through all this, it’s important to think about the consumer first, constantly working to meet shifting consumer demands while also helping to consider more applicants with more information.
The Work Number can help lenders mitigate risk and increase efficiencies for loan origination. Credentialed verifiers can quickly access more than 125 million active employment records from over 2 million employers. For more information, visit www.theworknumber.com.
SPONSORED CONTENT
Ashley Wood is Vice President of Mortgage Verification Services at Equifax, overseeing the strategy and deployment of the industry-leading employment and income verification solutions, including an enhanced focus on lender efficiency and borrower experience. She brings over a decade of financial services experience to the organization, and has been instrumental in driving results, diversifying consumer equities and helping more than 11.2 million U.S. consumers close home loans in the first half of this year.