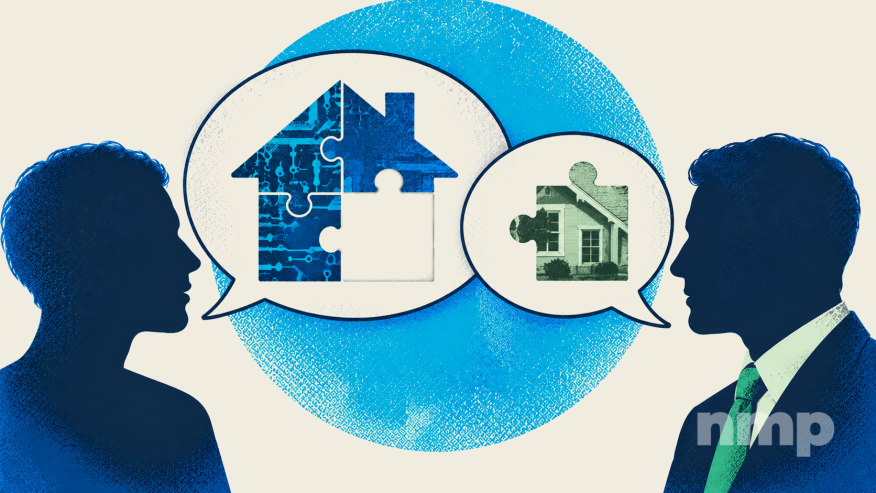
For generations, prospective homebuyers started their journey by speaking with a real estate agent, lender, family member, or financial adviser. Today, their first conversation may be with artificial intelligence instead.
According to Bank of America’s 2026 Homebuyer Insights Report, one in five prospective buyers and current homeowners used AI tools or chatbots during the past year to research homebuying topics. Usage is even higher among younger consumers, including 32% of Gen Z and 28% of Millennials.
Consumers are doing more than simply asking AI if it’s a good time to buy. Among consumers who used AI for homebuying research, 57% used it to estimate affordability, mortgage payments, or closing costs; 55% used it for general education about the homebuying process, and 52% researched neighborhoods, market trends, or property values.
While those numbers make it sound like lenders are losing their grip, it’s actually an important opportunity for them. It’s clear AI can help buyers become more informed, but it can also just as easily lead them astray with overly generalized or simply incorrect answers.
Lenders today must consider what to do when borrowers walk through their door with AI-generated homebuying assumptions.
AI Lowers the Barrier to Entry
Mortgage comes with its own vocabulary and acronyms: debt-to-income (DTI) ratios, loan-to-value (LTV) ratios, mortgage insurance, escrow accounts, points, closing costs, rate locks, and countless other terms that can feel like a foreign language, especially to first-time buyers.
Pre-AI, plenty of consumers searched the internet and sorted through articles, calculators, discussion forums, and even social media to find answers to all their initial homebuying questions, but generative AI dramatically changes that experience. Instead of interpreting what they find for themselves, consumers can now ask specific questions like: “How much house can I afford if I make $90,000 a year?” or “What happens if I put 5% down instead of 20%?” They can even ask follow-up questions until the explanation makes sense to them.
That level of accessibility is valuable. A borrower who understands more of the terminology and basic mechanics of a mortgage may enter the process better prepared to have productive conversations with their lender. However, education and advice are two very different things.
The Danger of Missing Context
People typically think about AI risk primarily in terms of “hallucinations,” where a system generates something clearly false. In mortgage lending, the problem is more insidious: an answer that sounds correct but lacks important context. A consumer might ask an AI tool how much income is required to qualify for a $400,000 mortgage. The AI can produce a perfectly reasonable-looking calculation based on assumptions about interest rates, taxes, insurance, and debt, but a real mortgage qualification depends on much more than that.
The borrower may have other debt like student loans or a car payment. Their income might include overtime, bonuses, commissions, or self-employment income that must be evaluated differently. Property taxes and insurance can vary significantly by location, and different loan programs have different requirements.
The AI-generated calculation can be useful as an estimate, but borrowers should not base a financial decision on it. AI can produce similar issues with down payment requirements, credit scores, mortgage insurance, property values, and closing costs.
Mortgage lending depends heavily on the individual borrower and transaction. Generalized information can help someone understand the process better, but specific details are best left to the experts that have the right context.
Turning the AI Answer Into a Conversation
With all this in mind, lenders should be prepared for a new type of conversation with borrowers, ones where they report that ChatGPT told them they qualify or Claude says they don’t need mortgage insurance. In those moments, lenders have an opportunity to demonstrate expertise, rather than simply telling borrowers their AI was wrong.
First, lenders should acknowledge the research. A borrower who has done their homework is engaged and better prepared; acknowledge the work done and steps taken. Next, ask about their prompt. Understanding the question, and potential assumptions behind the answer, will help quickly identify where there are gaps in the response.
From there, lenders should be taking the time to explain why the borrower’s situation differs from the assumptions behind the AI answer. Walk them through how their actual income, debts, location, or loan program options change the result. Finally, they should help them leave the conversation better educated. Walking the borrower through how their circumstances affect their options will provide a clear understanding that they can use the next time they research, whether through an AI tool or anywhere else.
This opportunity to fill in the gaps and educate borrowers is lenders’ biggest opportunity to shine. It helps borrowers come closer to achieving their homeownership goals and helps lenders build relationships that result in trust, confidence, and repeat business or referrals down the line.
Though people have more access to information than ever before, that access is making trusted human expertise even more important. Bank of America’s research provides some evidence of this. Borrowers may bypass a human and adopt AI for research, but still prefer human expertise for important parts of the transaction, including home tours or legal guidance.
People still need lenders who can help them interpret, personalize, and validate the information they encounter online. While lenders may no longer be the primary source of information for some borrowers, they can still be the trusted interpreter.
Borrowers Expect Both
AI adoption in housing is still relatively early. If one in five consumers is already using these tools for homebuying research, however, lenders should expect that number to grow. Tomorrow’s borrower may begin researching a mortgage with an AI assistant, compare homes using digital tools, complete much of an application online, and still expect a knowledgeable professional to be available when the decisions become complicated.
That is where lenders can fine-tune their experience: high-tech when technology makes the process easier, and high-touch when expertise and judgment matter most.
The lenders that succeed in that environment will not be the ones trying to convince borrowers to stop using AI altogether. They will be the ones borrowers trust to tell them when the AI answer is useful, when it is incomplete and what it means for their specific path to homeownership.
Jose Bellido is Senior Director of Underwriting at Enact Mortgage Insurance, where he leads underwriting operations and works to modernize the underwriting experience through innovation, including the responsible use of generative AI. The statements expressed in this article are solely the opinions of Jose Bellido and do not necessarily reflect the views of Enact or its management.