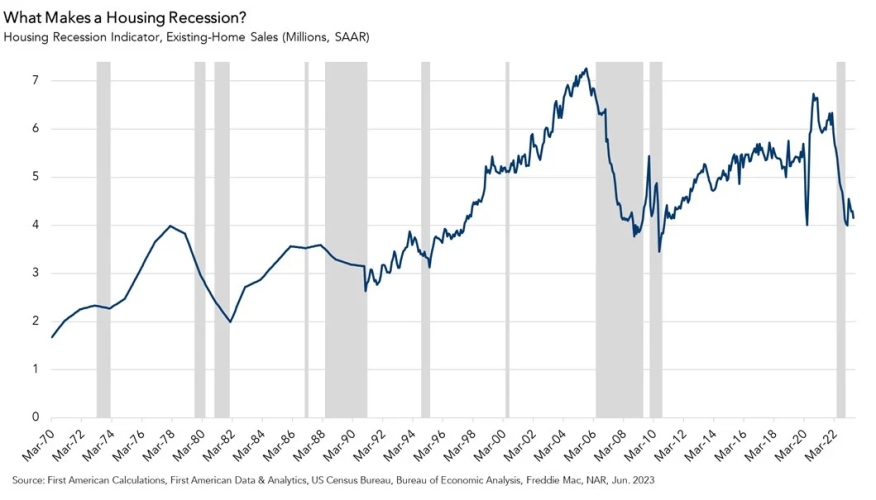
The bad news is the housing market has been firmly involved in a double-dip recession. The good news? It seems that the worst of this housing recession is behind us.
The overall housing market's double-dip recession was inclusive of both existing- and new-home markets. That’s the thrust of a commentary released today by First American Deputy Chief Economist Odeta Kushi. She wrote, “June and July data [are] still trickling in, but early signs point to a double-dip recession that began to take form in March of this year. It is not surprising that the housing market continues to struggle, even if a small segment of the housing market, new construction, seems to be bucking that trend.”
Kushi explained, “Existing homes make up the bulk of total inventory, and existing homeowners are not selling. Potential home buyers are still contending with higher mortgage rates and a limited inventory of homes for sale.”
She continued, “As long as the Fed’s fight against inflation persists, it will continue to put downward pressure on the housing market because mortgage rates typically follow the same path as long-term bond yields, which move with inflation expectations and the Fed’s actions. But housing recessions come in all shapes and sizes, and it seems that the worst of this housing recession is behind us.”
There may not be universal agreement yet with Kushi’s optimism. Marty Green, a principal at Dallas-based Polunsky Beitel Green, told NMP the housing sector is again showing signs of slowing, with inventory once again a critical issue. “The higher mortgage rates triggered by the Fed’s policy have caused more sellers to sit on the sidelines given the large differential between the rate they enjoy on their current home compared to the possible interest rate on any home they may purchase today,” Green said. “This means buyers have fewer choices and may sit on the sidelines as well. If the Fed isn’t careful, this critical industry may once again slow to a crawl in the fall and winter.”
The First American housing recession model is based on the following indicators: average hourly earnings of non-supervisory construction workers; the total number of employees in residential building construction; the total number of employees in real estate rental and leasing; the number of single-family housing starts; private residential fixed investment; personal consumption expenditures on housing and utilities; existing-home sales; and our Real House Price Index, which is a measure of affordability. “If the moving average of the monthly growth rate of four of the eight indicators is negative for at least three consecutive months, then a housing recession has begun,” Kushi explained.
Kushi added that the housing recession of 2022 began in May and ended in November. The average 30-year fixed mortgage rate increased by 1.6 percentage points during those months, which resulted in a 14% decline in affordability. As a result of the rapid decline in affordability, builders pulled back on breaking ground on more homes. Additionally, higher mortgage rates had a dual impact on existing-home sales – pricing out buyers who lost purchasing power and keeping some potential sellers’ rate-locked in, resulting in fewer transactions.
The housing market recession paused in December as rates came down from recent highs, and in the first couple months of 2023, the housing market began to recover as rates stabilized and the new home market began to take market share from the existing-home market. Yet, mortgage rates once again trended higher in May, and affordability suffered as a result. Sales of existing homes have remained low.