The Federal Housing Finance Agency (FHFA) released its National Mortgage Database (NMDB) as is required by the Housing and Economic Recovery Act of 2008 to conduct a monthly mortgage market survey on the characteristics of individual mortgages, and to make the data available to the public.
The NMDB is a nationally representative 5% sample of residential mortgages in the United States. This program is designed to provide a rich source of information about the U.S. mortgage market broken down by three primary components: the National Mortgage Database (NMDB), the quarterly National Survey of Mortgage Originations (NSMO), and the annual American Survey of Mortgage Borrowers (ASMB).
The NMDB includes residential mortgage performance statistics and outstanding residential mortgage statistics.
In the fourth quarter of 2023, 1.8% of all mortgages were 30 to 60 days past due on their payments, up 0.4 percentage points from last year. Only 0.6% of mortgages were 90 to 180 days past due, up 0.1 percentage point from the year past, and 0.1% of mortgages were in foreclosure, bankruptcy, or deed-in-lieu, with no change year-over-year.
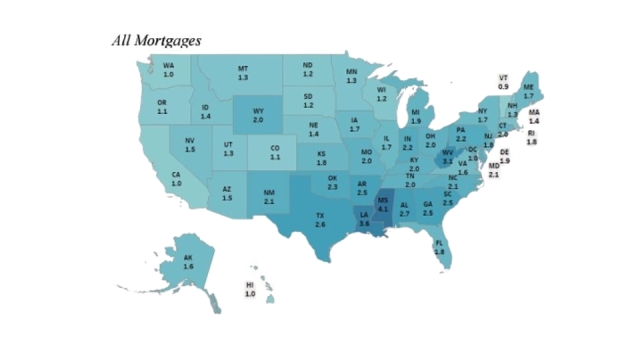
Percent 90 to 180 Days Past Due Date by Market Segment and State, 2023 Q4, NMDB data by FHFA.
Mississippi (4.1%), Louisiana (3.6%), West Virginia (3.1%), and Kentucky (0.3%) had the highest past due shares in the fourth quarter of 2023. But one New England state appears as well. Connecticut had the highest past due share among enterprise loans, at 1.1%.
Get the NMP Daily
Essential stories, every weekday.
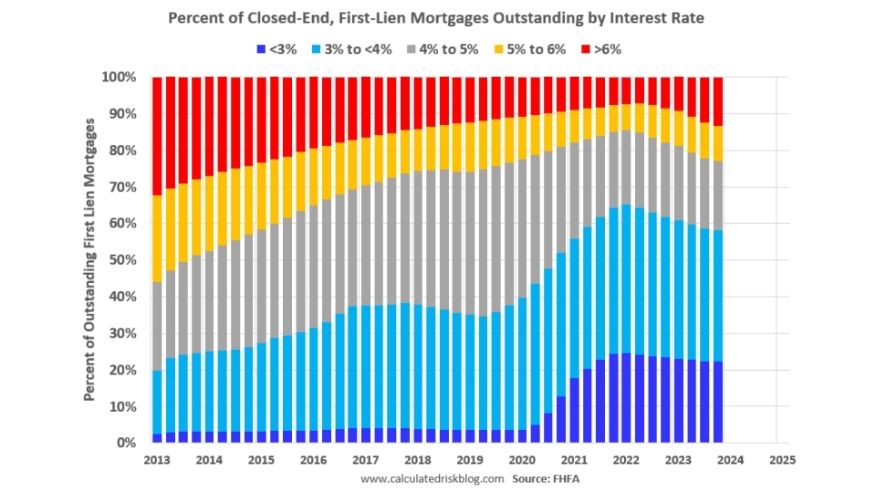
The data also shows evidence of the lock-in effect on closed-end, fixed-rate mortgages on one-to-four family properties that are outstanding. Starting in early 2020, there has been a surge in the percentage of loans under 3%, and also under 4%, since mortgage rates declined sharply during the pandemic. The percentage of outstanding loans under 4% peaked in the first quarter of 2022 at 65.3% (now at 58.1%), and the percentage of mortgages under 5% peaked at 85.6% (now at 77%). The percent of loans over 6% bottomed in the second quarter of 2022 at 7.2% and increased to 13.4% in the fourth quarter of 2023.
In all, while the lock-in effect does show signs of easing, it may take a while to fully cool off.
The modest decline trims borrower payments, while year-end forecasts above 7% leave LOs focused on deals already close to working
The first mortgage-rate decline in two months trims about $22 from the monthly payment on a $400,000 loan. For LOs trying to salvage year-end transactions, that creates an opening among borrowers already close to making the numbers work.Freddie Mac reported Thursday that the...
NMP’s Ignite summit explored the rules, expenses, and platform differences that shape what originators actually earn
A loan officer willing to earn less to win a borrower can still run into a compensation problem. The sticking point is how that smaller paycheck is determined, who funds it, and whether the arrangement connects compensation to the loan’s terms.That tension drove National Mor...
DPR’s Q3 report identifies 311 programs without income limits and 1,080 without first-time buyer requirements, though funded availability grew more slowly than the overall count