According to CoreLogic’s Home Equity Report (HER) for the second quarter of 2022, homeowners are still gaining near-record equity, despite home-price growth slowing on an annual basis in the second quarter.
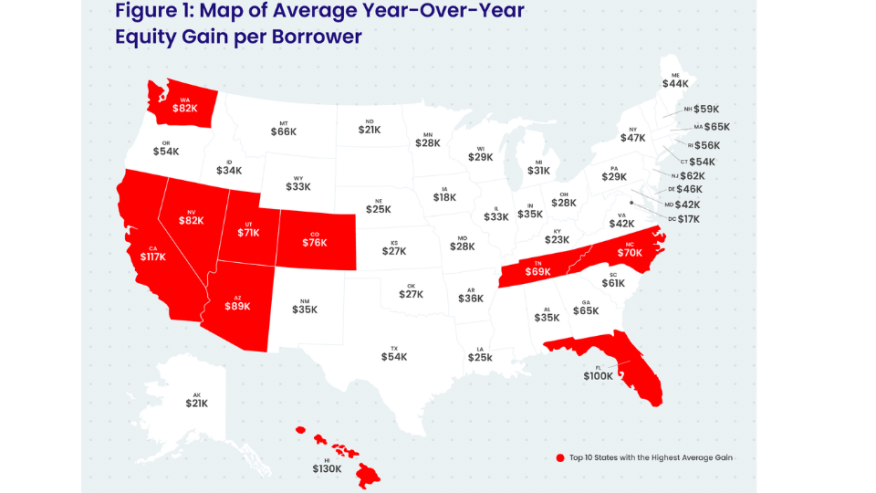
U.S. homeowners with mortgages — which accounts for roughly 63% of all properties — saw equity increase by 27.8% year-over-year. This represents a collective gain of $3.6 trillion, or an average of $60,200 per borrower, since the second quarter of 2021.
The total average equity per borrower has now reached $300,000, the highest in the data series. Fifteen states post higher gains than the national average, led by Hawaii, California, and Florida.
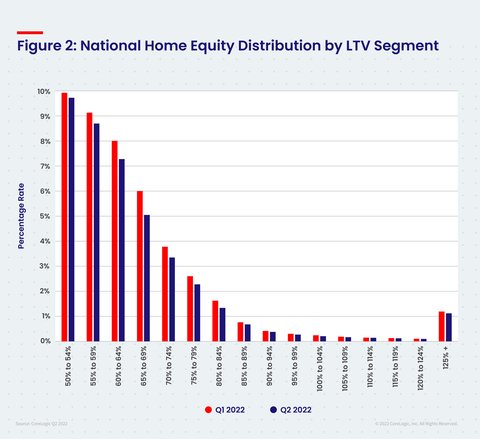
Home price growth and the refinance boom that transpired over the past two years have helped bring down the national average loan-to-value ratio to 42%, the lowest in the data series since 2010.
“For many households, home equity is the only source of wealth creation,” said Selma Hepp, interim lead of the Office of the Chief Economist for CoreLogic. “As a result, recent record gains in equity and record declines in loan-to-value ratios will provide many owners with a financial buffer in case economic conditions worsen. In addition, record equity continues to provide fuel for housing demand, particularly if households are relocating to more affordable areas.”
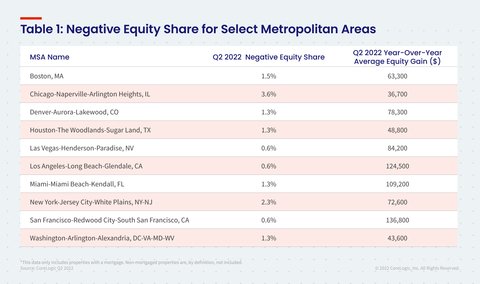
Negative equity, also known as underwater or upside-down mortgages, applies to borrowers who owe more on their mortgages than their homes are currently worth. From the first quarter to the second quarter of 2022, the total number of mortgaged homes in negative equity decreased by 7% to 1 million homes, or 1.8% of all mortgaged properties. Compared to the second quarter of 2021, the total number of mortgaged homes in negative equity decreased by 18%.
Home equity is primarily affected by home price changes. Borrowers with equity positions near (+/- 5%) the negative equity cutoff are most likely to move out of or into negative equity as prices change. CoreLogic predicts that if home prices increase by 5%, 116,000 homes would regain equity. Yet, if home prices decline by 5%, 148,000 properties would fall underwater.