Fewer borrowers opted to delay or reduce their loan payments in March, according to the Mortgage Bankers Association.
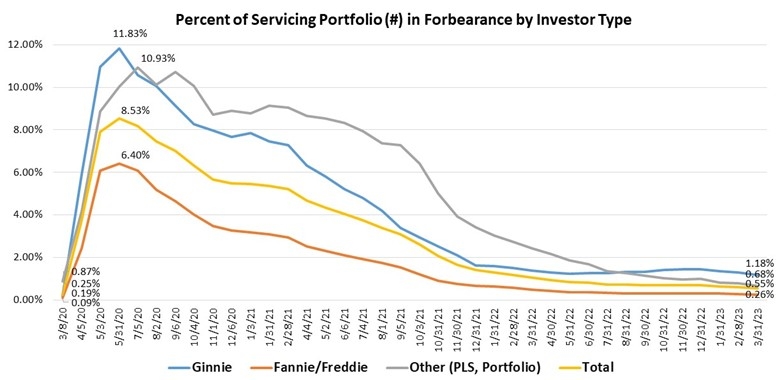
The MBA’s monthly Loan Monitoring Survey (LMS) indicated the number of loans in forbearance dropped by five basis points between February and March from 0.60% to 0.55%.
“As the COVID-19 national emergency draws to a close, the number of loans in forbearance continues to drop,” MBA Vice President of Industry Analysis Marina Walsh said. “Mortgage performance remains strong with the percentage of borrowers who were current on their mortgage payments and post-forbearance workouts increasing in March.”
The MBA estimates that about 275,000 homeowners are currently in forbearance plans.
Business economists and trade associations across the U.S. did predict a recession in 2023, which has the potential to impact loan repayment trends.
“MBA’s forecast still calls for a recession in 2023, which may change the current performance levels, but credit quality is generally good and many borrowers facing financial hardship can now access enhanced loss mitigation options that resulted from successes of pandemic-related policies,” Walsh pointed out.
Among the LMS’ other key findings, the amount of delinquent and foreclosed loans in servicers’ portfolios decreased by 0.59% during that same time frame.
Current loans comprised 96.35% of their portfolio volume in March, versus 95.76% in February, without any seasonal adjustments.
Different lenders reported varying decreases in basis points relative to the prior month.
The share of Fannie Mae and Freddie Mac loans in forbearance decreased two basis points - from 0.28 to 0.26% during that period.
Ginnie Mae loans in forbearance decreased 10 basis points to 1.18% and their share among portfolio loans and private-label securities (PLS) also dropped 10 basis points, to 0.68%.
Those lent by Independent Mortgage Banks (IMBs) decreased from 0.81% to 0.74% and from depositories, 0.40% to 0.36%.
The survey represents 32.7 million loans, or approximately 65% of the first-mortgage servicing market.
Over the last three years, over 7.8 million borrowers have been serviced while in forbearance, according to the MBA.
About one-third of loans in forbearance are in the initial plan stage; 52.9% are in an extension and the remaining 13.3% are re-entries.
Between June 1, 2020 and March 31, 2023, 29.6% of borrowers who exited forbearance deferred their loan or made a partial claim.
18.0% of all exits represented borrowers who did not default on their monthly payments during their forbearance period.
A similar amount (17.7%) exited forbearance without a loss mitigation plan in place and not having completed all payments.
Loan or trial loan modifications were made in 16.1% of forbearance exit cases.
About 11% of people who exited forbearance reinstated their loans, paying back past-due amounts.
Loans that were paid off by refinancing or selling a home represented 6.5% of forbearance exits.
The remaining 1.2% ended via repayment plans, short sales, deed-in-lieus or for other reasons.
The states with the least amount of loans in forbearance were Washington, Idaho, Colorado, Utah and California.
The states with the most loans in forbearance were Louisiana, Mississippi, New York, Oklahoma and West Virginia.