Put politicians and politics aside. Down payment assistance (DPA) is alive and well and active in America.
Some 43 programs were started in the first quarter this year alone, bringing the total nationally to more than 2.500, according to Down Payment Resource (DPR), a company that connects homebuyers with DPA programs.
That DPA is healthy, growing, and critical to today’s housing market has DPR Chief Executive Rob Chrane a bit miffed at lawmakers who question the future availability of homebuyer assistance for low and moderate-income buyers.
“With inventory tight in many housing markets across the country, it’s more important than ever to use every available tool to connect qualified buyers with homes.” —Rob Chrane, CEO, Down Payment Resource
His Atlanta-based firm has been tracking and analyzing assistance programs since 2008. “At DPR, our mission has always been to connect lenders and real estate professionals with the resources that make homeownership possible,” Chrane told National Mortgage Professional.
“We don’t just believe in DPA,” he added. “We’ve built our business around it, and back our ‘feelings’ with data.”
He also noted that as a privately owned company, DPR is “not beholden to government oversight or restrictions on what we can publish.”
His data shows that the programs DPR tracks offer an average benefit of $18,000. Many down payment assistance programs can be used to purchase manufactured housing — an affordable price entry point for some buyers — or multi-family housing, a draw for many other buyers.
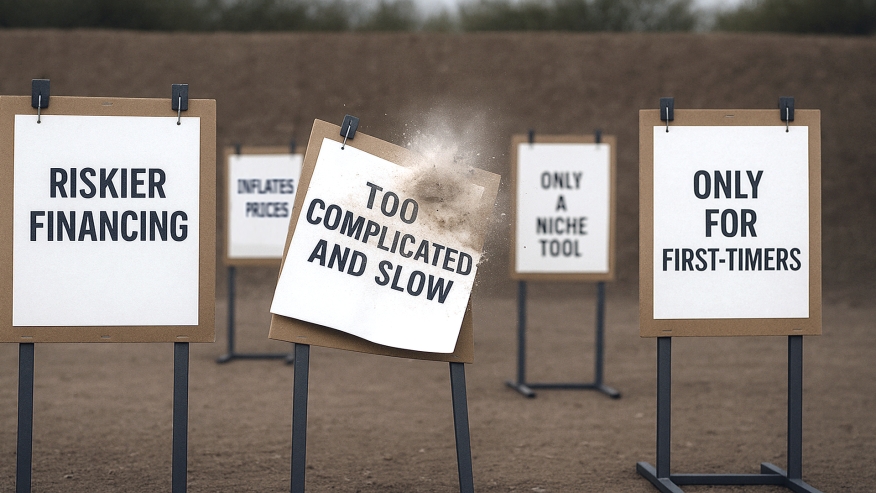
Chrane commented on some of the myths that commonly pop up when DPA is part of the conversation:
- DPA makes financing riskier. Not so, Chrane says, noting that borrowers still have to qualify for a mortgage. That means meeting the same credit, income, and debt-to-income standards as other buyers. In many cases, he added, DPA lowers risk by reducing the LTV ratio, sometimes by as much as 6%, thereby strengthening a borrower’s profile and helping him or her secure better loan terms.
- DPA inflates home prices. “Helping buyers afford a home doesn’t raise prices, it expands access for only a segment of the housing market — primarily entry-level buyers,” Chrane argues. “With inventory tight in many housing markets across the country, it’s more important than ever to use every available tool to connect qualified buyers with homes.”
- It’s too complicated and slow. “Like any financing tool, DPA requires planning, but it’s not a roadblock,” Chrane maintains, noting that many programs are designed for quick approvals and integrate seamlessly into the lending process. Smart lenders, he adds, use DPA as a proactive purchase strategy to serve more buyers and compete more effectively in a challenging market.
- DPA is only for low-income or first-time buyers. Yes, some programs have enhanced benefits and/or eligibility rules for low-income households. But many do not. And a surprising number are open to repeat buyers and moderate-to-middle-income households. “Eligibility criteria vary, and savvy buyers — and their lenders — know to look beyond the headlines,” Chrane says. He also points out that DPA often is pegged for teachers, first responders, veterans, healthcare workers, and others with stable, well-paying jobs.
- DPA is a niche tool. Hardly so, says Chrane. In the first year after Zillow went live with its DPR integration in December 2021, more than a million unique users searched for their down payment assistance eligibility. That suggests the need is far more widespread. Further, 93% of people who searched on Zillow for eligibility were matched with at least one assistance program. During the first three years on Zillow, more than 5 million unique visitors completed the eligibility form found on qualified listings.
“For most, this was their very first exposure to the concept of DPA,” says Chrane. “They may have never heard the term, but they clearly understood the message that help is available.”