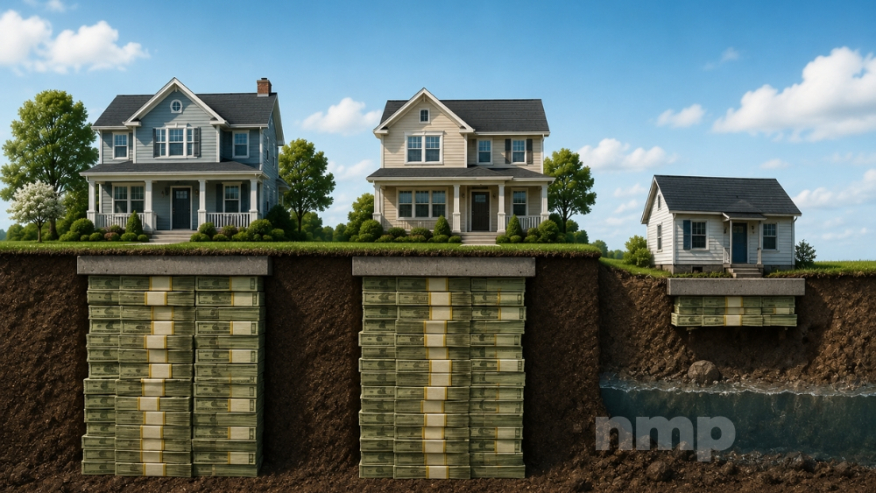
Mortgage holders collectively entered the third quarter with nearly $18 trillion in home equity, but that record wealth is obscuring mounting distress among recent FHA and VA borrowers who bought near the top of their local markets.
Some 320,000 homeowners were both underwater and behind on their mortgage payments entering the third quarter, nearly double the 163,000 recorded a year earlier, according to ICE’s August Mortgage Monitor. Those borrowers have fewer options to sell, refinance, or otherwise avoid foreclosure if their financial position deteriorates.
Overall, approximately 813,000 mortgage holders remained underwater at the end of the second quarter. That was the lowest level in 10 months as spring price gains restored equity for some borrowers, but it was still 44%, or 250,000 borrowers, higher than a year ago.
The risk is highly concentrated. ICE found that 85% of underwater borrowers took out their mortgages in 2022 or later, and three out of four financed their purchases with low-down-payment FHA or VA loans.
Texas and Florida accounted for 39% of underwater mortgages nationwide. Cape Coral, Florida, had the highest negative-equity rate among major markets at 11.4%, followed by Lakeland, Florida, at 7.5%; San Antonio at 6.9%; and Austin at 6.6%.
The figures reveal a divided housing market: longer-tenured homeowners are sitting on substantial equity, while a smaller but growing group of recent buyers has little protection against falling prices, payment trouble, or an unexpected financial setback.
Government-Backed Loans Bear More Stress
The negative-equity data aligns with broader deterioration among some government-backed mortgages.
The share of FHA borrowers at least 90 days delinquent or in active foreclosure reached 5.7% in June, up 1.8 percentage points from a year earlier. The comparable VA rate reached 2.3%, an increase of 0.4 percentage points.
New VA defaults rose 25% year over year during the second quarter, the largest increase among the major loan categories ICE analyzed. FHA performance showed some improvement at the front end, with new FHA defaults falling 11% in the quarter, largely because fewer previously delinquent borrowers fell behind again.
The growing pressure remains visible in foreclosure inventory. Loans originated in 2022 or later now account for nearly 35% of active foreclosures, reflecting the vulnerability of borrowers who purchased after rates and prices had already risen but have since experienced limited appreciation.
That continues a trend NMP highlighted earlier this year, when the end of temporary FHA relief programs contributed to rising late-stage delinquencies.
The national picture, however, does not suggest a foreclosure crisis. The share of mortgages in active foreclosure reached a six-year high of 0.53% in June but remained below the 0.57% recorded in June 2019. June foreclosure sales increased 16% annually to 7,300 but were still 46% below their pre-pandemic level.
Record Equity, But Limited Growth
The other side of the market remains flush with housing wealth.
Mortgage holders had nearly $18 trillion in equity at the end of the second quarter, including $11.7 trillion considered tappable—equity that could be withdrawn while leaving the borrower with at least a 20% cushion. Nearly 47.5 million mortgage holders had some tappable equity.
Both total and tappable equity increased only 1% from a year earlier, however. Markets were nearly evenly divided, with 53% recording annual equity growth and 47% experiencing declines.
New York led the country in equity gains. Syracuse, Albany, and New York City each posted tappable-equity growth of more than 10%, while markets in Florida, Colorado, and Ohio recorded some of the largest declines.
For originators, that split argues against treating the $18 trillion as a single nationwide opportunity. Established homeowners with substantial equity remain prospects for HELOCs and closed-end second mortgages, particularly if they are unwilling to refinance a low-rate first mortgage. Recent buyers in weakening markets may require a different conversation centered on payment sustainability, product structure, and realistic property values.
That home-equity channel is already becoming more important. Second-lien lending reached an 18-year high earlier this year as borrowers increasingly sought cash without replacing their existing first mortgages.
Similar Borrowers Still Receive Different Rates
ICE also found substantial differences in the rates received by borrowers with otherwise similar profiles.
After controlling for credit score, loan-to-value ratio, loan purpose, balance, debt-to-income ratio, property type, occupancy, loan program, and lender channel, approximately 70% of same-day variation in locked rates remained unexplained by observable borrower or loan characteristics.
Among comparable conforming purchase borrowers, rates varied by 38 basis points across the middle 50% of 2026 locks. The difference widened to 82 basis points between borrowers at the 10th and 90th percentiles.
On a $300,000 conforming mortgage, the middle spread produced a $76 difference in monthly payments and approximately $5,800 over five years. Across the wider 10th-to-90th percentile range, the difference reached $162 per month and approximately $12,300 over five years.
Dispersion was even wider among comparable FHA and VA borrowers, at 47 and 48 basis points, respectively, across the middle half of outcomes. Lower-credit conforming borrowers, small-balance borrowers, cash-out refinance customers, and borrowers with loan-to-value ratios above 95% also experienced larger pricing differences.
“Mortgage rates are often discussed as if borrowers face a single market rate on any given day,” ICE said in the report, “but borrowers with nearly identical credit profiles routinely lock in meaningfully different rates from different lenders.”
For loan originators, that finding makes the value proposition more concrete. The borrowers facing the greatest affordability pressure often occupy the segments with the widest pricing variation. Product selection, lender access, overlays, mortgage insurance, and careful comparison can therefore make the greatest financial difference for borrowers with the least room in their budgets.
Price Growth May Have Limited Runway
Annual home-price growth accelerated for a fifth consecutive month in July, reaching a 14-month high of 1.5%. But the headline acceleration partly reflected weak prices from summer 2025 falling out of the year-over-year comparison.
Seasonally adjusted prices increased 0.19% in July, down from 0.27% in March and April. July’s monthly increase equated to a 2.2% annualized pace, suggesting that substantially faster appreciation is unlikely under current rate, affordability, and inventory conditions.
“Mortgage holder equity hitting $18 trillion is a remarkable milestone—one that reflects just how much wealth American homeowners have built,” said Andy Walden, ICE’s head of mortgage and housing market research. “At the same time, rates have trended higher since early in the year, which may soften how much additional acceleration we’re likely to see in the second half.”
That leaves the market with two very different borrower populations: millions of established homeowners who can tap accumulated wealth, and a smaller concentration of recent FHA and VA borrowers whose limited equity is becoming a serious constraint.