CoreLogic determines how many loans would be ripe for a refi if rates drop again
KEY TAKEAWAYS
46.2% of the loans in the servicing sample are “refinance burnouts”
Nearly half (46.1%) of the loans in this sample are "locked-in" to ultra-low rates
Only 7.7% of loans in the sample are candidates for a lower rate refinance if rates drop to or below 6%
As mortgage rates tick down and expectations rise for multiple rate cuts by the end of 2024, lenders and originators have begun preparing for another refinance wave. After reviewing 15.7 million first-lien mortgages currently in servicing, CoreLogic discovered an overwhelming majority of U.S. household mortgages are either locked into a low-rate mortgage or “refinance burnouts.”
As of mid-August, 30-year-fixed mortgage rates eased slightly from their peak in the mid-7% range to the mid-6% range, prompting many homeowners who borrowed at interest rate heights to consider refinancing for lower mortgage payments. According to the Mortgage Bankers Association (MBA), refinance applications in August 2024 more than doubled from last year.
Still, lenders and mortgage professionals want to know how many homeowners are likely to find meaningful reductions in their monthly mortgage payments by refinancing to rates in the lower 6% range.
CoreLogic estimates 4 million loans were originated during the period of high interest rates 2023-24.
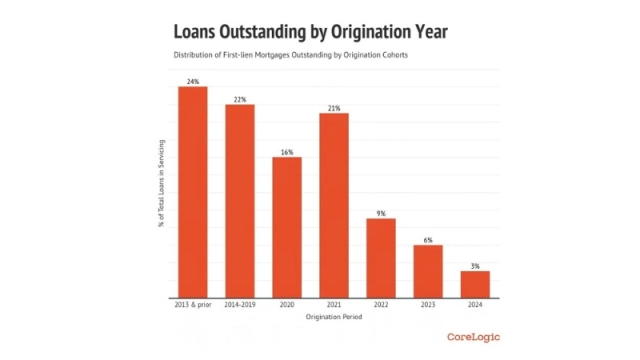
Broken down by year, 46.2% of the loans reviewed in CoreLogic's servicing sample were originated before the 2020 pandemic, making them more seasoned loans. Twenty four percent (24%) of those loans were originated in 2013 or prior, and 22.2% of loans were originated between 2014 and 2019. Because those are seasoned loans that have had plenty of opportunities for a lower rate refinance, CoreLogic calls them “refinance burnouts.”
Nearly half (46.1%) of the loans in this sample portfolio were originated between 2020 and 2022, when interest rates were at record lows. These loans are “locked-in” to their existing low and ultra-low rates.
Get the NMP Daily
Essential stories, every weekday.
Loans originated in 2023 and 2024 comprise just 7.7% of the 15.7 million loans in servicing that CoreLogic analyzed. Many of those loans are deemed already “in the money” candidates for a lower rate refinance, or will be among the first in line to apply for refinancing should interest rates drop to (or below) 6%.
As of June 2024, an estimated 4 million outstanding loans were originated during the period of high interest rates in 2023 and 2024. The total outstanding loan volume was estimated to be 51.97 million, with an average loan balance of $240,900. High-rate loans represent an estimated $1.452 trillion in outstanding unpaid mortgage balances, originated during the high interest rate period of 2023-2024.
However, with more than $12 trillion of total outstanding U.S. mortgage debt, even a small percentage of “in-the-money” loan balances can amount to hundreds of billions of dollars of originations for lenders. Average loan sizes for those with an interest rate of 6.75-7.5%, or at or above 7.5%, are $265,000 and $196,000, respectively.
As of June 2024, an estimated $579 billion in loan balances are carrying an interest rate in the 6.75% to 7.5% range, and an additional $157 billion in loan balances are at or above 7.5%. This results in a combined total of $735 billion in loans that could benefit from a refinance if rates drop further to near or below 6%, CoreLogic reports.
Proposition 37 could open new purchase lending opportunities, but financing costs and borrower qualification will determine its reach
California voters have approved a $25 billion homebuyer financing initiative that could create new purchase mortgage opportunities for lenders and brokers, particularly those working with homebuilders.Proposition 37, which passed with more than 60% of the vote in the Nov. 3 ...
As investor purchases decline, DSCR loans capture a growing share of Non-QM lending, creating opportunities for brokers who understand the differences between lender programs
Real estate investors are buying fewer homes than they did a year ago, yet debt service coverage ratio (DSCR) lending continues to gain ground in the market. A big part of the reason is that DSCR loans are purpose-built for property investors. Agency loans qualify borrowers ...