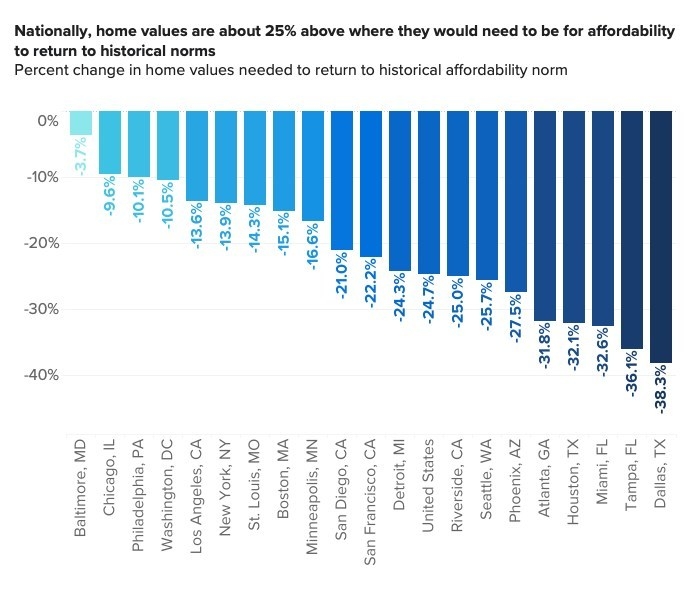
It’s clear that housing affordability is at a low and not returning to normal anytime soon, especially with home values 24.7% above where they would need to be for affordability to return to recent norms. That’s according to a new Zillow report, and shows that housing relief isn’t here quite yet.
The monthly mortgage payment on a typical U.S. home is about $1,850 — 75.5%, or about $800, higher than it was last year. Home values have fallen a bit since the peak in June, but rising mortgage rates have overwhelmed those small affordability gains.
Mortgage affordability has risen to 30.2% nationally, before including the cost of taxes and insurance. Zillow says that’s above the 30% threshold for households to be considered cost burdened, and much higher than the 2005–21 average of 22.8%.
"The next several years appear set up for affordability to be a major challenge for homebuyers," said Zillow Senior Economist Nicole Bachaud. "Inventory remains tight, real income growth is dismal, mortgage rates show no signs of dropping, and there is plenty of pent-up demand ready to bid prices back up if they reach a level would-be buyers can once again afford."
Bachaud added that, "Filling the housing deficit continues to be the key to long-term affordability, but the recent slowdown in single-family construction is not a good sign that the market is getting closer to building enough to meet demand."
For mortgage affordability to return to the 22.8% norm nationally, U.S. home values would need to fall nearly a quarter, or 24.7%. However, some markets are almost back to their historical affordability norms, such as Hartford, Conn. Hartford home values are only 2.4% higher than where they would need to be.
In Baltimore, they are 3.7% higher than what their affordability norm once was. Other markets, though, have seen affordability deteriorate much more. Salt Lake City; Nashville, Tenn.; Dallas; and Las Vegas are furthest away from their historical affordability, at least 37% above where they would need to be to once again reach that level.
Zillow's forecast calls for home values to remain nearly flat in the 12 months ending September 2023. Zillow says it would take a sharp increase in inventory for home values to fall dramatically. While inventory is ticking up, it remains nearly 40% below pre-pandemic levels.
New listings are slowly coming onto the market, but still down 16% in September compared to a year prior. In 2022 to date, there have been about 11% fewer homes listed than at this point in 2019. Many homeowners have mortgages with low rates from purchasing or refinancing earlier in the pandemic, and have very little financial incentive to sell.