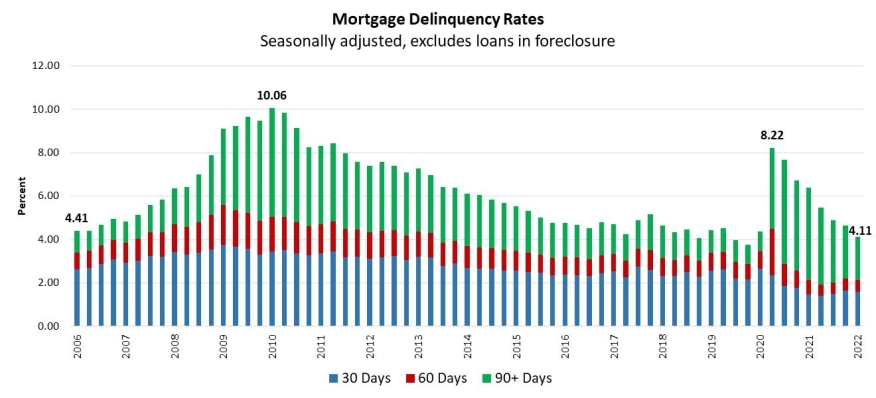
Mortgage delinquencies for the first quarter of 2022 were down to 4.11% for mortgage loans on one-to-four-unit residential properties. That’s the seventh straight quarter in which delinquencies have declined.
The Mortgage Bankers Association asked servicers to report loans in forbearance as delinquent if the payment was not made based on the original terms of the mortgage. The delinquency rate decreased 54 basis points from the fourth quarter of 2021 and was down 227 basis points from one year ago.
By loan type, the total delinquency rate for conventional loans decreased 55 basis points to 3.03% over the previous quarter,, the lowest level since the fourth quarter of 2019. The FHA delinquency rate decreased 118 basis points to the lowest level since the fourth quarter of 2019 (9.58%), and the VA delinquency rate decreased by 38 basis points to 4.86%, the lowest level since the first quarter of 2020.
“The mortgage delinquency rate dropped for the seventh consecutive quarter, reaching its lowest level since the fourth quarter of 2019,” said Marina Walsh, MBA’s vice president of industry analysis. “The decrease in delinquency rates was apparent across all loan types, and especially for FHA loans. The delinquency rate for FHA loans declined 118 basis points from fourth-quarter 2021 and was down 509 basis points from one year ago.”
According to Walsh, most of the improvement in loan performance can be attributed to the movement of loans that were 90-days or more delinquent. The majority of these aged delinquencies were either cured or entered post-forbearance loan workouts.
The expiration of pandemic-related foreclosure moratoria led to a modest increase in foreclosure starts from the record lows maintained over the past two years. At 0.19%, the foreclosure starts rate remains below the quarterly average of 0.41% dating back to 1979.
Added Walsh, “Given the nation’s limited housing inventory and the variety of home retention and foreclosure alternatives on the table across various loan types, the probability of a significant foreclosure surge is minimal. Borrowers have more choices today to either stay in their homes or sell without resorting to a foreclosure.”