Newrez's Brittany Boccher says qualified veterans are being directed toward conventional financing, costing originators opportunities to serve borrowers who may benefit from VA loans
Mortgage lenders may be losing qualified VA borrowers because of their own lending practices and misconceptions about the program, rather than the eligibility requirements established by the Department of Veterans Affairs.
“In my opinion, the industry loses more VA borrowers through misinformation than through qualification issues,” Brittany Boccher, national director of military strategy and military engagement at Newrez, shared with National Mortgage Professional for Veterans Day.
Boccher said eligible veterans are still being directed toward conventional financing because some mortgage professionals assume VA loans take longer to close, create appraisal problems, or make offers less attractive to sellers.
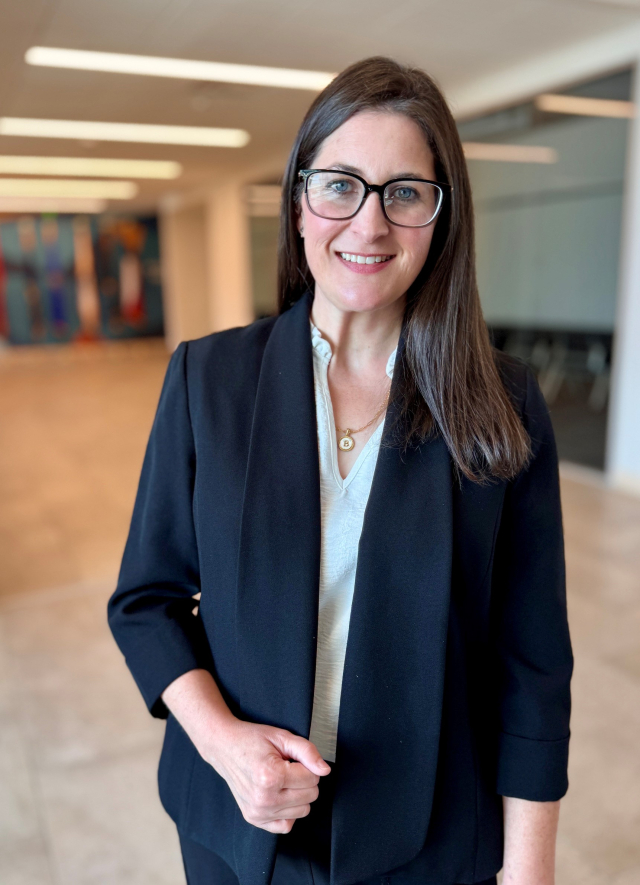
Brittany Boccher, National Director of Military Strategy & Military Engagement at Newrez
"These assumptions often push borrowers toward products that may not be their best financial option," she said. "The reality is that many borrowers who leave the VA process are not leaving because of VA guidelines. They are leaving because of communication breakdowns, lack of product knowledge, or unnecessary complexity introduced into the process."
Lender Overlays Create Additional Hurdles
Boccher said some of the biggest opportunities to improve VA lending lie in how lenders apply the program's requirements, rather than in changes to the guidelines themselves.
Get the NMP Daily
Essential stories, every weekday.
"Many military borrowers face unnecessary barriers due to lender overlays, conservative underwriting practices, or a lack of familiarity with military income, PCS moves, non-traditional credit, and entitlement usage," she said.
Some lenders impose minimum credit scores, debt-to-income restrictions, or documentation requirements beyond those required by the VA, potentially excluding borrowers who could otherwise qualify.
Boccher also identified inconsistent treatment of manually underwritten loans and military-specific income scenarios as areas where lenders could improve execution.
"From our perspective, the biggest opportunities for improvement are often not within the VA guidelines themselves, but in how lenders implement them," she said.
At Newrez, Boccher said the company has sought to address those barriers through specialized training, dedicated VA policy support, and closer alignment with the program's guidelines while maintaining responsible lending practices.
Misconceptions Persist Among Experienced LOs
The knowledge gaps are not limited to newer LOs.
Boccher said experienced mortgage professionals continue to misunderstand VA residual income requirements, entitlement restoration, assumability, seller concessions, appraisal procedures, and eligibility for National Guard and Reserve borrowers.
"Perhaps the biggest misconception is that VA loans are more difficult than conventional loans," she said. "Many loan officers simply originate fewer VA loans and therefore lack confidence in the product."
That lack of familiarity can affect which financing options originators recommend.
"We've found that when loan officers better understand VA guidelines, they are more likely to recommend the VA loan as the first solution instead of defaulting to a conventional product," Boccher said.
Newrez has invested in Military Lending Professional certification, continuing education, dedicated policy expertise, and access to specialists who can assist originators with individual loan scenarios.
Boccher said the company has seen increased engagement, repeat usage, and stronger referral activity among originators participating in VA-focused education programs.
VA Purchase Business Remains A Priority
Boccher said Newrez experienced an increase in VA Interest Rate Reduction Refinance Loans earlier in 2026, although purchase lending has remained the primary driver of its VA business.
The company is also seeing strong interest from first-time military homebuyers, she said.
Today's VA borrowers are often better informed before contacting a lender, but the information they find online can be incomplete or inaccurate.
Some veterans still believe their VA benefit can only be used once or that they cannot subsequently rent out a home purchased with VA financing, according to Boccher.
Misconceptions also persist among real estate professionals, particularly concerning appraisal requirements, closing timelines, and the competitiveness of VA offers.
"Many concerns around closing timelines, appraisals, or fallout rates are rooted in outdated perceptions rather than current performance," Boccher said.
She said originators can address those concerns by educating real estate agents and sellers early in the transaction and clearly communicating expectations.
Understanding Military Life Matters, Too
Beyond underwriting guidelines, Boccher said lenders frequently underestimate the circumstances military families face when buying a home.
Deployments, permanent change of station (PCS) moves, spouse employment transitions, and compressed relocation timelines can complicate the mortgage process.
"A lender may view a loan as a transaction, but for a military family, it often represents stability during an otherwise uncertain period," she said.
Newrez has incorporated military family perspectives into its training and support programs, including input from veterans and military spouses within the organization.
Looking toward 2027, Boccher identified better awareness of VA eligibility, greater consistency in lending practices, and modernization of VA technology and processes as priorities.
"The VA loan is already one of the strongest mortgage products available," she said. "So, while continued modernization matters, we shouldn't overlook the education gap."
Czarinna Andres is Vice President of Content at NMP, where she leads editorial strategy, content development, and coverage of the trends, policies, and business decisions shaping the industry. Her work focuses on delivering…
The 29-year mortgage veteran joins the Rate subsidiary to serve borrowers across Dallas-Fort Worth and East Texas
Certainty Home Lending has named Tom Sherman senior vice president of mortgage lending, adding a 29-year industry veteran as the Rate subsidiary strengthens its presence in Texas.Based in McKinney, Sherman will serve borrowers throughout the Dallas-Fort Worth Metroplex and E...
Despite widespread awareness of VA home loans, misconceptions about down payments and interest rates persist, putting greater responsibility on lenders to educate veteran borrowers
At a time when our country often feels profoundly divided, we unite around support for veterans. National polling consistently shows that respect for veterans remains overwhelmingly high, crossing party, demographic, and regional lines.Veterans rank among the most favorably ...
Newrez's Brittany Boccher says qualified veterans are being directed toward conventional financing, costing originators opportunities to serve borrowers who may benefit from VA loans
Despite widespread awareness of VA home loans, misconceptions about down payments and interest rates persist, putting greater responsibility on lenders to educate veteran borrowers
VA's latest reminder about reusable benefits highlights an opportunity for originators to revisit past clients — and understand the rules around remaining entitlement