MBA RIHA updated report notes 'housing supply is being impacted by increased life expectancy'
The Mortgage Bankers Association's (MBA) Research Institute for Housing America (RIHA) released yesterday an update to its somewhat morbid research report, titled “Who Will Buy the Baby Boomers’ Homes When They Leave Them? Population Aging, Mortality, and the Future of the Housing Market.” Those prospective homebuyers who have remained on the sidelines of the housing market due to its hostility the past few years come to mind. However, they may have to bide their time a bit longer given how “supply is being impacted by increased life expectancy,” the MBA wrote in its recently revised report, in contrast to previous expectations of a sudden influx of housing supply once baby boomers downsize, move into retirement homes, or die.
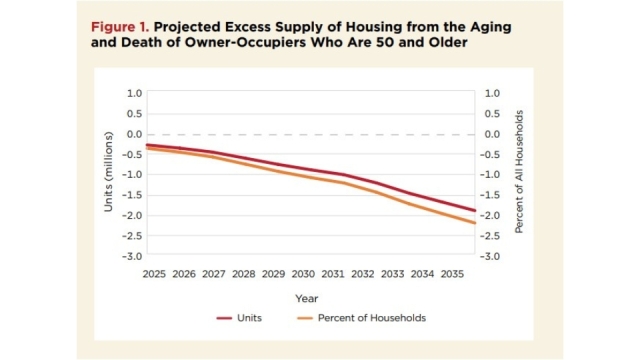
The original report, published in 2022, collected and analyzed vast research from the American Community Survey (ACS), Health and Retirement Study (HRS), American Housing Survey (AHS), and the universe of deaths from the Center for Disease Control’s Vital Statistics program, as well as projections of future population growth and mortality from the Social Security Administration (SSA) Office of the Chief Actuary. The resulting graph depicts the MBA’s original death projections for baby boomers (50+ years old) and the correlating excess supply of housing.
Graph from the MBA RIHA updated report. The dark red line shows the updated projected excess supply of homes for sale as older homeowners age and die over the next decade.
Evidently, housing supply is a function of population mortality, as well as the homeownership rate, cohort size, and how homeowners dispose of their housing assets as they age and die.
However, researchers might have been better off looking into a crystal ball or drawing tarot cards because that goldrush of housing supply is no longer in the MBA’s forecast. The report provides a detailed analysis on the rising homeownership rate for Americans over 50 years old, how the COVID-19 pandemic affected housing decisions, and how supply is being impacted by increased life expectancy.
“The findings highlight the varying patterns for older Americans as shifting demographics, the pandemic, and overall buyer attitudes have impacted buying and selling decisions,” said Edward Seiler, RIHA executive director and associate vice president of housing economics at the MBA. “It is evident that older households are aging in place, leading to updated predictions that show that there will be no excess supply of homes to the markets from older Americans moving or dying over the next decade.”
Get the NMP Daily
Essential stories, every weekday.
Essentially, older Americans are holding onto their homes longer, and there are more of them.
Since 2015, the MBA found there has been a sizable increase in the homeownership rate among seniors age 70 and older. Baby Boomers are holding onto their homes for a longer period of time. Prior to 2015, patterns in the MBA's data suggest that more of those existing homes would have been sold.
In 2022, homeownership rates among 65-plus age group were higher compared to 2015. The increase in ownership rate combined with a higher base of 65 to 70 year-olds in 2022 means that there were almost 2 million more homeowners younger than 70 than in 2015.
As the gap in ownership rates widens after age 70, the cumulative number of additional owners in rapidly increases to a peak of about 7 million more by age 85.
Projections suggest that over 8 million homes will be made available by older Americans as they age and pass away, increasing to around 9 million within the next decade. Approximately 1 million of those homes will be released due to the passing of their owners. This number is nearly double the original projection, driven by a significant rise in homeownership among older adults. On the flip side, fewer existing homes have been sold since 2015 than expected. If age-related homeownership patterns had stayed at 2014 levels, more homes would have entered the market.
Given this unmet past demand, future demand for homes supplied by older Americans is also larger and expected to grow. Overall, there will be no demographic dividend to the net supply of existing homes.
September's $53 increase ended three months of payment relief, with affordability deteriorating in 39 states
Three months of declining mortgage payments came to an end in September, as higher rates pushed the median monthly payment on purchase applications up $53 despite a slight decline in loan amounts.The median principal-and-interest payment rose to $2,215 from $2,162 in August,...
The $2 million credit line combines 30-year fixed-rate repayment with reusable borrowing capacity
Fintech lender Aven is taking its home-equity lending model into the purchase mortgage market, offering qualified buyers up to $2 million in financing and promising closings in as little as seven days.The California-based company announced Friday that its new Home Purchase L...
The mortgage giants recorded a combined $1.94 billion in third-quarter provisions, with higher projected rates extending credit exposure and signs of stress emerging among newer loans
ICE and Auction.com data reveal a growing concentration of recent mortgage vintages in foreclosure activity, with government-backed borrowers facing additional equity pressures