BankSouth Mortgage, ABS Home Mortgage, and JVM Lending are now offering $850,000 one-unit baseline limits before the Federal Housing Finance Agency establishes its official 2027 figures, expanding what had been a higher threshold occupied by Pennymac in NMP's tracker.
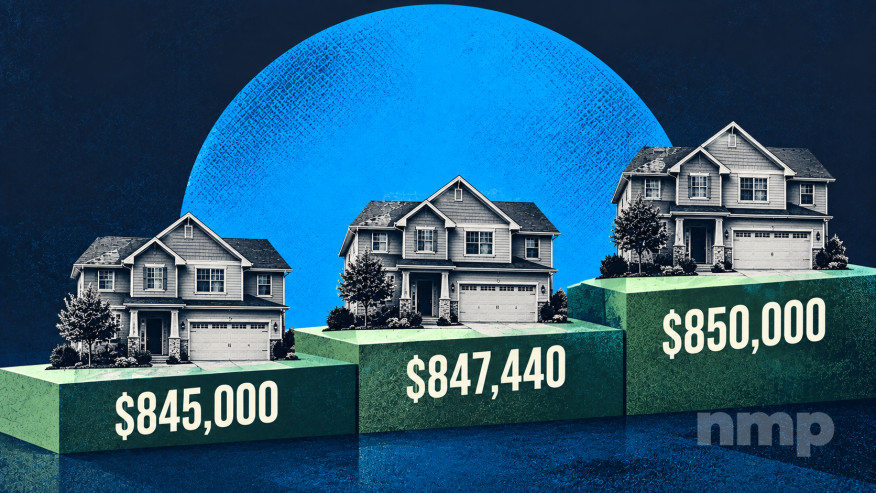
That gives four lenders a $850,000 early limit, compared with 16 parent lenders at $845,000 and two at $847,440.
The numbers remain lender-specific rather than official agency limits. And for originators, the difference between them involves more than a few thousand dollars of additional borrowing capacity. Channel access, geography, property type, closing dates, and investor requirements can determine whether a borrower can actually use the higher amount.
FHFA’s official 2026 baseline remains $832,750. A $850,000 limit provides $17,250, or approximately 2.1%, of additional room before a loan exceeds the current baseline conforming limit.
The latest NMP review found no additional qualifying lender announcement beyond the 22 parent lenders now in the tracker. Several mortgage brokers have begun advertising access to higher limits through their lending partners, but those do not represent separate lender programs and are not included.
BankSouth Changes Its Limit Within Days
BankSouth initially announced a $845,000 one-unit limit on Sept. 17. Four days later, the regional retail lender increased it again to $850,000 and made the revised amount available immediately for qualified buyers seeking conventional single-family financing.
The speed of BankSouth’s revision may be more significant than the lender’s size. Its move from $845,000 to $850,000 within days provides the clearest evidence yet that the early-limit competition is moving beyond simply getting ahead of FHFA. At least one lender has already decided its initial estimate wasn't where it wanted to stay.
More Lenders Reach $850,000
ABS Home Mortgage, which lends in Illinois, Texas, Florida, and Georgia, published a complete lower-48 grid based on a $850,000 one-unit limit:
- One unit: $850,000
- Two units: $1,088,350
- Three units: $1,315,500
- Four units: $1,634,950
The lender said qualifying loans may close under those figures now. Loans closing after FHFA announces the official limits, however, will use the amounts FHFA establishes.
That distinction matters for originators working with borrowers near the upper end of the early limit. The amount available today is not necessarily the amount that will apply to a loan closing after FHFA publishes its official 2027 figures.
JVM Lending, a division of Vellum Mortgage, has also begun offering conventional financing up to $850,000. JVM disclosed a $1.27 million high-cost limit and said the high-cost limit for a four-unit property approaches $2.5 million, although it did not publish a complete multiunit grid.
$850,000 Still Isn't The Industry Standard
Pennymac remains the most broadly accessible lender in NMP's $850,000 group because it offers the higher limit through Consumer Direct Lending, third-party origination, and correspondent channels.
Its lower-48 grid matches the amounts published by ABS Home Mortgage. Pennymac also established limits for Alaska and Hawaii beginning at $1.275 million for a one-unit property.
For correspondent sellers, however, the higher limit comes with operational conditions. Pennymac has said files may require a full appraisal, a later rerun through an automated underwriting system, and confirmation from mortgage-insurance and warehouse providers. Under specified circumstances, a loan that does not subsequently receive an eligible finding after the official limits are released could create repurchase exposure.
The other $850,000 participants are smaller retail or regional operations. Their addition does not make $850,000 the industry's dominant early limit: $845,000 remains far more widely adopted among the lenders NMP has verified.
But the market now has three distinct tiers — $845,000, $847,440 and $850,000 — and the highest of those figures is no longer represented by a single lender.
For originators, that makes comparing the programs increasingly important. The difference between $845,000 and $850,000 is only $5,000, while UWM's $847,440 sits just $2,560 below the highest tier. Whether that additional capacity is useful for a particular borrower depends on much more than the number itself, including lender channel, geography, property type, and the conditions attached to using an early limit.
2027 Early Conforming Loan Limit Tracker
Last updated Sept. 23, 2026.
FHFA has not established the official 2027 conforming loan limits. The amounts below are lender-specific early limits and may carry separate product, pricing, eligibility, closing-date, and delivery requirements.
Lender | Announcement Date | One-Unit Baseline Limit | Availability |
|---|
Rocket Mortgage/Rocket Pro | Sept. 10, 2026 | $845,000 | Rocket retail and Rocket Pro broker channels. Lower-48 limits are $1,081,950 for two units, $1,307,800 for three units, and $1,625,350 for four units. Alaska and Hawaii limits begin at $1,267,500. |
CrossCountry Mortgage | Sept. 10, 2026 | $845,000 | Available through CrossCountry Mortgage’s Early Bird Program, subject to program and underwriting requirements. |
NOVA Home Loans | Sept. 10, 2026 | $845,000 | Available through NOVA loan originators. Product, underwriting and geographic requirements may vary. |
Waterstone Mortgage Corp. | Sept. 10, 2026 | $845,000 | Waterstone retail channel; applies to qualifying loans funded on or after Sept. 10. |
Fairway Independent Mortgage Corp. | Sept. 14, 2026 | $845,000 | Fairway distributed-retail channel; effective Sept. 14 and subject to lender and program guidelines. |
OCMBC: LoanStream Mortgage, GIANT Lending, RISE TPO and LendingPros | Sept. 14, 2026 | $845,000 | Wholesale availability through multiple OCMBC divisions. Product availability and restrictions vary by division. |
Supreme Lending | Sept. 14, 2026 | $845,000 | Available for eligible new applications taken on or after Sept. 14, subject to product and underwriting requirements. |
CMG Home Loans | Sept. 14, 2026 | $845,000 | Effective Sept. 21, subject to CMG product, pricing and underwriting requirements. |
American Pacific Mortgage | Sept. 15, 2026 | $845,000 | Distributed-retail channel through local originators. APM disclosed a $1,267,500 high-cost limit. |
EMM Loans | Sept. 15, 2026 | $845,000 | Available for eligible new loans beginning Sept. 14. Public materials did not specify retail-versus-wholesale availability. |
Newrez | Sept. 15, 2026 | $845,000 | Newrez correspondent channel; all commitment types on new locks dated Sept. 15 or later. AUS-rerun, appraisal and potential repurchase requirements apply. |
Southern Trust Mortgage | Approx. Sept. 15, 2026 | $845,000 | Distributed-retail channel for qualifying conventional purchase and refinance loans. Early multiunit and high-cost amounts were not disclosed. |
Guild Mortgage | Sept. 16, 2026 | $845,000 | Guild retail channel; available beginning Sept. 17. Detailed eligibility, pricing and delivery requirements were not publicly disclosed. |
Movement Mortgage | Sept. 16, 2026 | $845,000 | Retail channel for eligible one-unit properties in the continental United States. Property, credit, DTI, LTV and program restrictions apply. |
United Wholesale Mortgage | Sept. 16, 2026 | $847,440 | Wholesale broker channel for eligible conventional and VA loans. Limits are $1,085,059 for two units, $1,311,535 for three units and $1,630,005 for four units. |
Pennymac | Sept. 16, 2026 | $850,000 | Consumer Direct Lending, TPO and correspondent channels. Lower-48 limits are $1,088,350 for two units, $1,315,500 for three units and $1,634,950 for four units. Alaska and Hawaii limits begin at $1,275,000. |
BankSouth Mortgage | Sept. 21, 2026 (revised) | $850,000 | Distributed-retail channel; available now for qualified buyers seeking conventional single-family financing. Originally announced at $845,000 on Sept. 17. |
Franklin Loan Center | Sept. 18, 2026 | $845,000 | Retail channel for conventional financing. Multiunit limits and an effective-date cutoff were not disclosed; Franklin said high-cost limits remained to be announced. |
JVM Lending/Vellum Mortgage | Sept. 18, 2026 | $850,000 | JVM consumer channel. A $1.27 million high-cost limit was disclosed, but a complete multiunit grid was not published. |
ABS Home Mortgage | Sept. 20, 2026 | $850,000 | Retail/direct channel in Illinois, Texas, Florida and Georgia. Lower-48 limits are $1,088,350 for two units, $1,315,500 for three units and $1,634,950 for four units. |
Neighborhood Loans | Sept. 21, 2026 | $847,440 | Distributed-retail channel. Limits are $1,085,059 for two units, $1,311,535 for three units and $1,630,005 for four units. |
Direct Mortgage Loans | Sept. 22, 2026 | $845,000 | Distributed-retail channel through select investors for qualifying conventional loans locked on or after Sept. 17. |
Current FHFA baseline: $832,750
- Verified parent lenders: 22
- Lenders at $845,000: 16
- Lenders at $847,440: 2
- Lenders at $850,000: 4
- Increase at $845,000: $12,250, or approximately 1.5%
- Increase at $847,440: $14,690, or approximately 1.8%
- Increase at $850,000: $17,250, or approximately 2.1%
NMP will continue updating this tracker as additional lenders announce early 2027 conforming loan limits and after FHFA publishes the official limits.