A man with his fingers on the pulse of the housing market is hopeful that the worst is over. That being said, the pulse of the housing market has been tough to gauge for the last several years.
With increasing employment and inventory rising as well, six to eight more interest-rate cuts are coming in the foreseeable future, National Association of Realtors (NAR) Chief Economist Lawrence Yun predicts.
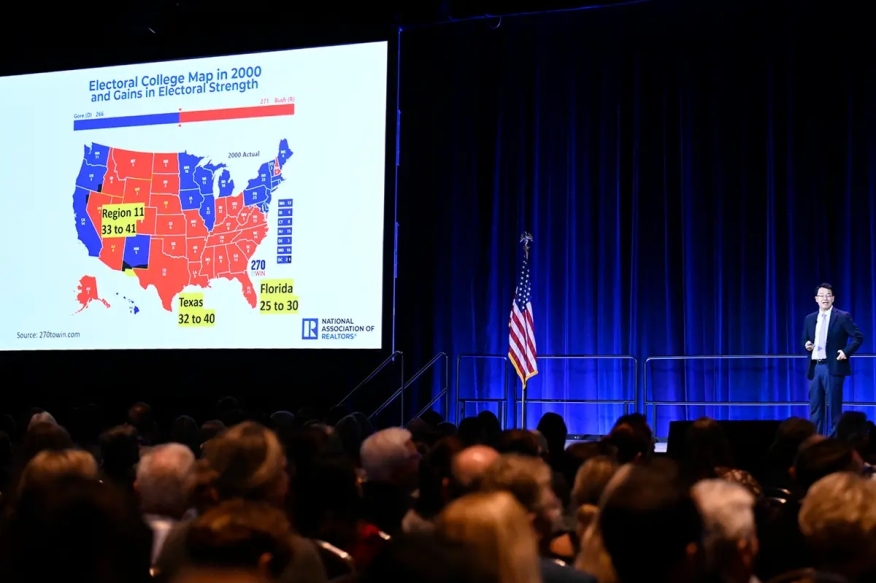
Yun shared his outlook for 2025 and 2026 during the 2024 NAR NXT, The Realtor Experience, in Boston recently.
“2024 has been a very difficult year on many fronts,” Yun told his audience. “We did not get the home sales recovery this year after an awful 2023.”
The Federal Reserve just issued a 25-basis-point cut to its federal funds rate, which now stands at a target range of 4.50%-4.75%.
Additionally, mortgage holders across the nation withdrew $48 billion of home equity in the third quarter of 2024 — the largest amount of quarterly equity withdrawn in the past two years. Home equity lending is expected to continue increasing by several organizations, including the Intercontinental Exchange (ICE), which forecasted it in its Nov. 2024 ICE Mortgage Monitor Report.
NAR estimated the net worth of homeowners ($415,000) and renters ($10,000) in 2024, and Yun noted the vast difference.
The number of renter households rose 2.7% on an annual basis in the third quarter to a record 45.6 million, three times faster than the 0.9% increase in homeowner households, which now total a record 86.9 million, according to a recent Redfin analysis.
“Homeowners’ wealth steadily rises while renters’ wealth does not,” he pointed out. “If you don’t enter the housing market, you are in the renter class where wealth is not being accumulated. If you want to participate in the housing market, the sooner you get in, the sooner you accumulate wealth.”
The stock market is optimistic that job growth will continue, but a Trump presidency doesn’t necessarily mean lower mortgage rates, Yun added.
“Mortgage rates in his first term (at 4%) were the good old days. Are we going to go back to 4%? Per my forecast, unfortunately, we will not. It’s more likely that we’ll go back to 6%. That will be the new normal, bouncing around 5.5%-6.5%.”
He also gave advice to the chair of the Federal Reserve on the pace and timing of rate cuts: “My advice to Jerome Powell: do it in January, rather than December. Today, we have a massive budget deficit at a time when we are not in an economic recession,” explained Yun.
“Clearly president-elect Trump will not stop tax cuts – he will extend or expand them," he continued. "There will be less mortgage money available because the government is borrowing so much money. However, if the Trump administration can lay out a credible plan to reduce the budget deficit, then mortgage rates can move downward.”
The industry is doing everything it can to increase inventory, with new construction and existing-home sales. Still, affordability presents an enduring challenge to lenders hoping to access more mortgage demand. Many sidelined borrowers have been shopping for a year or more.
“Maybe the worst is coming to an end,” added Yun. “Directionally, I think there’s going to be roughly a 10% boost of existing-home sales in 2025 and 2026.”
Yun projects new home sales to be 11% higher in 2025 and 8% higher in 2026. He also forecasts the median home price to be 2% higher in both 2025 and 2026.