Are Investors Fueling The Rapid Decline In Housing Affordability?

It might be a case, instead, of higher prices attracting investors

Housing Affordability

So, Which Came First?

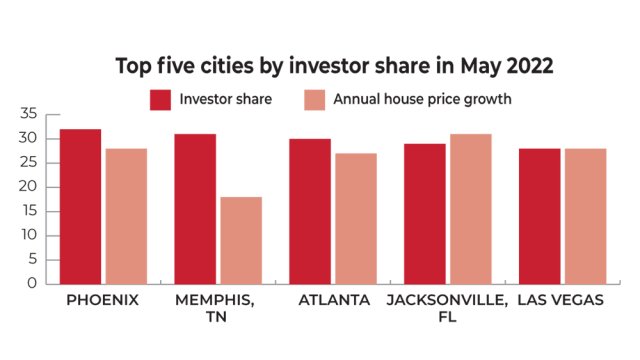
It turns out, as one might expect, that house price growth and investor participation are positively correlated. While there is substantial variation from city to city, we found cities with a larger investor share of sales generally experienced greater house price growth over the last year. For example, Phoenix, Atlanta and Jacksonville had the largest investor share in May as well as some of the fastest year-over-year house price growth rates in the country.

The top five cities by investor share in May 2022 were:

• Phoenix
Investor share: 32%
Annual house price growth: 28%

• Memphis, Tenn.
Investor share: 31%
Annual house price growth: 18%

• Atlanta
Investor share: 30%
Annual house price growth: 27%

• Jacksonville, Fla.
Investor share: 29%
Annual house price growth: 31%

• Las Vegas
Investor share: 28%
Annual house price growth: 28%

However, as the adage goes, correlation is not causation. Investor purchases could be driving price appreciation, or it could be the other way around, or both. There could also be a third factor driving both the growing investor share of purchases and house price appreciation simultaneously — a pandemic-driven surge in housing demand against a limited supply of homes for sale. It’s difficult to know with a high degree of certainty, but recent history provides some insight.

Pandemic-Priced Properties

The recent growth in demand to own residential properties is, in part, a consequence of a pandemic-induced flight away from densely populated cities and corresponding increase in demand for remote working space. This migration to more suburban cities and the search for more space accelerated demand in key markets, contributing to record house price appreciation.

Top Five Cities

As people became priced out of the purchase market, they turned to the rental market, which in addition to ongoing new rental household formation, contributed to rents growing at a record pace. The combination of rapid rent growth and house price appreciation attracted even more investors flush with capital. This explanation is compelling in part because annual house price growth was already in the double digits before the investor share picked up in the second half of last year. In other words, there’s a strong case to be made that house price growth was influential in driving up the investor share.

Rising investor participation in the residential housing market created additional competition for the already-limited number of homes available for purchase, compounding the already-rapid pace of price growth. One estimate for the current national shortage in housing units is 3.8 million units. This pre-existing shortage made house prices highly responsive to the increased demand from investors.

Permanent Phenomenon Or Passing Phase?

If greater investor participation continues to contribute to elevated demand relative to limited supply, then house prices are likely to remain positive despite rising interest rates. If house price growth is enticing greater investor participation, then we would expect to see declining investor participation in the residential housing market as house prices decelerate. Currently, investor participation remains near all-time highs, but mortgage purchase applications were down 16% year-over-year in a late-July report, indicating a declining buyer pool for potential homes that may translate to slower price growth in the near term.

However, the ongoing housing shortage will continue to make home prices particularly responsive to changes in demand. So, which came first, greater investor participation or faster house price growth? Perhaps, neither. It seems that both were predated by pandemic-accelerated demand amid a historic supply shortage.

As people became priced out of the purchase market, they turned to the rental market, which in addition to ongoing new rental household formation, contributed to rents growing at a record pace. The combination of rapid rent growth and house price appreciation attracted even more investors flush with capital. This explanation is compelling in part because annual house price growth was already in the double digits before the investor share picked up in the second half of last year. In other words, there’s a strong case to be made that house price growth was influential in driving up the investor share.

Rising investor participation in the residential housing market created additional competition for the already-limited number of homes available for purchase, compounding the already-rapid pace of price growth. One estimate for the current national shortage in housing units is 3.8 million units. This pre-existing shortage made house prices highly responsive to the increased demand from investors.

Permanent Phenomenon Or Passing Phase?

If greater investor participation continues to contribute to elevated demand relative to limited supply, then house prices are likely to remain positive despite rising interest rates. If house price growth is enticing greater investor participation, then we would expect to see declining investor participation in the residential housing market as house prices decelerate. Currently, investor participation remains near all-time highs, but mortgage purchase applications were down 16% year-over-year in a late-July report, indicating a declining buyer pool for potential homes that may translate to slower price growth in the near term.

However, the ongoing housing shortage will continue to make home prices particularly responsive to changes in demand. So, which came first, greater investor participation or faster house price growth? Perhaps, neither. It seems that both were predated by pandemic-accelerated demand amid a historic supply shortage.

This article originally appeared in National Mortgage Professional, on the week of October 1, 2022.
About the author
Xander Snyder is a senior economist at First American.
Published on
Oct 03, 2022
More from NMP Magazine
NMP
VA Home Loans: Veterans Deserve Better Information, Better Experiences

Despite widespread awareness of VA home loans, misconceptions about down payments and interest rates persist, putting greater responsibility on lenders to educate veteran borrowers

Pat Schlimmer
NMP
NMP's 2026 Best Military Lenders

National Mortgage Professional’s Best Military Lenders award honors the companies that go above and beyond for active-duty military members, veterans, reservists, and their families.

National Mortgage Professional
NMP
NMP's 2026 Best Military Originators

Every year, NMP sets out to find the originators who do far more than close VA loans. This year’s 10 honorees have turned military lending into a calling.

National Mortgage Professional
NMP
The Cost of Keeping America Building

With buyers struggling to afford homes and construction costs squeezing margins, builders are turning to private capital, aggressive incentives, and new technology to keep projects moving. But how long can those strategies hold?

Czarinna Andres
NMP
Appraisal Fees Under Fire

Appraisers face stagnant pay and rising costs as AMCs defend their fees and new technology reshapes the industry

Czarinna Andres
NMP
The Hidden Cost Of Appraisal Uncertainty

As home equity lending grows, lenders need a better way to resolve conflicting property evidence before it creates costly setbacks

Gerald M. Green

Webinars

AI Digital Assets Are Here: Is Your Mortgage Business Ready?

Explore how artificial intelligence, blockchain technology, and digital assets are shaping the future of mortg...

Webinar
Nov 10, 2026
Investor Confidence in Today’s Non-QM And Why Originators Are Paying Attention... A Virtual Town Hall

We host Angel Oak Mortgage Solutions for a special 2021 edition of their virtual town hall series they ran fro...

Webinar
Apr 08, 2021
How to Help Real Estate Pros in a Post-Refi World

Hear from Melissa Merriman, REALTOR® with The Melissa Merriman Team at Keller Williams, on what real estate pr...

Webinar
Mar 18, 2021
Connect with your local mortgage community.

Meet your your colleagues, both national and local, by attending an event in your area.