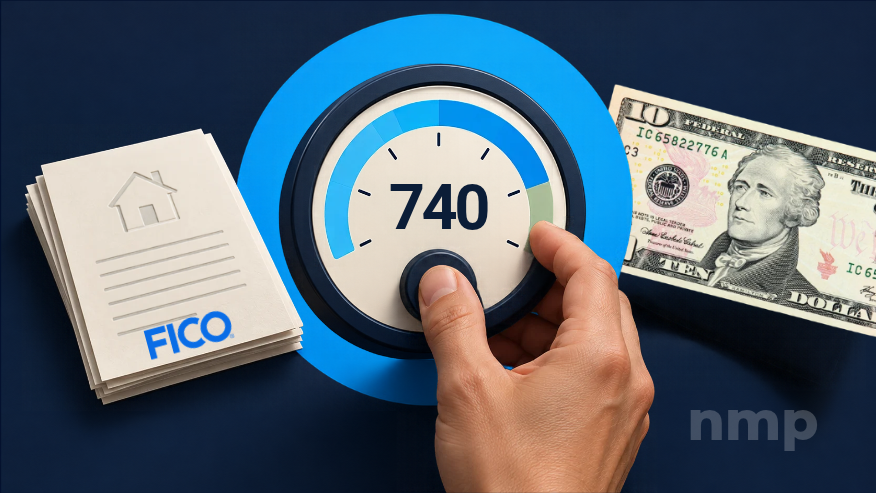
FICO is offering lenders and brokers a hold on its $10 wholesale mortgage score price in exchange for a commitment to keep buying its scores.
The company announced last week that lenders and brokers enrolled in its Preferred Program through participating tri-merge resellers will receive Classic FICO and FICO Score 10T as a bundle at the same wholesale price as a year earlier. Eligibility is tied to lenders having committed to FICO through those partners.
The offer arrives while credit bureaus are giving originators more ways to choose which scores they purchase — and delay some purchases until an application moves further along. For lenders evaluating those options, the value of FICO’s price hold will depend partly on the purchasing obligations attached to it.
For an originator already purchasing FICO throughout the application process, maintaining the score price could help with budgeting. A lender working to reduce early-stage score purchases would also need to account for the program’s purchase requirements. A flat unit price does less to control spending if the arrangement calls for more purchases than the lender otherwise would make.
Credit Purchasing Is Changing
Earlier this month, Equifax and TransUnion introduced tools that separate credit-report purchases from score purchases, giving lenders more flexibility over when those expenses occur.
TransUnion’s First Look Functionality for Mortgage allows lenders to begin with credit information and add scores later. When eligibility and matching requirements are met, additional scores can be obtained without purchasing another credit report. The offering supports soft- and hard-pull workflows through mortgage resellers.
Equifax’s Mortgage Score Select allows lenders and brokers to request a credit file with Classic FICO, VantageScore 4.0, or no score. Customers can retrieve the file again within 24 hours for $1, plus the cost of any selected score.
Those products target a recurring origination expense: credit purchased for applications that never close. They also give lenders a way to stage purchases as they determine whether a borrower can move forward.
TransUnion separately extended its 99-cent VantageScore 4.0 mortgage pricing through the end of 2028, with no additional score charge when purchased alongside FICO. That advertised price, like FICO’s, is not an all-in credit-report quote.
A Place In The Credit Order
Lenders’ scoring preferences are also changing. Rocket Mortgage announced that it would make VantageScore 4.0 its preferred model for eligible loans during the fourth quarter, following several months of testing alongside FICO. Its broker channel, Rocket Pro, would continue offering both models.
That shift gives FICO a reason to keep its scores in the purchasing process even where lenders are willing to underwrite with an alternative. Bundling Classic FICO with 10T also puts both generations of its mortgage score into the same commercial offering.
For brokers and lenders, the useful comparison is the total credit expense across their pipeline: initial inquiries, additional scores, repeat reports, and applications that fall out before funding. Reseller terms and investor requirements will shape that calculation.