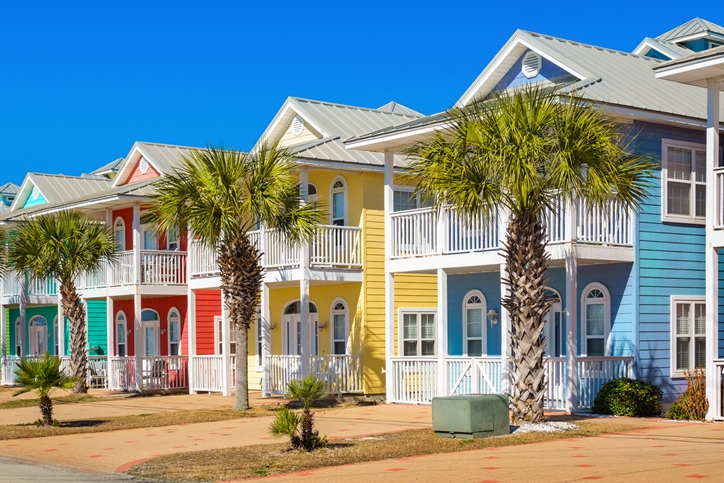
Policies put in place to spur lending for first-time primary home buyers in markets heavily populated by second homes failed to work as intended, according to a new working paper from the Consumer Financial Protection Bureau.
But the increase put in place in 2022 that raised the up-front fees on loans on vacation homes guaranteed by the government sponsored enterprises (GSEs) did make it more expensive for those borrowers — to the tune of $1,260 on average every year for the typical loan, the paper found.
And as a result, there was a “substantial” 23% decline in GSE originations for second residences with high loan-to-value ratios.
In counties where holiday homes accounted for a third or all sales, the paper’s authors — Zachary Blizard, Thomas S. Conkling, and Georgia Ronis von Helms — estimate that the policy change reduced overall mortgage lending by roughly 5% with a “very small” offsetting increase in primary home lending.
The Federal Housing Finance Agency’s stated goal for raising the fee was “to strengthen the enterprises’ safety and soundness and to ensure access to credit for first-time home buyers and low- and moderate-income borrowers.” But it didn’t work out that way.
Prior to 2020, about half of all second home purchases were financed by GSE-backed loans. The number rose to more than 60% in 2020, then dropped back to 50% in 2021. But when the GSE fee increase was announced in January 2022, their share slid to 30% in just three months.
While the substantial drop could reflect pure substitution by lenders offering non-GSE financing, the better explanation, the paper's authors speculated, is that the fee increase reduced credit supply for high-LTV second residence loans.
The evidence suggests that “while lenders and consumers may have been able to somewhat lessen the effects of the fee increase through substitution to non-GSE loans or other loan types, the fee increase meaningfully reduced credit for second residence lending overall,” they wrote.
As a result, the working paper found an average price increase across both GSE and non-GSE mortgages that “reflects substantially higher costs of credit for secondary residence borrowers.”
For an average second residence loan amount of $359,000, the higher fee amounts to $1,260 annually in additional costs. But the costs are even higher for GSE loans alone — the rate spreads rose by 0.52 basis points, equating to $1,867 per year in additional costs on the same $359,000 mortgage.
Not only did GSE-backed financing become more costly, it became more scarce, according to the paper. The evidence, it states, shows that borrowers seeking high-LTV second residence mortgages "are significantly affected by the availability and pricing of GSE credit, and that such borrowers are not able to fully substitute to other credit options in the market.”
The fee increase didn’t boost primary residence lending by the GSEs, either, the authors reported. “We do not find evidence of increased lending for primary residence home buyers, and very limited offsetting increases in lending for investment properties,” the paper's authors wrote.
The lack of a measurable impact on owner-occupant lending could be due to the particular dynamics of local markets with many second residences, the prevalence of competing cash buyers, or the characteristics of second home properties, the paper noted.
Here, the writers admit, more research is necessary to understand buyer and seller behavior in second home-dominated housing markets. “Understanding these dynamics could inform the design and expected effects of policies that aim to influence access to credit and home ownership,” the paper stated.