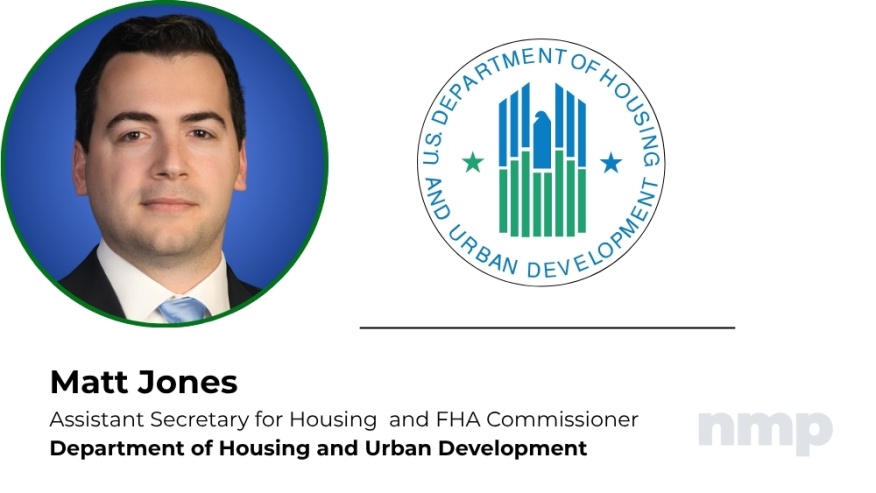
President Donald Trump has nominated Matthew Jones, the official currently overseeing the Federal Housing Administration’s single-family mortgage programs, to serve as assistant secretary for housing at the Department of Housing and Urban Development and FHA commissioner.
The White House sent Jones’s nomination to the Senate on Monday. He will require Senate confirmation.
For mortgage lenders, the appointment would put an official with both agency and industry experience in charge of FHA’s underwriting, appraisal, servicing, and mortgage insurance policies. Jones would also inherit the agency’s transition to newer credit-scoring models and continued pressure to reduce the cost and complexity of FHA lending.
Jones currently serves as HUD’s deputy assistant secretary for single-family housing. In that position, he oversees an FHA insurance portfolio of more than 8 million loans with an unpaid principal balance exceeding $1.6 trillion as of the end of fiscal 2025.
A Familiar Face
Jones previously served as associate vice president of government housing finance at the Mortgage Bankers Association. He also worked as a senior adviser for capital markets at Amerifirst Home Mortgage and served as senior counsel for both the Senate Banking, Housing, and Urban Affairs Committee and the Senate Finance Committee.
FHA policy reaches well beyond borrower eligibility. Agency decisions can affect documentation requirements, appraisal reviews, quality-control obligations, indemnification exposure, servicing costs, and the viability of FHA products within a lender’s loan mix.
Jones’s promotion would also eliminate much of the learning curve normally associated with a new commissioner. He already knows FHA’s internal operation and has been involved in an administration that has made regulatory streamlining a central part of its housing agenda.
The nomination suggests the Trump administration wants to continue its current FHA direction under an official who understands both the agency’s operational machinery and lenders’ complaints about cost and complexity. The unanswered question is whether that familiarity produces incremental policy changes or more substantial reductions in the expense of originating and servicing FHA loans.
Credit Scores And Lender Requirements Await
If confirmed, Jones would assume the role as lenders prepare for a significant credit-score transition.
Beginning with case numbers assigned on or after Jan. 1, 2027, FHA will accept VantageScore 4.0 and FICO Score 10T in addition to the Classic FICO model, according to HUD’s implementation guidance. Lenders choosing to use the newer models will need to prepare their systems, workflows, vendor relationships, and underwriting processes.
Jones would also inherit FHA’s recent effort to reduce administrative burdens. In June, the agency issued a package of policy revisions affecting mortgagee approval, quality control, appraisals, renovation lending, servicing, and claims. Those changes included some relief for lenders handling early-payment defaults caused by natural disasters.
For originators, the significance will be measured by whether FHA becomes easier and less expensive for lenders to offer. Operational costs and compliance exposure can influence lender overlays, product availability, and how aggressively lenders price FHA loans.
MBA Backs Its Former Executive
MBA President and CEO Bob Broeksmit, CMB, endorsed Jones’s nomination Tuesday.
“MBA enthusiastically supports the nomination of Matt Jones to serve as HUD Assistant Secretary of Housing and FHA Commissioner,” Broeksmit said. “Matt brings an impressive combination of hands-on mortgage industry experience, deep knowledge of government housing finance, and a strong understanding of how FHA programs can better serve homebuyers, renters, and lenders. His previous leadership of MBA’s government housing finance portfolio and current role overseeing FHA’s single-family operations provide him with valuable perspective on the opportunities and challenges facing the agency.
“We will work with Matt, Secretary Turner, and HUD staff to continue to modernize and streamline FHA’s single-family and multifamily lending programs, cut unnecessary red tape, and lower costs for homebuyers and renters.”
MBA’s emphasis on modernization, regulatory relief, and lower costs offers a clear indication of what lenders expect from Jones if he is confirmed.
A Financially Strong FHA Fund
Jones would take over an agency whose primary mortgage insurance fund remains well above its statutory minimum.
FHA’s Mutual Mortgage Insurance Fund held $188.9 billion in capital as of Sept. 30, 2025, an increase of $16.1 billion from the prior fiscal year, according to HUD’s annual financial report. Its overall capital ratio stood at 11.47%, more than five times the congressionally mandated minimum of 2%.
More than 83% of FHA forward purchase endorsements in fiscal 2025 went to first-time homebuyers, underscoring the program’s importance to originators working with borrowers who have limited savings or less-established credit profiles.
The strength of the insurance fund provides Jones with a solid financial position but also ensures that borrower costs will remain part of the policy conversation. Any future mortgage insurance premium reduction could lower monthly payments and make FHA financing more competitive, although neither the White House nor Jones has announced plans for such a reduction.
If confirmed, Jones would succeed Frank Cassidy, who left HUD and returned to Walker & Dunlop this summer. Ginnie Mae President Joseph Gormley has served as acting FHA commissioner since Cassidy’s departure.