Median purchase application payments rose 3.5% from the end of 2023 — the last 'worst year in decades' for home sales
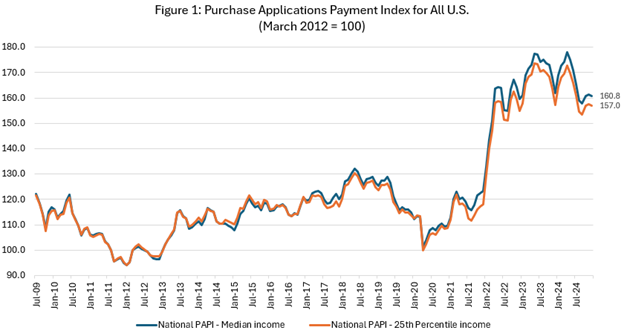
Homebuyer affordability remained flat in December as the national median mortgage payment applied for by purchase applicants declined just $6 to $2,127 — the same level they were at in October — from $2,133 in November.
That payment is $72 higher than a year earlier, however, marking a 3.5% annual increase, per the latest figures from the Mortgage Bankers Association (MBA), which tracks changes in borrowers’ payment-to-income ratios through its Purchase Applications Payment Index (PAPI).
At $1,866 last month, the national median mortgage payment for FHA loan applicants was $32 less than November's (-1.68%), but $44 higher than a year ago (+2.4%). The national median mortgage payment for conventional loan applicants was $2,128, down $5 from November (-0.23%), but up $75 from a year ago (+3.65%).
An increase in MBA’s PAPI indicates declining borrower affordability conditions, meaning that the mortgage payment to income ratio (PIR) is higher due to increasing application loan amounts, rising mortgage rates, or a decrease in earnings.
The nominal month-over-month change in December was “the result of somewhat volatile mortgage rate movements and moderating home-price growth,” said Edward Seiler, MBA’s Associate Vice President, Housing Economics, and Executive Director, Research Institute for Housing America.
Source: Mortgage Bankers Association
Typical mortgage payments, including property taxes and skyrocketing insurance costs, continue to eat up larger portions of monthly incomes, making it difficult for younger, first-time homebuyers to access the market, particularly given the lack of affordable, entry-level homes.
The MBA reports that median earnings rose 4.1% compared to one year ago, and while payments increased 3.5%, the significant earnings growth means that the PAPI is down 0.6 % on an annual basis. For borrowers applying for lower-payment mortgages (the 25th percentile), the national mortgage payment increased to $1,446 in December from $1,436 in November.
Seiler calls 2024 "a sluggish year for home sales" due to the nation's widespread affordability challenges. He adds “[The] MBA expects 2025 conditions will improve as housing supply increases, giving prospective buyers more options and putting less pressure on their budgets.”
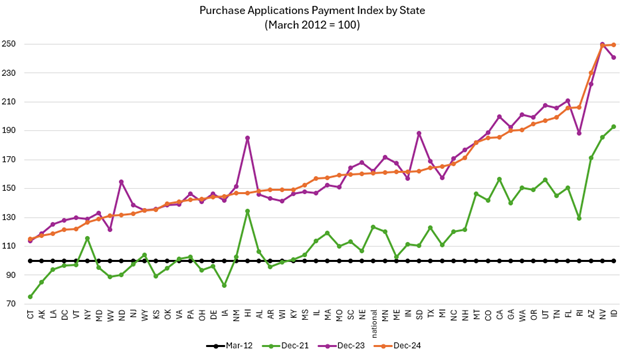
The top five states with the highest PAPI — the worst housing affordability from the perspective of payment-to-income ratios — were: Idaho (249.5), Nevada (249.0), Arizona (230.3), Rhode Island (206.3), and Florida (205.8).
Source: Mortgage Bankers Association
The top five states with the lowest PAPI — the best housing affordability from the perspective of payment-to-income ratios — were: Connecticut (115.2), Alaska (117.3), Louisiana (118.9), D.C (121.3), and Vermont (122.1).
The Builders’ Purchase Application Payment Index (BPAPI) showed that the median mortgage payment for purchase mortgages from MBA’s Builder Application Survey increased to $2,500 in December, up from $2,481 in November.
Proposition 37 could open new purchase lending opportunities, but financing costs and borrower qualification will determine its reach
California voters have approved a $25 billion homebuyer financing initiative that could create new purchase mortgage opportunities for lenders and brokers, particularly those working with homebuilders.Proposition 37, which passed with more than 60% of the vote in the Nov. 3 ...
As investor purchases decline, DSCR loans capture a growing share of Non-QM lending, creating opportunities for brokers who understand the differences between lender programs
Real estate investors are buying fewer homes than they did a year ago, yet debt service coverage ratio (DSCR) lending continues to gain ground in the market. A big part of the reason is that DSCR loans are purpose-built for property investors. Agency loans qualify borrowers ...