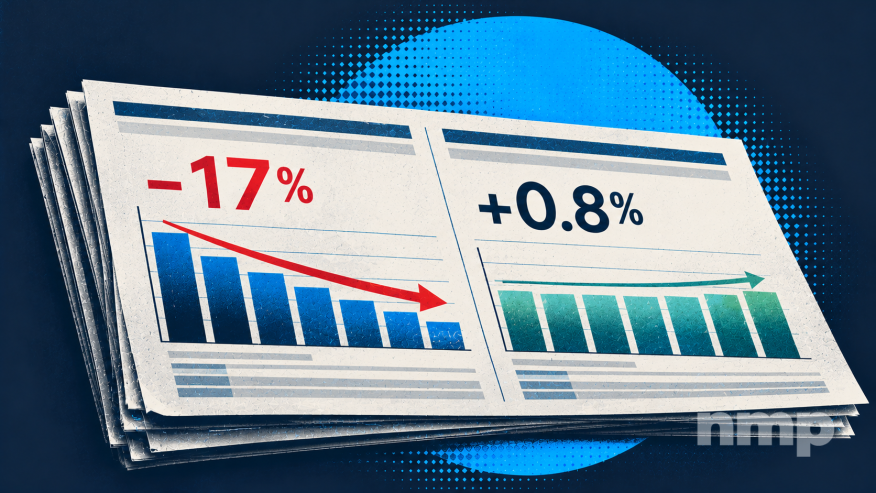
The Mortgage Bankers Association forecasts refinance originations falling 17% to $571 billion in 2027, with purchase volume increasing just 0.8% to $1.42 trillion. Total single-family lending would decline 5% to just under $2 trillion.
Released Oct. 11 at MBA’s annual convention in Chicago, the forecast puts loan count at 5 million, down 5.6% from the 5.3 million projected for 2026.
That leaves a tougher growth calculation: increasing production would require winning a larger share of business or finding opportunities within segments that outperform the broader market.
Less Help From Rates
MBA expects the 30-year rate to average 7.3% in the fourth quarter of 2026 and remain above 7% through 2027.
Chief economist Mike Fratantoni expects borrowing costs to ease from recent peaks while remaining higher than previously projected. MBA also anticipates two additional quarter-point Federal Reserve hikes, in December and early 2027.
The rate outlook is a forecast, not a commitment from policymakers or a guarantee of where loan pricing will land. MBA flagged geopolitical and financial-market shocks among the risks that could change the economic path.
A Growing Segment In A Contracting Market
September’s lock activity offers one example of where business is expanding.
Optimal Blue’s latest Market Advantage report showed Non-QM lock volume rising 8% from August while overall locks fell 2.1%. Non-QM represented about 12% of September activity.
Investor and debt-service coverage ratio loans accounted for 33.3% of the Non-QM segment, bank-statement loans represented 29.9%, and other expanded-guideline programs made up 36.8%.
Optimal Blue measures locks in participating lenders’ pipelines; MBA forecasts national originations. But the September results show why a declining market does not mean every product category is moving in the same direction.
At NMP’s recent Non-QM Town Hall, lender executives pointed originators toward investors, self-employed borrowers, and applicants whose earlier deals did not fit agency guidelines.
The discussion also highlighted equity financing for homeowners reluctant to replace an existing first mortgage. Those opportunities depend on a borrower’s financing need, rather than solely on the availability of a lower rate.
Volume Is Only Part Of The Equation
MBA’s separate second-quarter performance report showed independent mortgage banks and bank mortgage subsidiaries earning an average pretax production profit of $973 per loan, up from $727 in the first quarter. The average production margin was 25 basis points, compared with a historical quarterly average of 39 basis points.
“Average net production profits remained positive for the fifth consecutive quarter,” said Marina Walsh, MBA’s vice president of industry analysis, in the August report.
Lower costs helped. Per-loan production expenses fell to $10,936 from $11,898, even while production revenue declined. Including servicing and production, 85% of surveyed firms reported pretax profits.
MBA’s forecast leaves purchase lending as the larger source of business, with little projected market growth to lift individual producers. An originator can outperform that forecast. The harder question is where the additional loans will come from.